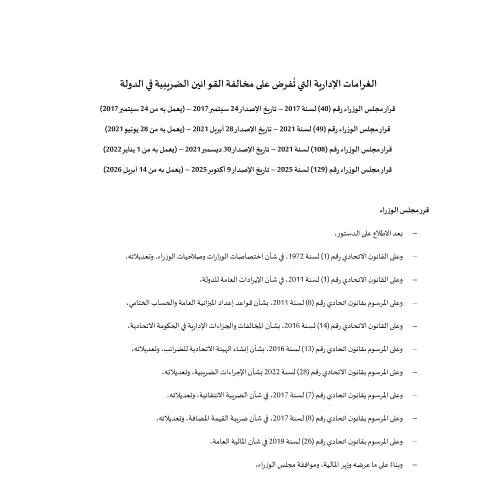
Navigating the Administrative Penalties Framework: Understanding Decision No. 40 of 2017
In the context of the UAE's evolving tax system, Decision No. 40 of 2017, issued by the Council of Ministers, plays a crucial role in defining the framework for administrative penalties imposed for violations of tax laws. This document not only establishes the penalties but also outlines the responsibilities of taxpayers and the relevant authorities. Diving into this decision unveils a structured process that affects both individuals and entities engaged in business activities in the UAE.
A Historical Perspective on Tax Regulations in the UAE
The introduction of Decision No. 40 of 2017 marked a significant step in the UAE’s tax governance, laying the groundwork for a more organized tax landscape. Prior to this decision, the UAE had minimal regulatory frameworks concerning tax obligations, leading to confusion and inconsistencies in compliance.
To grasp the importance of this decision, we must consider the backdrop against which it was developed:
- Enactment of the Federal Law No. 1 of 1972 regarding the powers of ministries.
- Introduction of Federal Law No. 1 of 2011 concerning public revenues.
- Implementation of Decree-Law No. 8 of 2011 on the establishment of the Federal Tax Authority (FTA).
This progression culminated in the enactment of the Value Added Tax (VAT) and the Excise Tax, which necessitated the establishment of a systematic approach to enforce compliance through administrative penalties.
The Core Components of Decision No. 40 of 2017
Decision No. 40 is a comprehensive document that outlines various aspects related to administrative penalties, including definitions, the scope of penalties, and processes for objections. Understanding these components is vital for both compliance and governance.
Defining Key Terms and Concepts
Understanding the terminology used in the decision is key to navigating its implications. The decision defines essential terms such as:
- Administrative Penalties: Financial penalties imposed on individuals or entities for contravening tax laws.
- Taxable Person: Individuals or corporate entities subject to tax laws.
- Tax Declaration: The submission of tax-related information as prescribed by the FTA.
These definitions provide a foundation for interpreting the subsequent penalties detailed in the decision.
Understanding the Penalties and Their Implications
The decision specifies different scales of penalties for various infractions, categorized in tables attached to the document. Understanding these penalties is crucial as they can significantly impact financial outcomes for taxpayers.
Category of Violations and Corresponding Penalties
Table 1 of the decision outlines specific violations and their associated penalties. For example:
| Type of Violation | Penalty Amount (in AED) |
|---|---|
| Failure to maintain required records | 10,000 for the first violation, 20,000 for repeat within 24 months |
| Failure to submit tax documents in Arabic when requested | 5,000 |
| Failure to register for tax within the stipulated timeframe | Varies based on specific circumstances |
These penalties serve to enforce compliance, reflecting the UAE’s commitment to maintain a structured tax system.
The Lifecycle of Filing and Addressing Penalties
Upon receiving a penalty notification, taxpayers must navigate a series of administrative procedures. It is essential to understand how to manage this process effectively to mitigate potential repercussions.
Filing Procedures and Compliance Timeline
From the moment a taxpayer receives a penalty notice, the timeline for compliance and potential appeals becomes critical. Understanding this timeline can aid in timely responses:
- Notification of Penalty: Taxpayers are notified via official channels (as per the tax procedures law).
- Deadline for Response: Taxpayers typically have 30 days to respond or appeal the penalty.
- Resolution Process: The FTA reviews the appeal, which may take additional time.
Engaging promptly with the FTA can facilitate a more favorable outcome.
Managing Disputes: What to Do in Case of Non-Compliance or Errors
In scenarios where a taxpayer believes a penalty has been wrongly imposed, it is imperative to know the recourse available under the laws governing tax procedures in the UAE.
The Objection Process and Legal Recourse
As per Article 5 of Decision No. 40, individuals have the right to contest administrative penalties. The process typically involves:
- Preparation of a Formal Objection: Clearly outline the grounds for objection, supported by evidence or documentation.
- Submission through Official Channels: Utilize designated online platforms or the relevant ministry’s contact points.
- Awaiting Response: The FTA will provide feedback or a decision regarding the objection.
Understanding this process allows taxpayers to advocate for their rights effectively.
Impact and Consequences of Non-compliance
Failure to comply with the provisions set forth in Decision No. 40 can lead to severe financial repercussions and legal complications. It's essential for taxpayers to recognize the long-term implications of ignoring tax obligations.
Potential Consequences and Long-term Ramifications
Non-compliance can result in:
- Increased Financial Liabilities: Accumulation of penalties can escalate financial burdens.
- Legal Action: Persistent non-compliance may expose taxpayers to further legal actions from authorities.
- Damage to Reputation: Ongoing violations can tarnish a business's reputation in the marketplace.
Engaging proactively with tax regulations can help mitigate these risks and ensure continued operational viability.
Looking Ahead: Future Amendments and Adaptations
As the UAE’s tax landscape evolves, so too does the framework governing penalties. The adaptability of regulations is essential to accommodate changes in global tax standards and local economic conditions.
Understanding Amendments and Future Considerations
Recent amendments, such as those introduced by Decision No. 49 of 2021 and others, indicate a proactive approach towards refining tax compliance structures. Stakeholders should stay informed about future updates to:
- Improved clarity on penalties and compliance obligations.
- Increased digitalization of processes to facilitate better compliance.
- Potential introduction of new tax laws influencing administrative penalties.
Engaging with these changes ensures taxpayers remain compliant and prepared for future developments.
Conclusion: The Path to Compliance and Responsibility
Engagement with Decision No. 40 of 2017 is not merely a bureaucratic obligation; it represents a core element of responsible business practice in the UAE. By understanding the nuances of administrative penalties, taxpayers can navigate the challenges of compliance more effectively.
Ultimately, the proactive adoption of tax responsibilities fosters a compliant culture, essential for both individual business growth and the broader economic landscape of the UAE.
Understanding the Framework of Administrative Penalties in UAE Tax Laws
The administrative penalties established by the Cabinet Resolution No. (40) of 2017 encompass a structured approach to maintaining compliance with the tax laws stipulated by the Federal Tax Authority (FTA). These penalties serve not only as punitive measures but also as deterrents aimed at ensuring that both individuals and businesses adhere strictly to the legal tax obligations. It is crucial for taxpayers to understand the scope of these administrative fines, which can be imposed for various infractions ranging from minor errors in tax returns to significant failures in compliance.
To navigate the complexity of these laws, taxpayers should familiarize themselves with key provisions outlined in the resolution. For instance, penalties can vary depending on the nature of the violation, including errors in tax return submissions, failure to register for VAT, late payments, and non-compliance with documentation requirements. Each type of infraction carries specific penalties, which are clearly defined within the legal framework, thereby providing transparency and a clear understanding of potential repercussions.
Moreover, the resolution highlights the importance of voluntary disclosure. Taxpayers who proactively disclose inaccuracies in their tax filings may benefit from reduced penalties, fostering a culture of compliance. Understanding the interplay between the tax laws and the penalties associated with violations can significantly impact a taxpayer's approach to compliance and can influence business practices across various sectors.
Appeal Process for Administrative Penalties Under UAE Tax Regulations
In the event of a penalty being imposed, taxpayers have the right to contest the decision through a structured appeal process. This mechanism is designed to ensure fairness and provide taxpayers with an opportunity to present their case. Under the guidelines set forth in Cabinet Resolution No. (40) of 2017, the appeal process must be initiated within a specific timeframe following the issuance of a penalty notice.
The initial step in the appeal process involves submitting a formal objection to the Federal Tax Authority. Taxpayers are required to provide detailed justifications as to why they believe the penalty should be reconsidered. This may include evidence of compliance efforts, documentation supporting claims of extenuating circumstances, or instances of miscommunication with tax authorities. It’s essential for taxpayers to maintain thorough records and documentation to bolster their case during the appeal.
Once the objection is submitted, the FTA will review the appeal and issue a decision. If the taxpayer remains dissatisfied with the outcome, further recourse is available through the Tax Disputes Resolution Committee, which offers an independent assessment of the case. This two-tiered approach not only ensures due process but also reinforces the commitment of UAE authorities to uphold fairness in tax administration.
Impact of Administrative Penalties on Business Operations in the UAE
The implementation of administrative penalties significantly influences business operations within the UAE’s economic landscape. For many businesses, particularly small and medium-sized enterprises (SMEs), understanding the implications of these penalties is critical for financial planning and risk management. Non-compliance with tax obligations can lead to substantial financial burdens due to penalties, which can hinder operational capacity and growth potential.
Furthermore, the stigma associated with penalties can affect a company’s reputation in the market. Businesses found in violation of tax laws may struggle to maintain relationships with clients and partners who prioritize compliance and transparency. Therefore, proactive compliance strategies are essential not only for avoiding penalties but also for sustaining operational integrity and fostering trust within the business community.
It is advisable for business owners and financial managers to invest in robust tax compliance training and systems to mitigate risks associated with administrative penalties. Engaging the services of tax professionals who understand the intricacies of UAE tax law can be invaluable. By ensuring that all tax filings and payments are completed accurately and on time, businesses can not only avoid penalties but also enhance their overall operational efficiency.