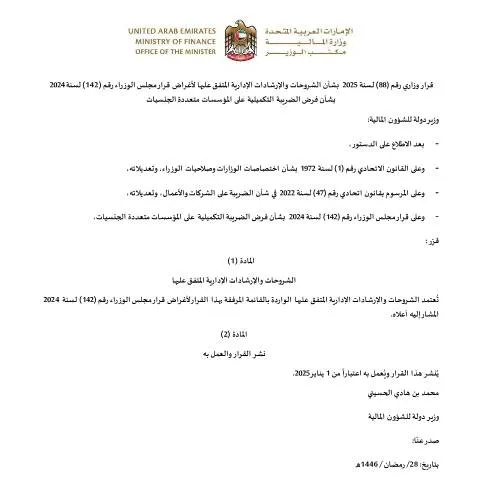
Understanding Ministerial Decision No. 88 of 2025: A Comprehensive Guide
The Ministerial Decision No. 88 of 2025 establishes critical administrative guidance on the supplementary tax levied on multinational enterprises (MNEs) in the UAE, as outlined in the Cabinet Decision No. 142 of 2024. This document serves as a cornerstone in the evolving landscape of UAE tax regulations, reflecting a commitment to comply with international tax standards, particularly those shaped by the OECD.
The Context of the Supplementary Tax
To grasp the significance of the Ministerial Decision No. 88, it's essential to consider the broader context. The supplementary tax was introduced following the UAE's commitment to the OECD's Base Erosion and Profit Shifting (BEPS) framework, aimed at tackling tax avoidance strategies that exploit gaps in tax laws. The UAE, through this decision, reinforces its position as a responsible global player in tax matters.
Key Regulatory Developments
- Federal Law No. 1 of 1972: Foundational legislation outlining the powers of ministries.
- Federal Decree-Law No. 47 of 2022: Establishes the framework for corporate taxation.
- Cabinet Decision No. 142 of 2024: Specifically addresses the implementation of supplementary taxes on MNEs.
This new tax regime is set to come into effect on January 1, 2025, necessitating proactive measures from businesses within the UAE.
The Role of Ministerial Decision No. 88
This document provides essential explanations and guidance to ensure that businesses understand the requirements and implications of the supplementary tax. It outlines the administrative processes to be followed, ensuring compliance and clarity for MNEs operating within the UAE.
Who is Required to Submit This Document?
The responsibility of submitting the relevant forms falls primarily on multinational enterprises with a significant presence in the UAE. These entities must be prepared to furnish comprehensive data regarding their financials and operations to demonstrate compliance with the supplementary tax requirements.
Completing the Documentation: What You Need to Know
Fulfilling the requirements set forth in Ministerial Decision No. 88 involves meticulous preparation. The following steps outline how to effectively complete the necessary forms:
Preparation of Required Documentation
- Gather Financial Statements: Ensure that your financial statements are up-to-date and reflect accurate operational data.
- Compile Data on Global Operations: Document your MNE's global footprint, including all entities and their earnings.
- Understand Tax Jurisdictions: Identify jurisdictions where your MNE operates and the respective tax obligations in those regions.
Each of these elements plays a crucial role in demonstrating compliance and understanding potential liabilities under the supplementary tax framework.
Submission Process: How to File
Once your documentation is complete, the submission process is straightforward but must be approached with diligence:
Filing the Forms Online
The UAE emphasizes digital efficiency in administrative processes. Submissions are conducted through the federal portal u.ae, which integrates with various emirate portals. Follow these steps:
- Access the relevant section of the federal portal.
- Authenticate using your UAE Pass or Emirates ID.
- Upload all required documents through the dedicated submission form.
- Confirm submission and note any reference numbers provided for tracking.
It's essential to keep copies of all submitted documents for your records, as well as any correspondence from the authorities.
Implications of Non-Compliance
Failure to comply with the requirements of Ministerial Decision No. 88 can lead to serious consequences for multinational enterprises. Ignoring the submission of necessary documentation may result in:
- Fines and Penalties: Non-compliance can lead to significant financial penalties imposed by the Federal Tax Authority (FTA).
- Increased Scrutiny: Your enterprise may face heightened scrutiny from tax authorities, leading to more audits and compliance checks.
- Reputation Damage: Failing to adhere to tax obligations may tarnish your enterprise’s reputation in the market.
What to Do If Issues Arise
As with any administrative process, issues may occasionally arise. Here’s how to navigate potential challenges:
Addressing Submission Errors
If you receive feedback indicating an error in your submission, it is crucial to address it promptly:
- Review Feedback: Carefully analyze the reasons provided by the authorities for any rejection or request for additional information.
- Gather Corrective Information: Assemble all necessary data to rectify the issues identified.
- Resubmit Corrected Documents: Ensure that you follow the submission process again, clearly indicating that this is a revised submission.
Handling Refusals
In the unfortunate event that your application is refused, enterprises have the right to appeal:
- Understand the Grounds for Refusal: Ensure you fully comprehend the reasons behind the denial.
- Seek Professional Guidance: Consider consulting with tax advisors familiar with UAE regulations to navigate the appeals process effectively.
- File an Appeal: Depending on the advice received, prepare and submit your appeal through the appropriate channels provided by the FTA.
A Comparative Overview: Understanding Related Forms
Ministerial Decision No. 88 is often confused with other tax-related forms. Below is a comparative overview to clarify distinctions:
| Document | Purpose | Filing Authority | Applicable Entities |
|---|---|---|---|
| Ministerial Decision No. 88 | Guidance on supplementary tax for MNEs | Federal Tax Authority (FTA) | Multinational Enterprises |
| Federal Decree-Law No. 47 of 2022 | Establishes corporate taxation framework | Federal Tax Authority (FTA) | All Businesses |
| Cabinet Decision No. 142 of 2024 | Outlines supplementary tax obligations | Federal Tax Authority (FTA) | Multinational Enterprises |
This comparison highlights the specific focus of Ministerial Decision No. 88 in the overall regulatory framework.
Staying Informed: The Importance of Continuous Compliance
Tax regulations are subject to change and require ongoing attention. Multinational enterprises should stay updated on any amendments to laws and decisions affecting their operations. Following are strategies to maintain compliance:
- Regular Training: Provide continuous training for your finance and compliance teams on the latest tax regulations.
- Establish Compliance Checkpoints: Regularly assess compliance status and address any discrepancies in a timely manner.
- Engagement with Tax Advisors: Maintain a relationship with tax professionals who can provide insights and necessary updates.
Final Thoughts on Ministerial Decision No. 88 of 2025
The implementation of Ministerial Decision No. 88 marks a significant step in the UAE's commitment to tax compliance and international standards. For multinational enterprises, understanding and navigating this process is crucial for ensuring operational integrity and avoiding potential penalties. As the tax landscape evolves, proactive engagement with the regulatory framework will be vital for success.
Understanding the Implications of Ministerial Decision No. (88) of 2025
Ministerial Decision No. (88) of 2025 is a significant regulatory framework that outlines administrative clarifications and guidelines concerning the implementation of the Cabinet Decision No. (142) of 2024, which introduces a supplementary tax for multinational enterprises operating within the UAE. This tax is designed to ensure that these entities contribute fairly to the national economy while maintaining transparency and compliance within the jurisdiction. Understanding the implications of this ministerial decision is crucial for multinational corporations, tax professionals, and compliance officers.
One of the key aspects of this decision is its emphasis on compliance and transparency. Multinational enterprises are required to provide detailed reports regarding their financial activities in the UAE, including revenues, expenses, and profit allocation. This requirement is crucial for the Federal Tax Authority (FTA) as it aims to ensure that companies are not engaging in profit shifting to minimize their tax liabilities. Failure to comply with these reporting standards may result in penalties and increased scrutiny from tax authorities.
Moreover, the ministerial decision specifies the need for consistent documentation and adherence to the principles of transfer pricing. Transfer pricing regulations, which govern the pricing of transactions between related entities within a multinational corporation, must be followed meticulously to avoid potential disputes and ensure that tax liabilities are calculated accurately. Companies are encouraged to seek guidance from tax advisors who are well-versed in local laws and international tax treaties to navigate these complexities effectively.
Key Considerations for Multinational Corporations
For multinational corporations, the introduction of the supplementary tax as outlined in Cabinet Decision No. (142) of 2024 and further clarified by Ministerial Decision No. (88) of 2025 necessitates strategic planning and operational adjustments. Companies must evaluate their current tax structures and compliance processes to align with the new regulatory framework. This includes assessing their business models to determine how the supplementary tax might impact profitability and cash flow.
Another critical consideration is the potential for double taxation. Multinational companies operating in multiple jurisdictions may face the risk of being taxed on the same income in different countries. To mitigate this risk, businesses are advised to explore the applicability of double taxation treaties (DTTs) the UAE has with various countries. These treaties can provide relief by allowing companies to credit taxes paid in one jurisdiction against their tax obligations in another.
Furthermore, organizations should invest in robust tax technology solutions that facilitate accurate compliance with the requirements stipulated in the ministerial decision. By automating tax reporting and documentation processes, companies can reduce the risk of errors and streamline their compliance efforts. Training internal teams on the latest tax regulations and compliance practices is also essential in fostering a culture of accountability and compliance within the organization.
Engagement with the Federal Tax Authority and Future Outlook
Engaging proactively with the Federal Tax Authority (FTA) is another vital step for multinational enterprises adapting to the new tax landscape. The FTA encourages open communication and collaboration, promoting a transparent relationship between tax authorities and businesses. By establishing a dialogue with the FTA, companies can seek clarity on specific provisions of the ministerial decision, address any concerns regarding compliance, and stay informed about any changes in tax legislation.
Looking ahead, businesses must remain vigilant and adaptable as the regulatory environment continues to evolve. The UAE is committed to enhancing its tax framework to align with international best practices while fostering a conducive business climate. This means that further amendments and updates to tax legislation can be expected in the future, which may require ongoing adjustments in compliance strategies for multinational corporations.
In conclusion, navigating the implications of Ministerial Decision No. (88) of 2025 requires a proactive approach, comprehensive understanding of regulatory requirements, and strategic planning. Multinational companies must prioritize compliance while leveraging technology and engaging with tax authorities to mitigate risks associated with the supplementary tax on multinational enterprises.