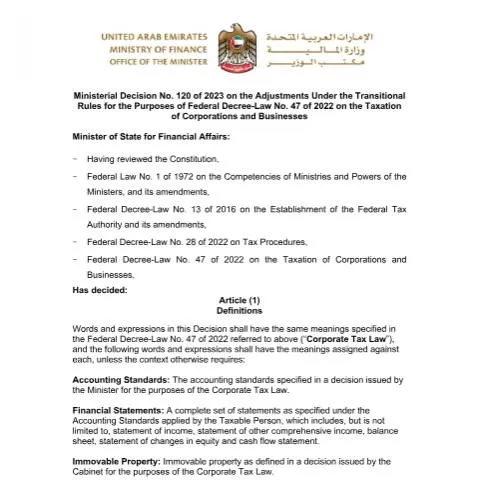
Overview of Ministerial Decision No (120) of 2023 on Tax Transition Regulations in the UAE
The United Arab Emirates (UAE) has issued Ministerial Decision No (120) of 2023 to clarify the transitional provisions related to the implementation of Federal Decree-Law No (47) of 2022 concerning the taxation of corporations and businesses. This decision aims to facilitate a smooth transition for entities subject to the new tax framework, ensuring compliance while maintaining the UAE’s commitment to a highly digitalized and efficient administrative environment.
Scope and Objectives of the Decision
This ministerial decision primarily targets businesses and corporate entities operating within the UAE that are affected by the recent amendments introduced by the federal tax law. Its main objective is to outline the transitional rules that will govern the period following the enactment of the new tax law, thereby providing clarity on compliance obligations and procedural adjustments during this phase.
It is important to note that the decision aligns with the broader legal framework established by the UAE's constitutional principles, which emphasize federal oversight complemented by emirate-level autonomy, especially in administrative and legal matters related to taxation.
Main Provisions and Transitional Measures
Implementation Timeline and Compliance Deadlines
The decision delineates specific timelines for entities to adapt to the new tax regime. It emphasizes that entities should align their reporting and registration processes with the directives issued by the Federal Tax Authority (FTA). The transitional rules provide a grace period during which businesses can adjust their accounting and tax procedures to meet the requirements of the new law.
Tax Registration and Filing Procedures
During the transitional period, businesses are encouraged to utilize the digital platforms provided by the FTA for tax registration, filing, and related communications. The decision clarifies that entities must adhere to the deadlines set by the FTA for submitting their tax declarations, while also benefiting from simplified procedures designed to ease the transition.
Handling of Pre-Existing Tax Liabilities
The decision also addresses how pre-existing tax liabilities, accrued prior to the enactment of the new law, should be managed. It stipulates that transitional rules may include provisions for the gradual settlement of these liabilities, subject to specific conditions and in accordance with FTA guidelines.
Implications for Businesses and Taxpayers
For companies operating in the UAE, this decision underscores the importance of leveraging digital tools available through the UAE Pass and Emirates ID systems for efficient compliance. It also highlights the need to stay informed about the evolving regulatory landscape, particularly as the FTA continues to develop detailed procedures and guidelines.
Entities should review their internal tax and accounting procedures to ensure alignment with the transitional provisions. Consulting with authorized tax advisors or legal experts familiar with federal and emirate-level tax regulations can facilitate compliance and optimize their adaptation to the new legal framework.
Conclusion
Ministerial Decision No (120) of 2023 plays a crucial role in guiding the UAE’s corporate sector through the initial phase of implementing the new tax law. By establishing clear transitional rules, the decision aims to promote compliance, reduce administrative burdens, and support the country’s strategic goal of maintaining a transparent and digitally advanced tax environment. Businesses are advised to closely monitor official updates from the Federal Tax Authority and relevant authorities to ensure adherence to all transitional requirements during this period.