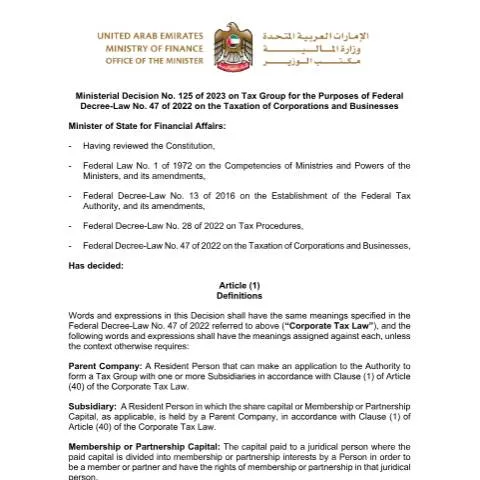
Overview of Ministerial Decision No (125) of 2023 on Tax Group Formation in the UAE
The United Arab Emirates (UAE) has continually refined its tax legislation framework to promote compliance and streamline corporate taxation processes. One of the recent significant updates is the issuance of Ministerial Decision No (125) of 2023, which addresses the establishment and regulation of tax groups in accordance with the provisions of Federal Decree-Law No (47) of 2022 concerning the taxation of corporations and businesses. This decision clarifies the criteria, procedures, and implications of forming a tax group, providing essential guidance for taxpayers and tax authorities alike.
Scope and Purpose of the Decision
The primary aim of Ministerial Decision No (125) of 2023 is to facilitate the formation of tax groups among related entities operating within the UAE. It aims to enhance tax administration efficiency by allowing eligible corporate groups to be treated as a single taxable entity for corporate tax purposes. This approach aligns with the UAE's broader strategy to foster a competitive business environment while ensuring compliance with the federal tax regulations.
The decision delineates the legal and procedural framework for establishing a tax group, including the conditions for eligibility, the rights and obligations of group members, and the reporting requirements. It also emphasizes the importance of transparency and accuracy in the declaration of group structures to prevent tax evasion and ensure fair taxation.
Key Provisions and Eligibility Criteria
Under the decision, a tax group is composed of entities that meet specific criteria set forth by the Federal Tax Authority (FTA). These criteria typically include:
- Common Control: The entities must be under common control, which generally involves ownership thresholds and control rights.
- Legal and Economic Linkages: The entities should have strong operational or financial linkages, demonstrating their integration as a single economic unit.
- Registration and Compliance: All entities must be duly registered with the FTA and comply with their tax obligations.
The decision also specifies that entities seeking to form a tax group must submit an application through the designated digital platforms provided by the FTA, including the UAE Federal Tax Portal and relevant emirate-level tax portals. The application process involves submitting detailed documentation to substantiate the control and linkage criteria.
Implications for Taxpayers and Businesses
Forming a tax group under this decision offers several advantages, including simplified tax compliance, consolidated reporting, and potential tax benefits. However, it also entails specific responsibilities:
- Unified Tax Filing: The group must submit a consolidated tax return, reflecting the combined financial position of all member entities.
- Liability and Compliance: Members are jointly responsible for the accuracy of the tax declarations and adherence to tax regulations.
- Audit and Monitoring: The FTA retains the authority to audit the entire tax group, ensuring compliance and verifying the legitimacy of the group structure.
It is crucial for businesses considering forming a tax group to conduct thorough internal assessments and consult with tax professionals to ensure adherence to all legal requirements and optimize the benefits of grouping.
References and Regulatory Framework
This decision is part of the UAE's broader legal and regulatory effort to modernize tax administration and align with international standards. It complements other provisions within the federal tax legislation and is implemented under the oversight of the Federal Tax Authority (FTA), which is responsible for the regulation, collection, and enforcement of federal taxes.
For detailed guidance, application procedures, and updates, taxpayers are encouraged to consult the official publications and digital platforms provided by the FTA, including the UAE Federal Tax Portal and the relevant emirate-level tax authorities.
Conclusion
Ministerial Decision No (125) of 2023 marks a significant development in the UAE’s tax landscape, providing a clear framework for the formation of tax groups. It aims to facilitate compliance, promote transparency, and support the government's strategic objectives for a competitive and compliant business environment. Businesses interested in establishing a tax group should ensure they understand the legal criteria and leverage digital channels for application and compliance, in line with the UAE’s commitment to digital government services and efficient tax administration.