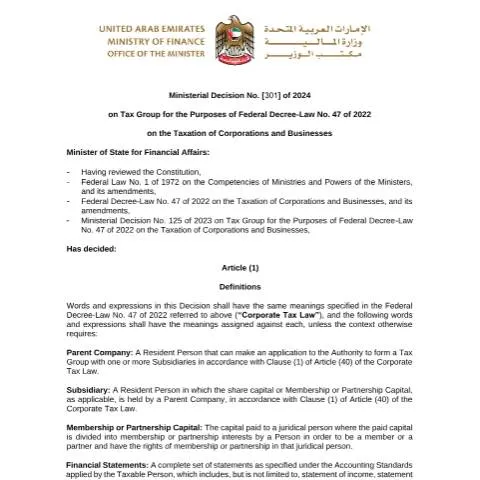
Overview of Ministerial Decision No (301) of 2024 on Tax Grouping in the UAE
The United Arab Emirates has introduced a significant update to its corporate taxation framework through Ministerial Decision No (301) of 2024. This decision clarifies the regulations surrounding the formation and management of tax groups under the provisions of Federal Decree-Law No (47) of 2022 concerning the taxation of corporations and businesses. Its primary aim is to streamline tax compliance and facilitate a cohesive approach to corporate taxation for eligible entities operating within the UAE.
Scope and Purpose of the Decision
The decision provides detailed guidelines on the establishment and operation of tax groups, a mechanism designed to allow related entities to be treated as a single taxable unit for corporate tax purposes. This approach aims to simplify tax reporting, reduce administrative burdens, and promote fiscal transparency among interconnected businesses. The regulation applies to all entities involved in consolidated operations, provided they meet specific criteria outlined within the decision.
Criteria for Formation of a Tax Group
Under the provisions of Ministerial Decision No (301) of 2024, entities seeking to form a tax group must satisfy certain conditions:
- The entities must be legally registered and operating within the UAE.
- They must be related through ownership, with a specified percentage of shareholding or control, as defined by the decision.
- The entities should demonstrate operational interdependence, such as shared management or integrated business functions.
- All members of the tax group must agree to the terms and adhere to the reporting obligations stipulated by the Federal Tax Authority (FTA).
Operational Guidelines and Responsibilities
The decision emphasizes the importance of maintaining accurate and comprehensive records to support the tax group structure. Each member must submit an application through the designated digital channels managed by the Federal Tax Authority (FTA), providing necessary documentation to verify their eligibility.
Once established, the tax group is responsible for filing consolidated tax returns, which reflect the combined financial activities of all members. The decision also delineates procedures for handling transactions between group members, ensuring proper transfer pricing documentation and compliance with UAE tax laws.
Implications for Tax Compliance and Reporting
Entities forming a tax group benefit from simplified tax obligations, as they are taxed collectively rather than individually. However, this requires diligent coordination among group members and strict adherence to the reporting deadlines and documentation standards set forth by the FTA.
Furthermore, the decision clarifies the process for dissolving a tax group or modifying its composition, ensuring flexibility while maintaining compliance. The FTA provides guidance on the necessary procedures to notify authorities and update records accordingly.
References and Regulatory Framework
This decision complements other regulations under the UAE tax legislation, particularly Federal Decree-Law No (47) of 2022, which established the legal foundation for corporate taxation in the country. The Federal Tax Authority (FTA) is the primary regulatory body overseeing the implementation and enforcement of these provisions, providing ongoing guidance and support to taxpayers.
Entities seeking further information or assistance should consult the official communications from the FTA and utilize the digital platforms available on the UAE government portal and respective emirate portals, which facilitate applications and compliance management related to tax grouping.
Conclusion
Ministerial Decision No (301) of 2024 marks a pivotal step in enhancing the UAE’s corporate tax regime by formalizing the framework for tax groups. It aims to promote a transparent, efficient, and compliant tax environment for businesses operating in the UAE, aligning with the country’s broader digital transformation initiatives and commitment to ease of doing business.