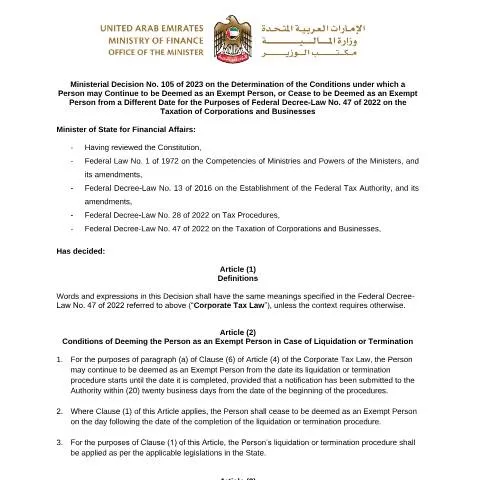
Understanding Ministerial Decision No (105) of 2023 on Tax Exemption Status in the UAE
The United Arab Emirates continues to refine its tax legislation framework to ensure clarity and fairness in the taxation of corporations and businesses. A significant development in this regard is the issuance of Ministerial Decision No (105) of 2023, which outlines the specific conditions under which a person may be classified as an exempt person or cease to be deemed as such for the purposes of Federal Decree-Law No (47) of 2022 on the taxation of corporations and businesses.
Scope and Objectives of the Decision
This ministerial decision aims to provide clear criteria for determining the status of entities or individuals as exempt persons under the UAE's federal tax law. It addresses situations where an entity's exemption status might change over time, ensuring that the tax authorities can apply consistent and transparent standards. The decision is particularly relevant for taxpayers, tax advisors, and legal entities involved in corporate taxation, offering guidance on the procedural and substantive conditions for maintaining or losing exemption status.
Key Provisions and Conditions
Criteria for Continuing as an Exempt Person
- The entity must meet specific operational and legal requirements stipulated by the tax authority, including compliance with registration, reporting, and other regulatory obligations.
- There must be ongoing adherence to the conditions that initially qualified the entity for exemption, such as the nature of business activities or the location of operations.
- Periodic review and confirmation of exemption status may be required, depending on the circumstances outlined by the tax authority.
Conditions Leading to the Cessation of Exempt Status
- Changes in the entity's operational structure, such as diversification of activities outside the scope of exemption criteria.
- Failure to comply with tax reporting or regulatory obligations, which may trigger a review of exemption status.
- Alterations in ownership or control that impact the entity's qualification as an exempt person.
Implications for Taxpayers and Stakeholders
The decision emphasizes the importance of ongoing compliance and accurate reporting to maintain exemption status. Entities that are classified as exempt persons benefit from certain tax advantages; however, they must remain vigilant to ensure they continue to meet the specified conditions. The decision clarifies the process and conditions under which the tax authorities may reassess or revoke exemption status, thereby reducing uncertainty and promoting compliance.
Procedural Aspects and Implementation
Taxpayers seeking to understand their status or facing potential changes should consult the relevant tax authority guidelines and utilize the available digital platforms for status verification and updates. The UAE's focus on digitalization means that most procedures related to exemption status, including notifications and compliance checks, are managed through online portals such as the Federal Tax Authority (FTA) portal.
Conclusion
Ministerial Decision No (105) of 2023 represents a significant step toward transparent and consistent application of tax exemption criteria within the UAE. It underscores the government’s commitment to a fair tax system that balances incentives for compliant entities with the need for effective oversight. Stakeholders are encouraged to stay informed about these regulations and ensure continuous compliance to benefit from the provisions available under federal tax law.