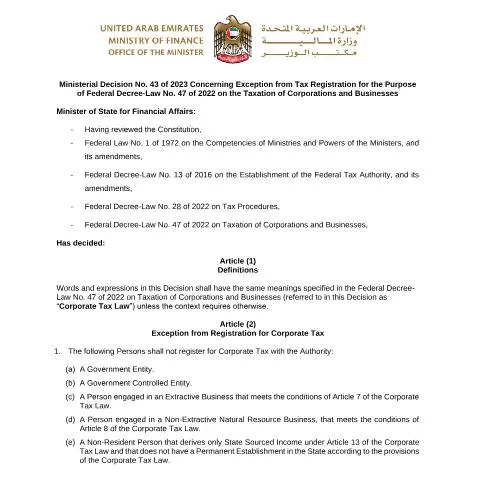
Understanding the Ministerial Decision No (43) of 2023 on Tax Registration Exemptions in the UAE
The United Arab Emirates (UAE) continues to refine its tax framework to promote a conducive business environment while ensuring compliance with its legal obligations. The recent issuance of Ministerial Decision No (43) of 2023 by the Ministry of Finance (MOF) introduces specific provisions concerning exemptions from mandatory tax registration. This guide aims to clarify the scope, implications, and procedural aspects of this decision, providing essential insights for businesses and stakeholders operating within the UAE’s evolving tax landscape.
Scope and Objective of the Decision
The primary purpose of Ministerial Decision No (43) of 2023 is to establish clear criteria and procedures for granting exemptions from the obligation of tax registration under the Federal Decree-Law No (47) of 2022 on the taxation of corporations and businesses. This legislation forms part of the UAE’s broader strategy to streamline tax compliance and facilitate economic activities by delineating circumstances under which certain entities may be exempted from registering for tax purposes.
This decision underscores the UAE’s commitment to creating a balanced tax system that accommodates specific business scenarios, especially those that do not generate taxable supplies or meet certain thresholds outlined in the law. It also aims to reduce administrative burdens for eligible entities, aligning with the UAE’s digitalization initiatives and the government’s focus on efficient service delivery through online platforms.
Key Provisions and Exemption Criteria
The decision details the conditions under which businesses and entities may be exempt from tax registration, which typically include:
- Entities whose turnover or taxable supplies fall below the threshold stipulated in the federal tax law.
- Organizations engaged in activities explicitly excluded from the scope of VAT or corporate taxation as defined by the relevant legislation.
- Entities that operate solely outside the UAE or do not have a physical presence or economic activity within the country.
- Specific categories of non-profit organizations or government entities that are exempted based on their legal status and activities.
It is important to note that the decision emphasizes that exemptions are granted based on a formal application process through the relevant authorities, primarily the Federal Tax Authority (FTA). The authorities assess each case individually, ensuring that the exemption aligns with the legal criteria and the entity’s operational profile.
Procedural Aspects and Implementation
Entities seeking exemption from tax registration must submit a formal request via the FTA’s digital portal, utilizing the specified online service. The application process involves providing detailed information about the entity’s activities, turnover, and legal status, along with supporting documentation as required.
Once an exemption is granted, the entity will receive official confirmation, which must be retained for compliance and audit purposes. The exemption status is subject to periodic review, and entities are obliged to notify the FTA of any material changes that could affect their exemption status.
The decision also clarifies that entities already registered for tax are not automatically exempted; they must submit a separate application if they believe they meet the criteria for exemption. Non-compliance or false declarations may lead to penalties, emphasizing the importance of accurate and transparent submissions.
Implications for Businesses and Stakeholders
This legislative development provides tangible benefits for certain businesses by reducing unnecessary administrative procedures and costs associated with tax registration. It also aligns with the UAE’s strategic goal of fostering a business-friendly environment that encourages economic diversification and foreign investment.
For stakeholders, understanding the exemption criteria and application process is crucial to ensure compliance and optimize their tax obligations. It is recommended that entities regularly review their status and consult with tax professionals or legal advisors to navigate the exemption process effectively.
Conclusion
Ministerial Decision No (43) of 2023 marks a significant step in the UAE’s ongoing efforts to refine its tax regime, offering clarity and flexibility for qualifying entities. By establishing a clear framework for tax registration exemptions, the UAE aims to balance compliance requirements with operational efficiency, supporting its broader economic objectives. Entities are encouraged to stay informed about these provisions and leverage the digital channels provided by the Federal Tax Authority to facilitate their compliance processes.