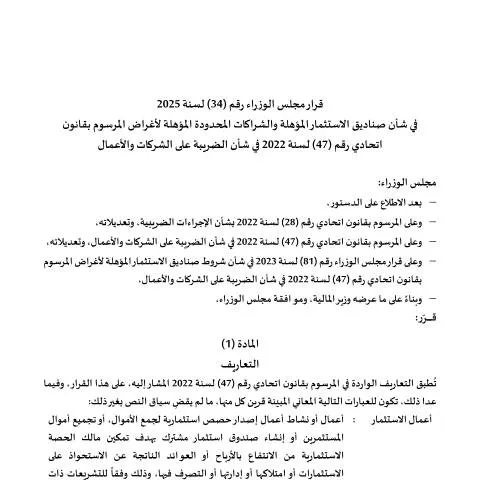
Overview of the Ministerial Decision on Qualified Investment Funds and Limited Partnerships in the UAE
The United Arab Emirates has issued a new ministerial decision aimed at clarifying the regulatory framework surrounding certain investment entities, specifically Qualified Investment Funds (QIFs) and Qualified Limited Partnerships (QLPs). This decision, issued by the Council of Ministers, is part of the broader legal and tax reforms introduced under Federal Law No. (47) of 2022 concerning corporate and business taxation.
As the UAE continues to position itself as a global financial hub, the regulation of investment vehicles such as QIFs and QLPs becomes crucial for attracting foreign investment while ensuring compliance with the country's fiscal policies. This decision offers detailed guidance on the classification, registration, and operational prerequisites for these entities, aligning them with the UAE's strategic economic objectives and tax legislation.
Scope and Objectives of the Decision
This ministerial decision delineates the criteria that qualify certain investment funds and partnerships for preferential tax treatment under the UAE's corporate tax regime. It aims to define the conditions under which these entities can benefit from the incentives provided by the federal tax law, thereby encouraging investment diversification and economic growth.
Key aspects include the eligibility requirements for funds and partnerships to be recognized as qualified entities, the procedural steps for registration and compliance, and the obligations imposed on these entities to maintain their qualified status.
Who Is Affected by This Regulation?
The regulation primarily targets entities involved in investment activities that seek to benefit from the tax incentives under the federal corporate tax law. This includes:
- Funds that pool capital from multiple investors to invest in various assets, provided they meet the criteria outlined in the decision.
- Limited partnerships structured to facilitate investment in specific sectors or projects, which qualify under the new legal framework.
Legal and financial advisors, fund managers, and investors operating within or intending to establish such entities should review the provisions of this decision to ensure compliance and optimize their tax position.
Key Provisions and Requirements
Eligibility Criteria
The decision specifies the conditions that funds and partnerships must meet to be considered qualified. These typically include organizational structure, capital requirements, and operational scope, all aligned with the objectives of the federal tax law.
Registration and Compliance
Qualified entities are required to register with the relevant authorities, such as the Federal Tax Authority (FTA), and adhere to ongoing compliance obligations. This includes maintaining proper records, submitting periodic reports, and ensuring transparency in operations.
Operational Constraints
The decision outlines restrictions on the activities of qualified funds and partnerships to prevent abuse of the tax incentives. Entities must operate within their declared scope and adhere to established governance standards.
Implications for Investors and Fund Managers
For investors, this regulation provides clarity on the tax treatment of returns generated through qualified investment vehicles, potentially enhancing the attractiveness of investing in the UAE. Fund managers must ensure their entities meet all criteria and maintain compliance to retain their qualified status and associated tax benefits.
Adherence to these provisions is essential for legal certainty and to avoid penalties or disqualification from the benefits conferred by the law.
References and Regulatory Authorities
This decision is issued by the Council of Ministers and falls under the jurisdiction of the Ministry of Finance (MOF) and the Federal Tax Authority (FTA). These bodies are responsible for overseeing the implementation, registration procedures, and compliance monitoring related to qualified funds and partnerships.
Entities and stakeholders are encouraged to consult the official publications and guidance issued by these authorities to ensure full adherence to the legal framework and to stay updated on any procedural changes.
For comprehensive understanding and ongoing compliance, legal and fiscal professionals should regularly review updates from the relevant UAE government agencies, particularly the Ministry of Finance and the Federal Tax Authority.