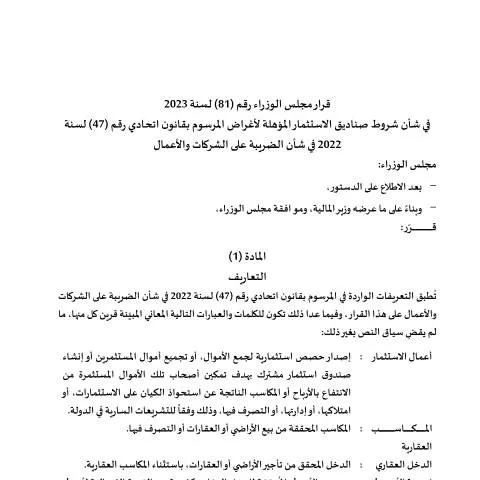
Overview of Cabinet Decision No. (81) of 2023 on Qualified Investment Funds for Corporate Taxation
The United Arab Emirates (UAE) continuously advances its legislative framework to promote a conducive environment for investment and economic growth. A recent significant development in this regard is the issuance of Cabinet Decision No. (81) of 2023, which delineates the criteria for investment funds to qualify for specific tax benefits under Federal Law No. (47) of 2022 concerning corporate and business taxation.
Context and Purpose of the Decision
This decision aims to establish clear eligibility conditions for investment funds seeking to benefit from the tax provisions introduced by the Federal Law No. (47) of 2022. It reflects the UAE's strategic goal of attracting qualified investment funds that meet specific standards, thereby supporting the diversification of the economy and enhancing the UAE's position as a global financial hub.
By setting standardized criteria, the decision ensures transparency and consistency in the qualification process, aligning with the UAE’s broader objectives of promoting compliant and sustainable investment practices within its jurisdiction.
Scope and Eligible Investment Funds
The decision applies to investment funds operating within the UAE that aim to benefit from the tax incentives provided under the federal legislation. It particularly targets funds that are structured to meet the legal and regulatory requirements specified in the decision, including those registered with the relevant authorities and compliant with the stipulated operational standards.
Eligible funds are generally those that demonstrate adherence to the criteria related to their legal structure, operational activities, and compliance with the regulatory framework overseen by the relevant authorities, such as the UAE Securities and Commodities Authority (SCA) and other relevant entities.
Key Conditions for Qualification
The decision specifies several essential conditions that investment funds must satisfy to qualify for the tax benefits. These include, but are not limited to:
- Legal Registration: The fund must be duly registered and licensed in accordance with applicable laws and regulations within the UAE.
- Operational Scope: The fund’s activities should align with the objectives outlined in the federal legislation, primarily focusing on investment activities that contribute to economic development.
- Ownership and Management: The fund must demonstrate transparency in ownership and management structures, ensuring compliance with anti-money laundering (AML) and counter-terrorism financing (CTF) standards.
- Reporting and Compliance: The fund is required to maintain accurate records and submit periodic reports to the relevant authorities, confirming ongoing compliance with the qualification criteria.
Implications for Investment Funds and Stakeholders
Investment funds that meet the criteria outlined in this decision can benefit from the tax incentives introduced under the federal law, which may include reduced corporate tax rates or exemptions, depending on the specific provisions applicable. This creates a strategic advantage for funds seeking to operate efficiently within the UAE's legal environment.
Stakeholders, including fund managers, investors, and legal advisors, should ensure thorough understanding and adherence to the conditions set by this decision. Doing so is essential for securing qualification status and maximizing the benefits available under the UAE’s evolving tax regime.
References and Regulatory Oversight
The implementation and oversight of this decision are managed by the relevant federal authorities, notably the Ministry of Finance (MOF), which is responsible for tax legislation and compliance. Additionally, the Securities and Commodities Authority (SCA) and other regulatory bodies play vital roles in licensing and supervising investment funds to ensure adherence to the stipulated conditions.
Investment funds seeking qualification should consult the official publications and guidelines issued by these authorities to ensure full compliance with the legal and regulatory requirements.
Conclusion
Cabinet Decision No. (81) of 2023 marks a significant step in refining the UAE’s investment and tax framework. By clearly defining the conditions for investment funds to qualify for tax benefits, the UAE reinforces its commitment to fostering a transparent, compliant, and attractive environment for global investors. Stakeholders are encouraged to stay informed of updates from the relevant authorities to ensure ongoing compliance and to leverage the benefits of the legislative amendments effectively.