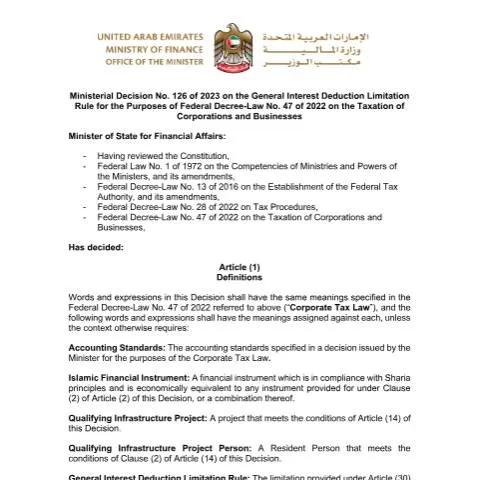
Overview of Ministerial Decision No (126) of 2023 on the General Interest Deduction Limitation Rule
In line with the ongoing efforts to enhance the transparency and fairness of the corporate taxation framework within the United Arab Emirates, Ministerial Decision No (126) of 2023 introduces specific guidelines concerning the limitation of deductions related to general interest expenses. This decision aligns with the provisions set forth in Federal Decree-Law No (47) of 2022 on the taxation of corporations and businesses, aiming to establish clear boundaries on deductible interest to prevent tax base erosion and promote fiscal discipline.
Scope and Application of the Decision
This ministerial decision applies to all taxable persons operating within the UAE who are subject to the corporate tax regime. It particularly targets entities that incur interest expenses as part of their financial operations, including but not limited to companies engaged in trading, manufacturing, financial services, and other commercial activities. The regulation seeks to standardize the treatment of interest deductions to ensure consistency and compliance across different sectors and jurisdictions within the UAE.
Main Provisions and Regulatory Framework
Limitation of Deductible Interest
The decision establishes a cap on the amount of interest expense that can be deducted for tax purposes. This cap is determined based on a specified percentage of the taxable entity’s earnings before interest, taxes, depreciation, and amortization (EBITDA). The purpose is to restrict excessive interest deductions that could otherwise diminish the taxable income of a company beyond reasonable limits.
Calculation Methodology
Taxable persons are required to calculate their interest deduction limit by applying the prescribed percentage to their EBITDA, as reported according to the UAE tax legislation. Any interest expenses exceeding this limit are non-deductible and must be carried forward or treated in accordance with specific provisions outlined in the regulation.
Exceptions and Special Cases
The regulation provides certain exemptions, including interest on debt used for qualifying activities or investments that meet specific criteria established by the Federal Tax Authority (FTA). Entities engaged in international transactions or those with related-party interests should review the detailed guidelines to determine applicability and compliance obligations.
Implications for Taxpayers and Compliance
Taxable persons must review their interest expense records and financial statements to ensure adherence to the new limitation rules. It is essential to maintain detailed documentation supporting interest calculations, including EBITDA figures and the nature of interest expenses incurred. The FTA emphasizes the importance of digital record-keeping and timely reporting through the designated online portals.
Impact on Corporate Tax Planning
The introduction of the interest deduction limitation necessitates a reassessment of corporate financing strategies. Companies may need to optimize their debt structures and consider alternative financing arrangements to maximize deductible expenses within the new regulatory framework. Engaging with tax advisors and legal experts is recommended to navigate these changes effectively.
Conclusion
Ministerial Decision No (126) of 2023 marks a significant step in the UAE’s tax policy, promoting responsible fiscal practices and aligning with international standards on transfer pricing and interest deductibility. Taxpayers are encouraged to stay informed about the detailed provisions issued by the Federal Tax Authority and ensure full compliance to avoid penalties and optimize their tax positions under the new rules.