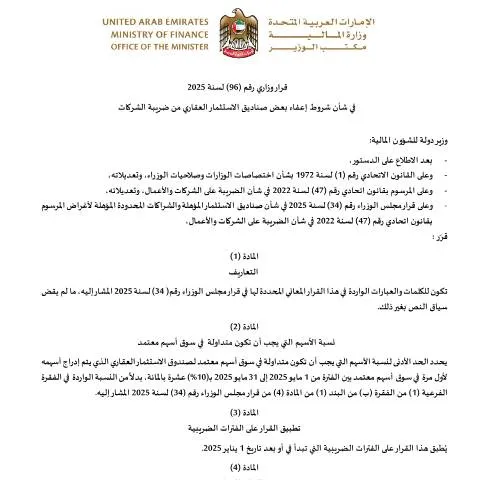
The Official Ministerial Decision: Understanding Resolution No. (96) of 2025 on Exemption Criteria for Certain Real Estate Investment Funds
In a significant move to enhance the investment climate within the United Arab Emirates, the Minister of State for Financial Affairs issued Resolution No. (96) of 2025 on April 14, 2025. This resolution outlines the exemption criteria for specific real estate investment funds from corporate tax obligations. As the UAE continues to position itself as a global hub for real estate investment, understanding this resolution becomes imperative for investors and fund administrators alike.
Who Should Pay Attention to This Ministerial Resolution?
This resolution primarily targets real estate investment funds operating within the UAE seeking favorable tax treatment. To be specific, stakeholders include:
- Investment Fund Managers: Those managing real estate portfolios that may qualify for exemption.
- Investors: Individuals and corporations investing in these funds, who would benefit from reduced tax liabilities.
- Legal and Financial Advisors: Professionals providing guidance on compliance with this new regulation.
- Regulatory Bodies: Entities overseeing the adherence to the resolution and its implications on the market.
Exceptions and Special Cases
While the resolution applies broadly, several exceptions exist. For instance, funds not listed on a recognized stock exchange or those that do not meet specific operational criteria as stipulated in Cabinet Resolution No. (34) of 2025 will not qualify for exemptions. Understanding these nuances is crucial for ensuring compliance and optimizing tax positions.
Effective Dates and Transitional Provisions
The application of this resolution is set to commence for tax periods starting on or after January 1, 2025. This timeline grants funds the necessary preparation period to align their structures with the new criteria. The implications of this effective date are significant:
- Preparation Time: Funds must assess their current compliance and make any necessary adjustments before the impending cut-off.
- Retrospective Applications: Changes can only be applied moving forward, which may leave some funds exposed to previous tax obligations if not compliant.
A Step-by-Step Guide to Navigating the Application Process
Understanding the procedural intricacies of applying for exemption under this resolution is essential for all stakeholders involved. Here’s a structured approach to guide potential applicants:
- Identify Fund Eligibility: Determine whether your real estate fund meets the qualifying criteria laid out in the resolution.
- Gather Required Documentation: Compile all necessary documentation that demonstrates compliance with the criteria, including proof of listing on an accredited exchange, financial statements, and governance frameworks.
- Submit Application: Applications should be submitted digitally through the relevant emirate's portals, ensuring all forms are correctly filled out according to the Emirates ID requirements.
- Await Review: After submission, the application will undergo a review process by the Federal Tax Authority (FTA). Keep an eye on any communication for additional requirements or clarifications.
- Receive Decision: Once evaluated, you will receive an official decision regarding your application, detailing whether the exemption has been granted.
Next Steps in Case of Denial
In the unfortunate event that your application is denied, a clear pathway exists for recourse:
- Review Feedback: Carefully analyze the reasons cited for denial. This feedback is crucial for making necessary adjustments.
- Appeal Process: Applicants can appeal the decision through formal channels outlined by the FTA, typically requiring additional documentation or clarifications.
- Re-application: After addressing the identified issues, a fresh application can be submitted, following the same steps as previously outlined.
Distinct Features of Resolution No. (96) and Its Unique Positioning
It's essential to differentiate this resolution from other similar forms and regulations to avoid confusion. Unlike generic forms that provide blanket exemptions, this resolution specifically targets real estate investment funds with stringent criteria. Key distinctions include:
- Specificity to Real Estate: This resolution exclusively addresses real estate funds, unlike other forms that may apply to broader business categories.
- Tax Period Applicability: The exemptions are tied specifically to post-January 1, 2025 tax periods, making timing a critical factor.
Dissecting the Resolution: Key Sections and Their Implications
Diving deeper into the resolution reveals critical sections that dictate compliance and operational requirements:
| Article | Content Overview | Implications for Funds |
|---|---|---|
| Article 1 | Definitions of terms related to exempt funds | Clear understanding required to ensure compliance with terminology |
| Article 2 | Minimum share trading requirements | Funds must ensure at least 10% of shares are traded on recognized exchanges |
| Article 3 | Application to tax periods | Funds need to ensure structuring aligns with the specified start dates |
| Article 4 | Publication and enforcement of the resolution | Immediate compliance required upon publication |
Each article serves a specific purpose, and understanding them in detail will equip fund managers to navigate their obligations effectively.
Conclusion: Embracing the Benefits of Compliance
As the UAE continues to refine its regulatory landscape, Resolution No. (96) of 2025 serves as a pivotal legislative framework for real estate investment funds. By adhering to its stipulations, stakeholders not only enhance compliance but also position themselves favorably within the burgeoning market. With the right preparation, investment funds can leverage these exemptions to optimize returns while contributing to the growth of the UAE's robust economy.