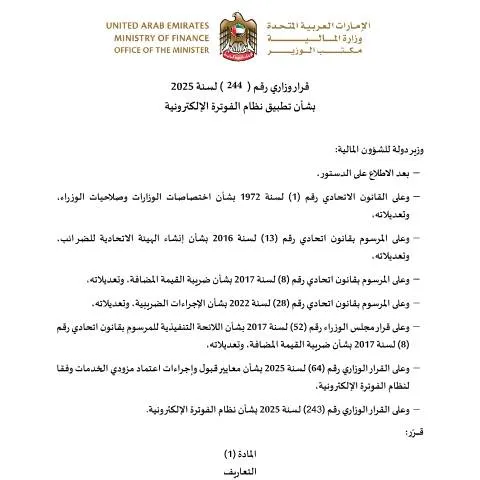
Unveiling the Electronic Invoicing System: A New Regulatory Framework
The Ministerial Decision No. 244 of 2025, relating to the implementation of the electronic invoicing system, marks a significant shift in the UAE's tax legislative landscape. This decision, orchestrated by the التشريعات الضريبية, aims to enhance compliance, streamline tax processes, and reduce administrative burdens for businesses. The decision encapsulates various facets of the electronic invoicing system, detailing the roles, obligations, and compliance requirements for different stakeholders.
Who Must Engage with the Electronic Invoicing System?
The introduction of this system touches a wide spectrum of entities, primarily those subject to tax regulations in the UAE. It is crucial to grasp the profiles of those affected by this mandate:
- Taxable Persons: Any individual or entity whose revenue exceeds AED 50 million falls under the mandatory engagement stipulations.
- Opt-In Entities: Smaller businesses or entities may choose to participate voluntarily in the electronic invoicing system, provided they comply with technical specifications laid out by the authorities.
- Government Entities: All governmental bodies are required to adopt this system within specified timelines, reflecting the government's commitment to modernization and efficiency.
Exceptions and Special Cases
While the framework appears straightforward, there are essential exceptions to consider:
- Transactions with Consumers: Transactions between businesses and consumers are currently exempt from the electronic invoicing system, pending further regulations from the authorities.
- Entities Below Revenue Threshold: Businesses with earnings below AED 50 million are not mandated to comply until the later phases of the rollout.
Chronological Steps: From Notification to Compliance
Understanding the timeline and process of compliance is vital for businesses to avoid penalties:
- Notification: Taxable persons will receive a formal notification from the Ministry once they are included in the electronic invoicing program.
- Consent Requirement: Prior to inclusion, written consent from the entity is required, ensuring stakeholders are aware and agree to the participation.
- Technical Specifications: Participating entities must adhere to all technical requirements outlined by the Ministry and the Federal Tax Authority (FTA).
- Implementation Period: The mandatory rollout phases are defined, with the first group expected to implement by January 1, 2027, followed by others in the subsequent months.
Navigating the Electronic Invoicing Form
The electronic invoicing system necessitates the submission of precise data through a dedicated online platform, demanding meticulous attention to detail:
| Section | Description | Common Pitfalls |
|---|---|---|
| Entity Information | Details of the taxable person or entity, including legal name and registration number. | Incorrect registration number can delay processing. |
| Revenue Declaration | Annual revenue figures that determine eligibility for the system. | Omitting revenue can lead to compliance issues. |
| Service Provider Details | Information about the approved service provider assisting in the invoicing process. | Failure to list an approved provider can result in penalties. |
Essential Documentation: Preparing for Submission
When finalizing the form, businesses must be diligent in collating the necessary documentation:
- Business License: A current copy of the business license is mandatory for verification.
- Financial Statements: Recent financial records may be required to substantiate revenue declarations.
- Proof of Tax Registration: Ensure the submission of the tax registration certificate to authenticate your status.
Unique Considerations for Foreign Entities
Foreign businesses engaging in the UAE market must navigate additional stipulations:
- Local Representation: Establishing a local representative is often necessary to handle compliance matters.
- Consideration of Local Laws: Understanding local tax laws is critical, as they may significantly differ from the business's home country.
Consequences of Non-Compliance
Failure to adhere to the stipulations of the electronic invoicing system can have serious implications:
- Financial Penalties: Non-compliance may result in substantial fines as determined by the FTA.
- Legal Repercussions: Continuous neglect of obligations could lead to legal actions against the business entity.
- Reputation Risks: Non-compliance may tarnish business credibility in both local and international markets.
Looking Ahead: The Future of Electronic Invoicing
The phased implementation of the electronic invoicing system stands to revolutionize financial operations within the UAE. As the FTA and the Ministry refine the system, entities must prepare for ongoing adaptations and ensure they stay informed on updates that may affect their operations.
In summary, engaging with the electronic invoicing system necessitates a proactive approach from businesses to navigate the complexities of compliance effectively. Understanding the role of the Ministerial Decision No. 244 of 2025 is instrumental in ensuring a smooth transition.
Understanding the Electronic Billing System Under Ministerial Decision No. 244 of 2025
The introduction of Ministerial Decision No. 244 of 2025 marks a significant milestone in the UAE's tax landscape, particularly in streamlining the invoicing process for businesses and enhancing tax compliance. This regulation mandates the implementation of an electronic billing system across various sectors, aimed at eliminating inefficiencies and reducing tax evasion. The new electronic invoicing system is designed to support the Federal Tax Authority (FTA) in its mission to ensure transparency and accountability in financial transactions.
With the integration of this electronic system, businesses are expected to adopt digital invoicing tools that automatically generate, dispatch, and archive invoices electronically. This move not only serves to minimize paperwork costs but also enhances the tracking of sales transactions, making it easier for the FTA to monitor compliance and audit trails. Companies must be aware of the technical specifications and standards set forth by the FTA to align their invoicing systems with the new regulatory requirements.
The Role of Digital Transformation in Compliance with Ministerial Decision No. 244
The UAE has been at the forefront of digital transformation, and the introduction of the electronic billing system aligns with the broader vision for a smart economy. Ministerial Decision No. 244 of 2025 requires businesses to utilize electronic invoicing solutions that are compliant with the FTA's guidelines. This not only simplifies the invoicing process but also enhances data accuracy and security through the use of encrypted digital platforms.
Organizations need to ensure that their electronic systems comply with specific technical requirements, including the ability to integrate directly with the FTA's central tax systems. This integration allows for real-time reporting of transactions, which is central to achieving effective tax compliance. Furthermore, businesses must train their staff on the new system, ensuring that they understand how to use the electronic invoicing tools proficiently while maintaining adherence to local tax legislation.
Implications for Different Business Sectors and Readiness Assessment
Ministerial Decision No. 244 of 2025 has implications that vary widely across different sectors, from retail to service industries. Understanding these specific impacts can help businesses prepare adequately for compliance. For instance, the retail sector, often characterized by high transaction volumes, may need to invest in robust electronic systems capable of handling large quantities of invoices efficiently, while service providers could focus on streamlined invoicing processes tailored to project-based billing.
To facilitate a smooth transition, businesses should conduct a readiness assessment that evaluates their current invoicing processes against the new electronic requirements. This assessment should include a review of existing software, employee training needs, and potential upgrades required to meet compliance standards. Engaging with tax advisors and tech solutions providers can also enhance preparedness and mitigate risks associated with non-compliance.