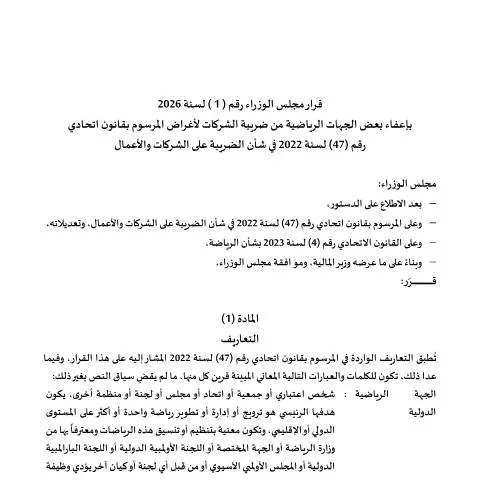
Overview of Cabinet Decision No. 1 of 2026 on Exempting Certain Sports Entities from Corporate Tax in the UAE
The United Arab Emirates continues to refine its fiscal policies to promote the growth of various sectors within its economy. One notable development is the issuance of Cabinet Decision No. 1 of 2026, which introduces specific exemptions from corporate tax for designated sports entities. This decision aligns with the UAE’s broader strategy to foster sports development, attract international sporting organizations, and support local sports initiatives while maintaining a robust fiscal framework.
Scope and Purpose of the Decision
This cabinet decision primarily aims to provide targeted tax relief to certain sports organizations operating within the UAE. The exemption applies to entities involved in organized sporting activities, including clubs, federations, and associations that meet specific criteria outlined by the relevant authorities. The overarching goal is to stimulate investment in sports infrastructure, encourage youth participation, and position the UAE as a global hub for sporting excellence.
Importantly, this exemption pertains specifically to corporate tax, which is a key component of the UAE’s fiscal landscape. By alleviating tax burdens on qualifying sports entities, the government seeks to create a more conducive environment for sports-related economic activities without compromising fiscal discipline.
Who Is Affected by the Decision?
The exemption targets a defined category of sports entities, which typically include:
- Sports clubs and teams registered under the relevant federal or emirate-level sports authorities.
- National sports federations recognized by the UAE Ministry of Culture and Youth.
- Local and international sports organizations operating within the UAE, provided they meet the stipulated criteria.
Entities that are engaged in commercial activities related to sports, such as event management and sports merchandise, may also benefit if they qualify under the specific provisions of the decision. However, the primary focus remains on organizations directly involved in the development and promotion of sports activities.
Key Provisions and Implications
Eligibility Criteria
The decision sets forth certain conditions that sports entities must satisfy to qualify for the tax exemption. These typically include registration with relevant authorities, adherence to regulatory standards, and compliance with reporting obligations. The precise criteria are detailed in the implementing regulations issued by the concerned authorities.
Duration and Scope of the Exemption
The exemption is granted for a specified period, which is designed to encourage long-term planning and investment. Entities benefiting from this exemption are expected to continue fulfilling the eligibility requirements throughout the exemption period to maintain their status.
Tax Compliance and Reporting
While the exemption reduces the tax burden, sports entities are still required to comply with other fiscal and legal obligations, including financial reporting and transparency standards established by the Federal Tax Authority (FTA). Entities must ensure proper documentation and adherence to all applicable tax laws to benefit from the exemption.
Legal and Administrative References
The decision is issued by the UAE Cabinet and forms part of the broader legislative framework governing corporate taxation in the country. For detailed legal interpretation and application procedures, affected entities are advised to consult the relevant authorities, including the Federal Tax Authority (FTA), the Ministry of Culture and Youth, and the General Authority of Sports.
Furthermore, the decision aligns with the UAE’s commitment to fostering a sustainable sports ecosystem and enhancing its international reputation as a destination for world-class sporting events. It exemplifies the government’s strategic approach to balancing fiscal policy with sector-specific incentives.
Conclusion
Cabinet Decision No. 1 of 2026 marks a significant step in the UAE’s ongoing efforts to support the sports sector through targeted fiscal incentives. By providing corporate tax exemptions to eligible sports organizations, the UAE aims to attract more investment, promote local talent, and establish itself as a leading destination for sports development and international competitions. Entities interested in benefiting from this exemption should closely monitor official communications from the relevant authorities and ensure compliance with all legal requirements.