Unlocking the Benefits of IRS Publication 5811
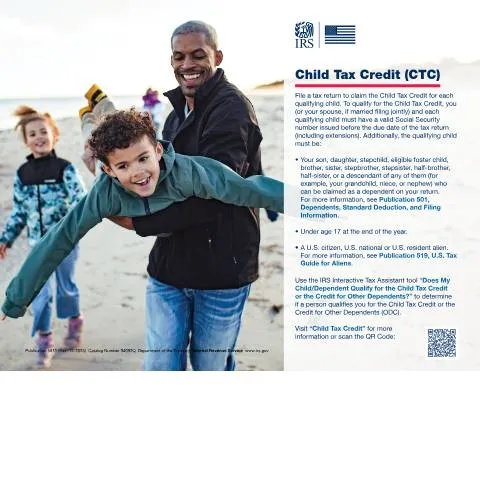
Diving into the intricacies of the IRS can often feel daunting, especially when navigating the various documents required for tax filings. One such pivotal document is IRS Publication 5811, which serves a critical role in assisting taxpayers in claiming the Child Tax Credit (CTC). This publication delineates eligibility criteria, the necessary steps for claiming the credit, and the importance of understanding the nuances that can significantly affect your financial benefits.
Navigating Eligibility: Who Gains from Publication 5811?
Understanding who qualifies for the Child Tax Credit as outlined in Publication 5811 is pivotal. The guidelines are designed to ensure that only those who genuinely meet specific criteria can claim this lucrative credit. Here’s a detailed look at the requirements:
- Taxpayer Eligibility: The individual claiming the CTC must either be the taxpayer or their spouse if filing jointly. Both must have a valid Social Security Number (SSN) issued before the tax return's due date.
- Qualifying Child: The child must be under 17 at the end of the tax year being reported. This child can include sons, daughters, stepchildren, or eligible foster children, among other specified familial relations.
- Residency and Citizenship: Essential to note is that the qualifying child must be a U.S. citizen, U.S. national, or U.S. resident alien.
Publication 5811 emphasizes the importance of these criteria to prevent inadvertent claims that could lead to delays or refunds being denied.
Completing the Application: A Step-by-Step Breakdown
Successfully filing for the Child Tax Credit involves filling out your tax return accurately. Here's how to leverage Publication 5811:
- Identify your filing status: Ensure you choose the correct filing status on your Form 1040, as this can impact your eligibility.
- Gather necessary documentation: Collect all relevant information, including SSNs for both the taxpayer and qualifying children.
- Claiming the credit: On your tax return, locate the section pertaining to credits and input the necessary figures as indicated by the guidelines in Publication 5811.
Be meticulous when entering data; even minor errors can lead to processing delays or incorrect credit calculations.
What Happens if Your Claim is Denied?
An unexpected denial of your Child Tax Credit claim can be frustrating. It’s essential to understand the steps available to you:
- Review the denial notice: This notice will detail the reasons for denial, which is your first clue on how to rectify the situation.
- Gather supporting documents: If the denial is due to missing information, compile evidence that supports your claim, including SSNs and relationship documentation.
- File an appeal: You have the right to appeal the decision. Prepare a thorough response addressing the points raised in the denial.
Additionally, contacting the IRS directly for clarification can often lead to a resolution without formal appeals. Remember, acting swiftly is key.
Understanding the Submission Process: Online vs. Paper
The IRS offers several avenues for submitting your tax return and claiming the Child Tax Credit. Knowing the differences can streamline your experience:
| Method |
Advantages |
Considerations |
| Online Filing |
Faster processing, immediate confirmation of submission. |
Requires internet access and familiarity with filing software. |
| Paper Filing |
Suitable for those less comfortable with technology. |
Slower processing times, risk of mail delays. |
Choose the method that aligns best with your comfort level, remembering that online submissions tend to receive faster responses from the IRS.
Timeline of Events: From Filing to Resolution
The pathway from submitting your tax return to receiving your Child Tax Credit is a journey paved with specific timelines:
- Filing Date: The typical deadline for submitting your tax return is April 15. However, you may file for an extension if needed.
- Processing Time: After submission, the IRS generally takes 21 days to process electronic filings, while paper returns can take longer due to manual handling.
- Credit Disbursement: If your claim is approved, expect your credits to be applied to your tax liability or issued as a refund shortly after processing.
Staying aware of these timelines can assist in planning your financial activities accordingly.
It’s common for taxpayers to confuse Publication 5811 with other IRS documents, particularly those related to child tax benefits. Understanding these distinctions can help clarify your filing process:
- Publication 501: Provides information about dependents, standard deductions, and filing requirements. It is essential for understanding your overall tax situation but does not specifically focus on the CTC.
- Form 1040: The main tax form on which you claim the Child Tax Credit. Publication 5811 supplements the filing of this form with specific guidelines for the credit.
Even though these documents are interconnected, knowing their unique roles can prevent confusion and ensure accurate filings.
The Role of Publication 5811 in the Greater Tax Framework
As part of the IRS's broader tax framework, Publication 5811 not only serves as an instructional guide but also highlights the significance of credits in tax liability reduction. By claiming the Child Tax Credit:
- You effectively lower your taxable income, resulting in a potential refund.
- It encourages families to invest in their children's futures, aligning with federal goals of supporting family structures.
In essence, while Publication 5811 focuses on a specific credit, it is intrinsically tied to the broader objectives of the IRS to support taxpayers in reducing their tax burdens responsibly.
Understanding IRS Publication 5811: A Detailed Overview
IRS Publication 5811 is a vital resource for taxpayers who are navigating the complexities of tax deductions. This publication specifically outlines how taxpayers can claim deductions for business expenses related to goods and services provided by their businesses. Understanding the fine details of this publication is crucial for ensuring compliance and maximizing eligible deductions.
First and foremost, it’s important to note that IRS Publication 5811 categorizes various types of deductible expenses. These can include, but are not limited to, materials and supplies, contract labor, and other necessary expenditures that keep a business operational. The IRS emphasizes that these expenses must be ordinary and necessary for the business to qualify for a deduction, which is a fundamental criterion under the Internal Revenue Code.
In addition to outlining deductible expenses, Publication 5811 provides guidance on how to properly document these expenses. Receipts, invoices, and financial statements are critical for substantiating claims made on tax returns. Failure to maintain proper records can result in disallowed deductions, leading to potential audits by the IRS. Taxpayers are advised to maintain accurate records for at least three years after filing their tax returns, as this is the standard statute of limitations for IRS audits.
Another key component of this publication is the discussion on expense allocation. For businesses that operate in more than one area or have mixed-use assets, the allocation of expenses can become intricate. Publication 5811 provides examples and methods for prorating these expenses correctly. For instance, if a taxpayer runs a business from a home office, they must determine what portion of their home expenses can be attributed to their business operations.
Moreover, special considerations are provided for specific industries or types of businesses. For example, farmers and ranchers may have unique deductible expenses pertaining to livestock, feed, and equipment. Similarly, businesses in the construction industry should familiarize themselves with additional guidelines that specifically address issues such as subcontractor payments and material costs.
Lastly, for taxpayers who may be considering starting a new business, IRS Publication 5811 includes information on startup costs. Understanding how these costs can be deducted in the initial years of operation can greatly impact a startup’s financial situation. The IRS allows new businesses to deduct up to a certain amount of their startup costs in the first year, with remaining costs amortizable over a period of time thereafter.
Key Takeaways for Business Owners: Practical Application of Publication 5811
For business owners, the practical application of IRS Publication 5811 can significantly influence financial performance and tax liabilities. It is essential to approach the guidelines in a proactive manner to capitalize on allowable deductions and optimize financial strategies.
To start, business owners should conduct a thorough review of their past expenses in light of Publication 5811’s guidelines. This means not only organizing current receipts and invoices but also revisiting older records to identify any overlooked deductions. Taxpayers should create a dedicated filing system that categorizes expenses accurately, making it easier to reference them during tax preparation.
Furthermore, it’s advisable for business owners to establish a regular schedule for financial reviews. Monthly or quarterly check-ins can help ensure that all expenses are being tracked and recorded appropriately, and they provide an opportunity to adjust business plans as necessary. This practice can stave off potential issues during tax season and help mitigate stress when it comes time to file.
Additionally, business owners should explore technology solutions that can facilitate expense tracking. There are various accounting software programs that integrate with business operations and automate the expense tracking process. Although choosing the right technology should align with the specific needs of the business, the overall goal should always be to simplify and streamline financial management.
Engaging with a tax professional can also provide invaluable insights into how best to apply the provisions of Publication 5811. Tax advisers are often well-versed in the latest tax laws and can offer tailored advice that aligns with a business’s unique circumstances. Whether it’s navigating complex deductions or preparing for potential audits, the expertise of a qualified tax professional can be a significant asset.
Finally, business owners should keep abreast of any changes to tax laws or IRS guidelines, including updates to IRS Publication 5811. The tax landscape can shift significantly due to new legislation or policy changes, and staying informed will help business owners remain compliant while maximizing their tax benefits. Resources such as the IRS official website or subscription services for tax news can serve as valuable tools for ongoing education.
Future Implications: How IRS Publication 5811 Fits into Broader Tax Trends
As the IRS continues to evolve its guidelines and publications, understanding IRS Publication 5811 within the context of broader tax trends can yield important implications for future compliance and strategy for business owners. With the increasing digitization of financial transactions and the ongoing development of tax policy, the landscape of allowable deductions is likely to change.
One emerging trend is the growing emphasis on transparency and accountability in tax reporting. The IRS has been enhancing its compliance measures, which may lead to more audits and scrutiny of businesses claiming deductions under guidelines such as those in Publication 5811. As a result, businesses should prepare for a culture of thorough documentation and justification of claims, which may require further investments in accounting practices and resources.
Additionally, recent discussions around tax reform at the federal level suggest that certain deductions could be modified or phased out in the future. Business owners must stay informed of any proposals that could impact the deductibility of their expenses. Whether it’s shifts in allowable caps for deductions or changes to the definition of what constitutes a necessary business expense, staying ahead of these trends will be crucial.
The growing gig economy also has implications for how IRS Publication 5811 is applied. More individuals are turning to freelance or contract work, often blurring the lines between personal and business expenses. Understanding how to navigate these nuances and apply the guidelines effectively will be essential for this new class of workers. They must familiarize themselves with the IRS rules to maximize their deductions while ensuring compliance.
Lastly, the integration of technology in financial management introduces both opportunities and challenges. As businesses adopt more advanced technologies for tracking and reporting expenses, they must also develop an understanding of the compliance challenges associated with these systems. This includes ensuring that any software systems used to track expenses are in accordance with IRS standards to avoid potential pitfalls during audits.
Navigating the complexities of IRS Publication 5811 requires a proactive approach, ongoing education, and strategic planning. By understanding not only the document itself but also the broader trends affecting tax policy and compliance, business owners can better position themselves for fiscal success now and in the future.