Navigating the IRS Publication 5534-A: A Comprehensive Guide
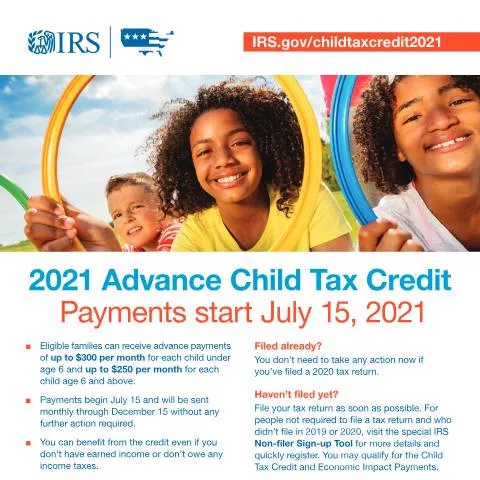
When it comes to claiming tax benefits, especially the Advance Child Tax Credit (CTC), understanding IRS Publication 5534-A is essential for eligible families. This publication serves as a critical resource for taxpayers looking to navigate the complexities of tax credits that have been expanded for the tax year 2021. With payments beginning on July 15, 2021, and continuing through December 15, 2021, knowing how to properly utilize this publication can lead to significant financial benefits.
Understanding Your Eligibility for Advance Payments
Eligibility for advance payments is determined by various factors, including income level, the number of qualifying children, and the age of those children. The publication outlines specific criteria that must be met:
- Income Requirements: Families can qualify for advance payments even if they do not have earned income or owe any taxes.
- Child Age Considerations: The CTC applies to children under age 17 by the end of the tax year; specifically, children must turn age 17 in 2021 to be included.
- Filing Status: The publication guides taxpayers on how their filing status affects eligibility.
Defining Qualifying Children
For the purposes of the Child Tax Credit, a qualifying child must meet specific criteria that include:
- Being a biological or adopted child, stepchild, or eligible foster child.
- Living with the taxpayer for more than half the year.
- Being claimed as a dependent on the taxpayer's federal tax return.
A Step-by-Step Breakdown of Publication 5534-A
Publication 5534-A not only highlights eligibility criteria but also explains how the process works. Here’s how to interpret the information you’ll find:
- Payment Amounts: Families may receive up to $300 per month for each child under 6 and up to $250 per month for children aged 6 and older.
- Automatic Enrollment: For those who have already filed their 2020 tax returns, no additional action is required to receive these payments.
The Importance of Timely Tax Filing
If you haven't yet filed your 2020 tax return, it's crucial to do so as soon as possible. The IRS advises that:
- Individuals not required to file should use the IRS Non-filer Sign-up Tool to register and potentially qualify for the Child Tax Credit.
- Delaying your tax filing could result in missing out on valuable credits, so fulfilling this requirement promptly is imperative.
Document Preparation: What to Have Ready
Preparing to claim the Child Tax Credit involves gathering specific documentation, especially if your situation is complex:
| Situation | Required Documentation |
|---|---|
| Standard Filing | Your 2020 tax return and Social Security numbers for all qualifying children. |
| First-time Filers | A valid ID, proof of income, and Social Security numbers for all dependents. |
| Non-filers (previously not required to file) | Proof of income (if any), Social Security numbers, and completed Non-filer Tool information. |
Filing Channels: Paper vs. Online Submission
Taxpayers have various options for filing their tax returns, each with distinct advantages and differences:
- Online Filing: Utilizing IRS e-file is typically faster and allows for immediate confirmation of submission.
- Paper Filing: While traditional, it can result in longer processing times. Ensure your Form 1040 is accurately filled out.
- In-Person Assistance: The IRS offers in-person help at various locations, but it’s advisable to schedule an appointment ahead of time.
What to Expect After Filing
Once you submit your tax return, the next steps depend on how you filed:
- For Online Filers: Expect a quicker refund process if eligible for a refund or credits.
- For Paper Filers: There may be a delay up to several weeks to receive processing confirmation and any potential refund.
Special Cases: What If Your Situation is Unique?
There are scenarios where taxpayers may find themselves in unique situations, such as being a foreign national or having complex family dynamics. Here’s how to navigate those challenges:
- Foreign Nationals: Specific rules apply, and it’s essential to check if you qualify for tax credits based on residency status.
- Minors as Filers: If a minor is filing, they too can benefit from the Child Tax Credit, but their eligibility will depend on who claims them as a dependent.
- Divorced or Separated Parents: In instances of divorce, custodial parent rules apply, and the non-custodial parent must have a signed form to claim the child.
Critical Reminders: Avoiding Common Pitfalls
When utilizing IRS Publication 5534-A, certain nuances can lead to misunderstandings. Here are key reminders:
- Verify Social Security Numbers: Ensure that all SSNs listed are accurate and correspond to eligible children.
- Be Aware of Changes: Tax laws may shift, so stay updated on any new provisions or modifications regarding child tax credits.
- Keep Records: Maintain copies of your tax filings and any correspondence with the IRS.
What to Do If You Miss Payments
If you fail to receive your advance Child Tax Credit payments, follow these steps:
- Check Payment Status: Use the IRS Child Tax Credit Update Portal to check the status of your payments.
- Submit a Request: If payments are missing, consider contacting the IRS directly to inquire about potential processing issues.
Final Notes on Publication 5534-A
IRS Publication 5534-A serves as a critical tool for families looking to maximize their tax benefits for the year 2021. The intricacies of eligibility, documentation, and the various channels for filing cannot be overlooked. Whether you’re a seasoned taxpayer or navigating the tax system for the first time, understanding the details provided in this publication ensures that you are well-prepared to benefit from the Advance Child Tax Credit.
Understanding the Implications of IRS Publication 5534A
IRS Publication 5534A provides crucial information for taxpayers, particularly those involved in international transactions or who are subject to specific federal tax requirements. This publication ensures transparency and compliance with IRS regulations. Understanding these implications is critical for individuals and businesses alike, especially in regard to reporting requirements, tax liabilities, and potential penalties.
One of the key areas addressed in Publication 5534A is the treatment of foreign income and how it should be reported on your federal tax returns. Taxpayers must be diligent in documenting any foreign assets, bank accounts, and income earned outside the United States to avoid incurring significant penalties. Form 8938, Statement of Specified Foreign Financial Assets, is typically used in conjunction with the guidelines provided in this publication. Failure to report foreign financial assets can lead to penalties exceeding $10,000, depending on the amount owed and the nature of the violation.
Moreover, navigating the regulations related to foreign tax credits and deductions is another essential focus of Publication 5534A. Taxpayers must be fully aware of how foreign taxes paid can impact their U.S. tax obligations. Properly claiming these credits can prevent double taxation but requires meticulous record-keeping and adherence to IRS guidelines. The interplay between U.S. tax law and foreign tax regulations can be complex, and taxpayers are strongly encouraged to consult tax professionals who specialize in international taxation.
Common Mistakes and Misconceptions Regarding IRS Publication 5534A
While IRS Publication 5534A provides essential guidelines, several common mistakes and misconceptions can lead to compliance issues for taxpayers. One of the prevalent misunderstandings is the belief that all foreign income is tax-exempt. In reality, U.S. citizens and residents are required to report their worldwide income, regardless of where it is earned. This misconception can lead to underreporting and, consequently, IRS scrutiny.
Another common error is failing to recognize the importance of the deadlines associated with foreign asset reporting. Taxpayers often misconstrue the filing dates of Form 8938 and FBAR (Foreign Bank Account Report). While the tax return deadline is typically April 15, the FBAR has its own filing timeline that must be adhered to. Taxpayers need to plan accordingly to ensure they meet all filing requirements to avoid penalties.
Additionally, misunderstandings regarding the definitions of foreign financial assets can create confusion. Many taxpayers mistakenly believe that only bank accounts fall into this category, whereas IRS definitions encompass various types of foreign investments, including stocks, securities, and partnership interests. A comprehensive understanding of what constitutes a foreign financial asset is crucial for proper compliance and reporting.
Filing Amendments: Correcting Mistakes Related to Publication 5534A
If you discover that you have made a mistake in your previous filings related to IRS Publication 5534A, it’s essential to understand the process for amending your tax returns. The IRS allows taxpayers to file an amended return using Form 1040-X. This form is utilized to correct errors, including those pertaining to foreign income reporting or asset disclosures.
When filing an amendment, it's crucial to provide a compelling explanation for the changes made. Whether it’s a mistake in reporting foreign income or failing to include certain assets, clarity and documentation are key. Supporting documentation should be attached to demonstrate the changes and justify the corrections. Keep in mind that amending your return may lead to additional taxes owed or a refund, depending on the nature of the correction.
Moreover, you should be aware of the statute of limitations for amending returns. Generally, you have three years from the due date of your original return or two years from the date you paid the tax to file an amendment. If your amendment involves unreported foreign assets, it's advisable to act promptly, as the IRS has strict guidelines on compliance and may impose significant penalties for late reporting.
Finally, if your amendment relates to foreign tax credits or deductions, be prepared to provide proof of taxes paid to foreign governments. Proper documentation is critical in supporting your claims and ensuring a smooth amendment process.