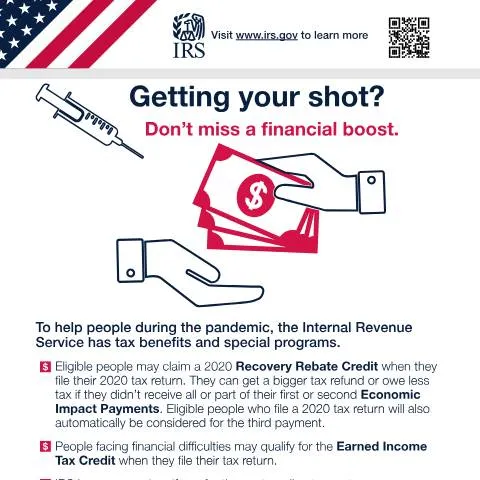
Understanding IRS Publication 5501: A Comprehensive Look
Navigating the IRS's complex forms and publications can often feel overwhelming. IRS Publication 5501 serves as a vital resource for taxpayers, particularly during challenging times like the pandemic. This publication outlines specific tax benefits and credits available, ensuring that eligible individuals can maximize their refunds or minimize their tax liabilities. From the Recovery Rebate Credit to special considerations for the Earned Income Tax Credit, understanding how to utilize this document is essential for anyone looking to optimize their tax situation.
Who Should Pay Attention to Publication 5501?
The primary audience for IRS Publication 5501 includes:
- Individuals who may not have filed a tax return in previous years.
- Those who experienced financial difficulties and want to explore available tax credits.
- Taxpayers eligible for the Recovery Rebate Credit.
- Eligible individuals seeking the Earned Income Tax Credit.
Furthermore, it is crucial for those who are first-time filers or who have had changes in their financial circumstances due to the pandemic to familiarize themselves with this publication. Understanding the implications can significantly affect their financial standing.
Exploring Key Sections of Publication 5501
Recovery Rebate Credit
The Recovery Rebate Credit is a crucial aspect of Publication 5501. This section details how eligible individuals can claim the credit when filing their tax return. If you did not receive the full Economic Impact Payments (EIPs) or did not receive them at all, applying this credit can help you obtain the amounts owed.
To successfully claim the Recovery Rebate Credit, taxpayers should:
- Review their eligibility based on their adjusted gross income (AGI) for 2020.
- Complete Form 1040 or 1040-SR, ensuring the credit is accurately reported.
- Understand that the credit is based on the total amount of EIPs received and any discrepancies should be reported.
Earned Income Tax Credit (EITC)
Another significant section of Publication 5501 provides details on the Earned Income Tax Credit. This credit is designed to benefit low to moderate-income working individuals and families. The publication outlines the eligibility criteria, which includes income thresholds and filing status considerations.
For EITC eligibility, taxpayers should consider the following:
- Income limits vary based on filing status and number of qualifying children.
- Those without qualifying children can still claim EITC but must meet specific income limits.
- Taxpayers must have a valid Social Security number, and investment income must not exceed a specified limit.
Important Dates and Deadlines
IRS Publication 5501 also highlights the critical deadlines that taxpayers must adhere to when filing their tax returns:
- Tax Filing Deadline: Typically April 15. Any extensions would push this date to October 15.
- Recovery Rebate Credit Claims: Must be filed with your 2020 tax return.
- EITC Claims: Also submitted with the annual tax return, ensuring all eligibility criteria are met by the deadline.
Missing these deadlines can result in losing out on potential credits, so awareness is crucial.
Common Pitfalls and How to Avoid Them
Many taxpayers face issues due to incorrect information or failing to file altogether. Here are common pitfalls related to Publication 5501 and how to navigate them:
- Not filing a tax return: Even if you earn below the taxable threshold, filing may be beneficial to receive credits.
- Incorrect AGI reporting: Ensure that the income reported is accurate to avoid discrepancies with the IRS.
- Failing to track economic payments: Keep records of any Economic Impact Payments received to accurately claim the Recovery Rebate Credit.
Submitting Your Claims: Channels and Procedures
Taxpayers have several channels through which they can submit their tax returns, each with its nuances:
| Submission Method | Description | Key Considerations |
|---|---|---|
| Online Filing | Use IRS-approved software for e-filing. | Faster processing and quicker refunds. |
| Paper Filing | Mail in your completed tax forms. | Longer processing time; ensure forms are sent to the correct address. |
| In-Person Filing | Some locations allow for in-person submissions. | Check for availability and local regulations. |
Each method has its benefits and potential drawbacks, so selecting the right one based on individual circumstances can optimize the process.
What to Do in Case of Errors or Missing Documents
In the event of errors in your tax return or if you realize you have not included necessary documentation, prompt action is necessary:
- File an amended return: Use Form 1040-X to make corrections. Be sure to clearly indicate all changes made.
- Respond to IRS notices: If you receive a notice regarding discrepancies, address it as soon as possible to prevent further issues.
- Gather missing documentation: If any documents are missing, obtain them promptly to complete your filings accurately.
Staying proactive in addressing issues can help mitigate potential delays in processing and refund timelines.
Unique Situations and Special Considerations
Taxpayers face diverse financial situations that may require unique considerations when dealing with Publication 5501. Some noteworthy circumstances include:
- Non-resident aliens: These individuals may have different rules regarding EITC eligibility and should consult IRS guidelines for specific criteria.
- Minors: If a minor has earned income, they might also qualify for EITC under certain conditions.
- Individuals with disabilities: Special rules may apply for those who are unable to work, impacting EITC eligibility.
It is vital for individuals in these categories to thoroughly review their eligibility and available options under Publication 5501.
Following Up with the IRS: Understanding the Process
Once you’ve submitted your tax return and any associated claims, understanding how to follow up is essential:
- Track your refund: Use the “Where's My Refund?” tool available on the IRS website for real-time updates.
- Respond promptly: If the IRS contacts you for more information regarding your claim, reply quickly to prevent delays.
- Check for updates: Regularly monitor your account status and be prepared to provide additional documentation if requested.
Being vigilant about the status of your submissions can ensure a smoother process and quicker resolution of any issues that arise.
Final Considerations on IRS Publication 5501
IRS Publication 5501 is a vital resource, especially for those who may have fallen through the cracks during the pandemic. By carefully reviewing the publication, taxpayers can take advantage of benefits that directly impact their financial situation. Remember, every detail counts, and it is crucial to ensure accuracy in all submissions. Familiarity with the guidelines laid out in this publication can be the key to unlocking significant financial relief.
Understanding Investment Income Reporting with IRS Publication 5501
IRS Publication 5501 provides essential guidance for taxpayers who engage in various types of investment transactions. The key objective of this publication is to ensure that all forms of investment income—including dividends, interest, and capital gains—are accurately reported on tax returns. Knowing how to navigate the rules surrounding these types of income can save you from potential penalties or audits.
Investment income generally falls into two primary categories: ordinary income and capital gains. Ordinary income includes accrued interest from bonds and dividends from stocks, while capital gains derive from the profit made on the sale of an asset over what you paid for it. Understanding how these are classified is crucial for correct tax reporting.
A critical aspect of the Publication is its explanation of what constitutes a "realized gain." Taxpayers often wonder whether they need to report gains before an asset is sold. The IRS requires you to report realized gains, meaning you only report profits when you sell an asset. However, if you receive a dividend from stock you still hold, you must report that as income for the year when it is paid, regardless of whether you choose to reinvest it.
Additionally, Publication 5501 discusses various forms required for reporting investment income, including Form 1099-DIV for dividends and Form 1099-INT for interest income. Each form provides detailed information about your earnings, so it’s essential to keep these documents organized. Misreporting or failing to report can lead to audits and penalties, so ensure that you cross-reference these forms with your entries on your tax return.
Tax-Loss Harvesting Strategies and Implications
Tax-loss harvesting is a strategic method used by investors to offset capital gains with losses, effectively reducing your taxable income. IRS Publication 5501 outlines the regulations governing this practice, which can be especially beneficial at tax time. The premise is straightforward: if you sell an investment for less than what you initially paid, the realized loss can be used to mitigate the tax burden from any realized gains in the same tax year.
However, the IRS imposes a "wash sale" rule that can complicate tax-loss harvesting. If you sell a stock at a loss and then repurchase the same stock within 30 days, the IRS will disallow the loss for tax reporting purposes. This rule is designed to prevent taxpayers from claiming a tax benefit while still holding the same investment. Investors must understand the timeline and avoid purchasing the same or substantially identical securities to capitalize on the loss.
Moreover, be aware of the limitations on how much capital loss you can deduct from your ordinary income. Currently, the IRS allows individuals to deduct up to $3,000 ($1,500 if married filing separately) of net capital losses in a single tax year. Any losses beyond that can be carried forward to subsequent years until fully utilized. Therefore, keeping detailed records of your capital transactions and losses is essential for effective tax planning.
State-Specific Considerations in Investment Reporting
While IRS Publication 5501 serves as a federal guideline, state tax laws may differ significantly in how investment income is treated. Each state has its own tax regulations, and as such, taxpayers should be vigilant about their state’s requirements when reporting investment income. For instance, some states tax capital gains at a different rate than ordinary income, while others may not even tax capital gains at all.
Moreover, states may have unique exemptions or credits that can influence the taxation of investment income. For example, states like New Hampshire and Tennessee do not impose a tax on earned income, but they do tax interest and dividends at a flat rate. On the other hand, states like California tax capital gains as ordinary income, which could considerably increase your tax liability depending on your income level.
Taxpayers should also be aware of the implications of multi-state investing. If you invest in assets located in different states or if you are a resident of one state but earn investment income from another, things can get complicated. Some states require non-residents to file tax returns if they earn income from sources within the state. Therefore, it’s often advisable to consult with a tax professional familiar with both federal and state regulations to navigate these complexities effectively.
In summary, IRS Publication 5501 sheds light on crucial aspects of investment income reporting, tax-loss harvesting strategies, and state-specific considerations that every investor should be aware of. Knowledge of these factors can empower taxpayers to make informed financial decisions while remaining compliant with tax regulations.