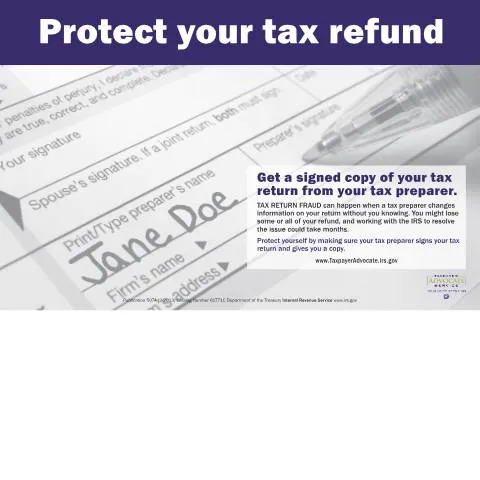
The Critical Role of IRS Publication 5074 in Tax Refund Protection
Navigating the labyrinth of tax regulations can often feel overwhelming, especially when it comes to ensuring that your tax deductions and credits are accurately recorded. IRS Publication 5074 plays a pivotal role in safeguarding your tax refund from potential fraud or mistakes that may occur during the tax preparation process. Designed to clarify your rights as a taxpayer and outline the responsibilities of your tax preparer, this document is instrumental in protecting your financial interests.
Understanding the Scope of Publication 5074
This publication is tailored to inform taxpayers about the importance of verifying their tax preparer's credentials and the necessity of safeguarding their personal information. It emphasizes the potential risks associated with tax return fraud, a growing concern that can lead to the loss of your hard-earned refunds. Publication 5074 serves as a guide, equipping taxpayers with the knowledge needed to protect themselves from unscrupulous practices.
Who Should Engage with Publication 5074?
While any taxpayer can benefit from the insights provided in Publication 5074, it is especially pertinent for those who:
- Engage third-party tax preparers to file their returns
- Have previously experienced issues with inaccuracies in their tax submissions
- Wish to understand the fine print of their rights regarding tax preparation
Understanding your rights and responsibilities can help in mitigating issues before they escalate into larger problems with the IRS.
Taxpayer Rights and Responsibilities Outlined
Publication 5074 emphasizes the importance of being proactive in ensuring your tax return is accurate. Here are some critical points regarding your rights and responsibilities:
- Right to Review: Taxpayers have the right to review their tax returns before filing.
- Right to a Copy: You have the right to receive a signed copy of your tax return from your preparer.
- Due Diligence: It's the taxpayer's responsibility to provide accurate information to their tax preparer.
By understanding these rights, taxpayers can better ensure that their returns reflect their actual financial situations.
Steps for Completing the Process with Publication 5074
The procedure to engage effectively with IRS Publication 5074 involves several crucial steps that taxpayers should follow to protect themselves:
- Read Publication 5074: Familiarize yourself with the guidelines and recommendations.
- Verify Your Preparer’s Credentials: Use the IRS's resources to ensure that your preparer is licensed and in good standing.
- Document Your Information: Always keep copies of documentation you provide to your preparer, including personal identification and income records.
- Review Your Tax Return: Before filing, check all entries for accuracy and completeness.
- Request a Signed Copy: Ensure your tax preparer provides a signed copy of your completed return.
The Importance of Documentation
Proper documentation is key in the tax preparation process. Taxpayers should maintain a thorough record of all communications and submitted paperwork. This includes:
- Copies of all tax returns filed
- Correspondence with your tax preparer
- Received signed forms
By keeping meticulous records, you are better positioned to defend your tax return should discrepancies arise.
Submitting Your Tax Return: Paper vs. Electronic
| Method | Advantages | Considerations |
|---|---|---|
| Paper Filing | Physical receipt; can review all information at once | Longer processing times; potential for delays in refunds |
| Electronic Filing | Faster processing; immediate confirmation of receipt | Must ensure security of electronic data; potential tech issues |
Choosing between paper and electronic filing can impact your overall experience. Electronic filing is generally faster and offers the benefit of tracking your refund status online, while paper filing gives you a tangible copy of your submission.
What Happens When Things Go Wrong?
Even with the best preparations, issues can sometimes arise. If a tax return is rejected or if there are discrepancies, it is essential to know how to respond effectively:
- Review Rejection Notices: Understand the reasons for any rejection thoroughly.
- Correct Errors Promptly: If your return is found to contain errors, correcting these promptly is crucial.
- Communicate with Your Preparer: Discuss any issues with your preparer to facilitate a swift resolution.
If your tax return was filed incorrectly, you may need to amend it using Form 1040-X. It is advisable to act on amendments quickly to avoid penalties or additional taxes.
Dealing with Missing Documentation
Another common issue arises when necessary documentation is missing. Here are steps to take:
- Identify Missing Documents: Check all records and correspondences to pinpoint what is missing.
- Contact Relevant Institutions: Reach out to banks, employers, or other entities for duplicate copies.
- Submit a Request for Extension if Needed: If you cannot acquire documentation in time, request an extension using Form 4868.
How Publication 5074 Fits in the Broader Tax Process
Understanding where Publication 5074 sits within the larger context of tax filing is crucial for effective management of your tax obligations. The publication is part of the IRS's broader initiative to enhance taxpayer education and awareness, particularly concerning the risks associated with tax fraud.
It complements other IRS forms and guidelines that help taxpayers navigate complex processes, including:
- Understanding Forms 1040 and 1040-SR for individual income tax returns
- Utilizing IRS resources to identify legitimate tax preparers
- Finding guidance on various tax credits and deductions
This interconnectedness emphasizes the importance of being well-informed and proactive in your tax dealings.
Ensuring Your Refund is Safe
Ultimately, the insights provided in IRS Publication 5074 are designed to protect your financial well-being. By adhering to its guidelines, you mitigate the risks of tax refund fraud and errors that could otherwise lead to lengthy disputes with the IRS.
Taxpayers who take the initiative to educate themselves and engage responsibly with their tax preparers can navigate the complexities of the tax system with greater confidence. A well-informed taxpayer is a powerful ally in ensuring that government systems work effectively for individuals and families alike.
Understanding IRS Publication 5074: An In-Depth Overview
IRS Publication 5074, officially titled "Tax Guide for Nonresidents," provides crucial information for nonresident aliens who are required to file U.S. tax returns. This publication outlines the specific tax obligations and reporting requirements for individuals who are not U.S. citizens or permanent residents but earn income within the United States. It highlights critical concepts such as residency status, income types subject to taxation, and applicable tax treaties, thus serving as an essential resource for anyone navigating the complexities of nonresident taxation.
Residency Status and Its Implications
Determining your residency status is pivotal when filing taxes in the U.S. Nonresident aliens are typically those who do not meet either the Green Card test or the Substantial Presence test as defined by the IRS. The Green Card test is satisfied if an individual is a lawful permanent resident of the United States at any time during the calendar year. The Substantial Presence test is more nuanced, requiring individuals to count days of physical presence in the U.S. over a three-year period. Understanding your residency status affects not only how and when you file but also the tax rates applied to your income.
Nonresidents are generally taxed only on income sourced from the U.S. This includes wages, salaries, tips, and certain types of investment income. However, it’s essential to recognize that nonresident aliens may also be eligible for certain deductions to minimize their taxable income. Publication 5074 provides examples of eligible deductions, such as certain business expenses and student loan interest, which can be particularly beneficial for nonresidents who are also students in the United States.
Tax Treaties: Navigating International Tax Obligations
Another vital aspect covered in IRS Publication 5074 is the issue of tax treaties. The United States has entered into tax treaties with many countries to prevent double taxation and provide clarity on tax obligations for foreign nationals. These treaties often provide reduced tax rates or exemptions for certain types of income, such as dividends, interest, and royalties.
When assessing potential benefits from tax treaties, nonresident aliens must ensure they meet specific criteria, including having the appropriate documentation, such as Form W-8BEN. This form certifies the foreign status of the individual and claims any applicable benefits under the treaty. Publication 5074 details how to determine if a tax treaty applies to your situation and how to appropriately leverage these agreements to minimize tax liability.
Additionally, it is crucial for nonresidents to be aware of the reporting obligations that come with claiming tax treaty benefits. Certain forms may need to be submitted along with the tax return, and failure to comply can lead to penalties or denied treaty benefits. Understanding the nuances outlined in Publication 5074 can help nonresident aliens take full advantage of tax treaties while ensuring compliance with U.S. tax laws.