Understanding the IRAS Form for Qualifying Amalgamations under Section 34C of the Income Tax Act 1947
The Inland Revenue Authority of Singapore (IRAS) provides a specific form for companies involved in qualifying amalgamations under Section 34C of the Income Tax Act (ITA) 1947. This form is an essential administrative tool designed to facilitate the tax treatment of corporate mergers that meet certain criteria. It ensures compliance with tax regulations and clarifies the tax implications for the involved companies.
Scope and Purpose of the Form
This form is intended for companies that are undertaking a qualifying amalgamation, which involves the merger of two or more companies into a single entity. The primary purpose is to elect the application of Section 34C of the ITA, which provides specific tax rules for such amalgamations. By submitting this form, companies confirm their intention to be taxed under the provisions of Section 34C, thereby potentially benefiting from specific tax treatments associated with qualifying mergers.
The form is designed to be completed digitally, typically taking around 10 minutes, and should be submitted either via post or through the myTax portal, IRAS’s official online platform for tax submissions.
Who Should Use This Form?
The form is applicable to companies that have undergone a qualifying amalgamation, which is recognized under the legal framework of Singapore’s company and tax laws. Companies planning to amalgamate and wish to avail themselves of the tax provisions under Section 34C must submit this form. It is particularly relevant for companies that have received a court order, a notice of amalgamation under the Companies Act, or approval under the Banking Act, as these documents are required to accompany the submission.
Key Sections of the Form
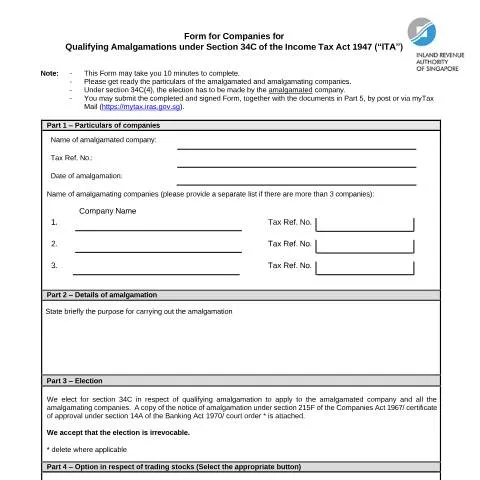
Part 1 – Particulars of the Companies
This section requires details about the amalgamated company and the amalgamating companies. Information such as the legal names, tax reference numbers, and the date of amalgamation must be provided. If more than three companies are involved, a separate list should be attached.
Part 2 – Details of the Amalgamation
Here, the applicant should briefly state the purpose of the amalgamation. This provides context for the tax election and helps IRAS assess the qualifying nature of the merger.
Part 3 – Election
This section involves an explicit declaration by the companies to apply Section 34C to the amalgamation. The applicant must confirm that the necessary legal documents, such as the notice of amalgamation or court order, are attached. The election is stated to be irrevocable once submitted.
Part 4 – Option for Trading Stocks
Companies can choose how to value trading stocks taken over during the amalgamation. The options include:
- Net Book Value
- Fair Value
This choice affects the calculation of consideration given by the amalgamated company to the amalgamating companies for stocks. The selected option is also irrevocable.
Part 5 – Supporting Documents
Applicants must submit relevant documents, such as:
- A copy of the amalgamation proposal
- A list of investment assets transferred to the amalgamated company
- Finalized accounts and tax computations of each amalgamating company for the relevant assessment years
- Any outstanding tax returns of the amalgamating companies
These documents support the election and facilitate IRAS’s review process.
Legal and Administrative References
The form references specific legal provisions, notably section 34C(11) and 34C(12) of the ITA, which outline the statutory basis for the election and its implications. Applicants should ensure they understand these provisions and prepare their documentation accordingly.
For further guidance, IRAS recommends consulting the IRAS e-Tax Guide on the Tax Framework for Corporate Amalgamations, which provides detailed explanations of the tax treatment and compliance requirements.
Submission and Contact Details
The completed form, along with the supporting documents, can be submitted via the IRAS online portal, myTax, or by mail to:
55 Newton Road, Revenue House, Singapore 307987For assistance or inquiries, IRAS provides a dedicated helpline at 1800-356 8622, and more information can be found on their official website.
In summary, this IRAS form is a crucial step for companies engaged in qualifying amalgamations, ensuring their merger benefits from the specific tax provisions under Section 34C of the ITA. Proper completion and submission of this form facilitate compliance and optimize tax outcomes for corporate mergers in Singapore.