Understanding the Notice under Section 23C of the Stamp Duties Act in Singapore
The Notice under Section 23C issued by the Commissioner of Stamp Duties is an official document that plays a crucial role in the administration of stamp duty related to property ownership in Singapore. Managed by the Inland Revenue Authority of Singapore (IRAS), this notice is part of the legal framework designed to ensure transparency and proper taxation of equity interests in residential property-holding entities.
Purpose and Scope of the Notice
This notice is primarily used to report changes in the beneficial ownership of equity interests in residential property-holding entities. When a person or entity acquires or disposes of a significant or beneficial interest in such an entity, the parties involved must notify IRAS within a specified timeframe. The purpose is to facilitate the accurate assessment of Additional Conveyance Duties (ACD), which are applicable when there are changes in beneficial ownership that could impact stamp duty obligations.
It is important to note that the notice is mandatory and must be submitted within 14 days of the change in ownership. Failure to do so may result in penalties or additional tax assessments. The document is designed to gather detailed information about all relevant parties, the nature of their ownership interests, and the specifics of the arrangement leading to the change.
Who Must Submit the Notice?
The notice applies to all parties involved in the beneficial ownership of residential property-holding entities. This includes:
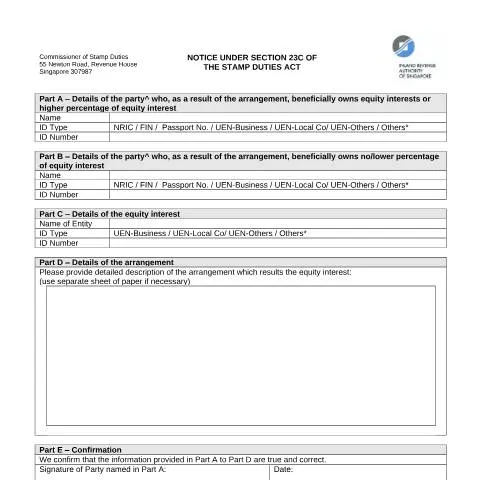
- The individual or entity who, as a result of the arrangement, beneficially owns a higher percentage of equity interest (Part A).
- The individual or entity who, as a result of the arrangement, beneficially owns no or a lower percentage of equity interest (Part B).
- The entity involved in the arrangement, including details such as its name and registration number (Part C).
Additionally, trustees holding equity interests on behalf of beneficiaries are also required to report, especially if they hold the interest under a trust arrangement.
Key Components of the Notice
Part A & Part B: Details of Beneficial Owners
These sections require the disclosure of the identities of the parties involved, including their identification type (NRIC, FIN, Passport, UEN), and their respective identification numbers. The distinction between Part A and Part B helps IRAS understand the change in ownership percentage resulting from the arrangement.
Part C: Details of the Entity
This part involves providing information about the entity holding the equity interest, including its name and Unique Entity Number (UEN). This helps IRAS link ownership changes to specific property-holding entities registered in Singapore.
Part D: Description of the Arrangement
A detailed explanation of the arrangement that led to the change in beneficial ownership is required. This could include information about transactions, trusts, or other legal arrangements that impact ownership interests. Additional sheets may be attached if necessary to provide comprehensive details.
Part E: Declaration
All parties involved must declare the accuracy of the information provided by signing and dating the notice. This legal affirmation ensures accountability and helps IRAS maintain accurate records.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Legal and Procedural Considerations
The notice is a legal requirement under the Stamp Duties Act, specifically under Section 23C. It is essential for property owners, trustees, and related parties to adhere strictly to the reporting obligations to avoid penalties. The IRAS website provides further guidance on the applicable ACD rates and the calculation methodology, which is based on the market value of the residential properties involved.
It is advisable to consult the IRAS e-Tax Guide on Stamp Duty: Additional Conveyance Duties (ACD) on Property-Holding Entities for detailed information on rates and procedures. The process is designed to be digital-first, with submissions made via the IRAS online portal, ensuring secure and efficient compliance.
Summary
The Notice under Section 23C serves as a vital tool for IRAS to monitor and tax beneficial ownership changes in residential property-holding entities. It ensures transparency, compliance with stamp duty obligations, and accurate assessment of additional conveyance duties. Parties involved in property transactions should be aware of their reporting obligations and use the official channels provided by IRAS to submit the required information promptly and correctly.