Understanding the IRAS Notice Under Sections 60I and 60J of the Stamp Duties Act
The Inland Revenue Authority of Singapore (IRAS) issues Notices under Sections 60I and 60J of the Stamp Duties Act to ensure transparency and compliance in transactions involving certain assets, particularly within the context of umbrella Variable Capital Companies (VCCs). This official communication serves as a formal requirement for VCCs and involved parties to declare specific transaction details to IRAS, facilitating proper assessment of stamp duties and related tax obligations.
Purpose and Scope of the Notice
This notice is a mandatory submission that must be filed within 14 days of the transaction date. Its primary purpose is to inform IRAS about the transfer or transaction involving chargeable assets, which may include immovable properties, shares, or other assets. The declaration helps IRAS verify that stamp duties are correctly assessed and paid, thereby supporting Singapore’s tax compliance framework.
The notice applies specifically to transactions involving umbrella VCCs and their sub-funds, especially when assets are transferred or exchanged between these entities. It is a crucial document for maintaining transparency within the financial and corporate sectors, particularly in the context of fund management and asset transfer activities.
Key Components of the Notice
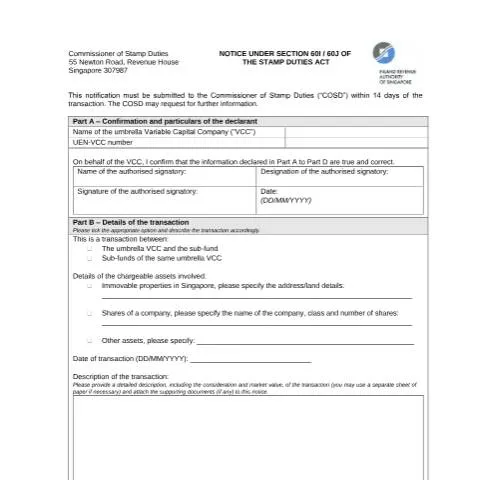
Part A: Confirmation and Declarant Details
This section requires the VCC to confirm the accuracy of the declared information and to provide details about the authorized signatory submitting the notice. The following information must be included:
- Name of the VCC (the umbrella Variable Capital Company)
- UEN-VCC number (Unique Entity Number)
- Name of the authorized signatory
- Designation of the signatory within the VCC
- Signature and date of submission
Part B: Transaction Details
This section captures specifics about the transaction, including:
- Type of transaction: whether it is between the umbrella VCC and a sub-fund or between sub-funds of the same VCC
- Details of chargeable assets involved, such as immovable properties, shares, or other assets
- Date of the transaction
- A detailed description of the transaction, including considerations, market value, and supporting documents
Part C and D: Parties Involved
The form requires details of both the transferor and the transferee:
- Part C: Information about the party from whom the asset is transacted (either the VCC or the sub-fund)
- Part D: Information about the party to whom the asset is transacted (either the VCC or the sub-fund)
Each part asks for the name and identification number of the involved parties, ensuring clarity on the transaction's participants.
How to Use the IRAS Notice
Once completed, the notice must be submitted electronically via the IRAS e-Services portal, typically through the Stamp Duty e-Submission system. The submission should include all relevant supporting documents, such as sale agreements, valuation reports, or other evidence that substantiate the declared transaction details.
Failure to submit this notice within the stipulated 14-day period may result in penalties or delays in stamp duty assessment. IRAS reserves the right to request additional information or clarification to verify the transaction details.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Resources and Reference
For further guidance, VCCs and involved parties should refer to the official IRAS website, which provides detailed instructions on stamp duty obligations and the electronic submission process. The Stamp Duties Act and related regulations also offer legal context for these requirements.
It is recommended to consult professional tax advisors or legal experts when preparing and submitting this notice to ensure compliance and accuracy in reporting.
Conclusion
The IRAS Notice under Sections 60I and 60J is a vital instrument in Singapore’s tax administration, particularly within the evolving landscape of fund management and asset transfer. By understanding its purpose and correctly completing the required information, VCCs and their sub-funds can maintain compliance, ensure timely assessment, and uphold transparency in their transactions.