Understanding the IRAS Notice Under Section 22C: Key Information for Beneficiaries of Residential Property Trusts in Singapore
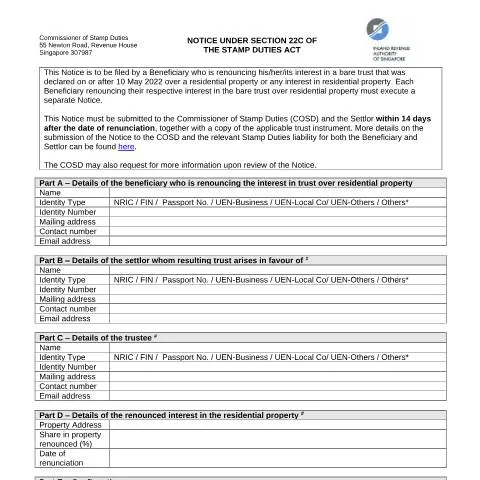
The Inland Revenue Authority of Singapore (IRAS) issues a specific notice under Section 22C of the Stamp Duties Act, which pertains to beneficiaries who wish to renounce their interest in a bare trust over residential property. This notice is part of Singapore’s efforts to enhance transparency and compliance in property transactions, especially concerning the declaration and transfer of beneficial interests in residential properties.
Scope and Purpose of the Notice
This official notice is mandatory for any beneficiary who, on or after 10 May 2022, chooses to renounce their interest in a bare trust relating to residential property or any interest therein. A bare trust, in this context, refers to a trust where the beneficiary holds the property in a purely fiduciary capacity, with no active duties or powers over the property. The notice aims to ensure proper documentation of such renunciations, which can have implications for stamp duties and legal ownership records.
Each beneficiary must submit a separate notice if they renounce their interest in the trust. The process involves notifying the IRAS and providing relevant details about the beneficiary, the settlor (the person who established the trust), and the trustee managing the trust.
Key Components of the Notice
Part A: Beneficiary Details
This section requires the beneficiary to provide personal information, including their name, identification type (NRIC, FIN, passport, or UEN), identification number, mailing address, contact number, and email address. Accurate completion ensures proper processing and correspondence.
Part B: Settlor Information
The settlor’s details are also necessary, including their name, identification type and number, mailing address, contact details, and email. This information establishes the origin of the trust and clarifies the relationship between the settlor and the beneficiary.
Part C: Trustee Details
If applicable, details of the trustee managing the trust are required. Similar to the other sections, this includes name, identification, contact information, and address. The trustee’s role is crucial in managing the trust and executing the renunciation process.
Part D: Details of the Renounced Interest
This section specifies the property address, the percentage share of the property interest being renounced, and the date of renunciation. Precise information here is essential for accurately recording the transfer of beneficial interest and calculating any stamp duty liabilities.
Part E: Declaration and Confirmation
The beneficiary must confirm the truthfulness of the information provided and agree to serve a copy of the notice on the settlor within 14 days of renunciation. Providing false information constitutes an offence under the Stamp Duties Act, with penalties including fines or imprisonment.
Legal and Practical Considerations
Submitting this notice is a legal requirement for beneficiaries renouncing their interest in residential property trusts declared on or after 10 May 2022. It must be done within 14 days of the renunciation date, and a copy of the notice must be served on the settlor promptly.
Failure to comply with these requirements can result in legal penalties and affect stamp duty liabilities. The IRAS may also request additional information during the review process to ensure compliance and accuracy.
How to Use This Notice Effectively
Beneficiaries should prepare all necessary information before completing the notice, ensuring accuracy and completeness. The notice must be signed and dated by the beneficiary or their authorized representative. Once submitted, it becomes part of the official record of the trust and renunciation.
It is advisable to consult legal or tax professionals if there are uncertainties regarding the implications of renouncing a beneficial interest or the proper completion of the notice. Ensuring compliance with IRAS requirements helps avoid penalties and facilitates smooth property ownership transitions.
Summary of Points to Remember
- The notice is mandatory for beneficiaries renouncing interests in residential property trusts declared on or after 10 May 2022.
- It must be submitted within 14 days of the renunciation date to the IRAS and served on the settlor.
- Accurate and complete information in all parts of the notice is essential for compliance and proper record-keeping.
- False declarations can lead to legal penalties, including fines and imprisonment.
- Consultation with legal or tax advisors is recommended to navigate the process effectively.
Understanding and adhering to the requirements outlined in the IRAS Notice Under Section 22C ensures transparency and legal compliance in the management and transfer of beneficial interests in residential property trusts in Singapore.