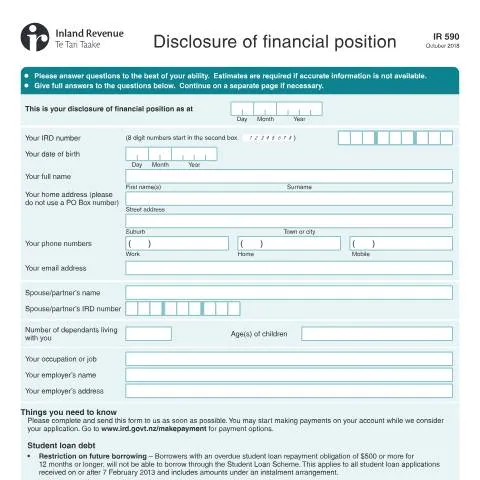
Understanding the IR590: A Key Document in Financial Transparency
When navigating the complexities of tax obligations in New Zealand, the IR590, or the Disclosure of Financial Position form, serves as a crucial document for individuals and entities facing financial difficulties. This form is not just a bureaucratic requirement; it represents a substantial step towards managing tax debts and ensuring that individuals remain compliant with the New Zealand tax system.
The Trigger: When to File the IR590
There are several scenarios that can prompt you to file the IR590. Typically, if you find yourself unable to meet your tax obligations due to financial strain, this form becomes essential. It acts as a formal declaration to the Inland Revenue Department (IRD) about your financial situation and is often required when:
- You have tax debt and wish to negotiate a payment plan.
- Your student loan debt has reached a critical level that restricts future borrowing.
- You are seeking to disclose your financial position to manage potential penalties related to late payments.
Filing the IR590 not only demonstrates your willingness to address your tax obligations but also helps the IRD make informed decisions regarding your situation.
Gathering Your Financial Information: Preparation is Key
Before diving into the details of the IR590, it’s important to gather all necessary financial documents and information to ensure accuracy throughout the process. This preparation phase might feel overwhelming, but breaking it down into smaller components can simplify the task. Here are the categories of information you’ll need:
Income Sources
Compile a detailed list of all household income. This includes:
- Salary or wages from your job
- Benefits from Work and Income, if applicable
- Any self-employed income
- Support payments such as child support or maintenance received
- Other income streams like dividends or rental income
Assets and Liabilities
Take stock of your assets, which may include:
- Residential and commercial properties
- Vehicles
- Personal effects with a market value greater than $5,000
Equally important is to detail your liabilities, such as outstanding mortgages, loans, or any other financial obligations.
Trusts and Entities
If you have been involved with any trusts or other entities in the past five years, gather relevant information including the names, IRD numbers, and your roles within these entities.
Navigating the Form: A Detailed Walkthrough
The IR590 is structured to guide you through the reporting of your financial position. Below is a breakdown of key sections of the form along with tips to avoid common pitfalls:
Personal Identification Details
The first part of the form requires personal information such as:
- Your full name, date of birth, and address (ensure you do not use a PO Box).
- Your IRD number and contact information.
Tip: Double-check your IRD number and ensure that all details are up to date to avoid processing delays.
Income Reporting
In the income section, you’ll report your and your partner's incomes separately. It's critical to be thorough and honest:
- List all sources of income accurately, including frequency (weekly, fortnightly, monthly).
- If you receive variable income, provide best estimates supported by any past documentation.
Property and Assets Details
Here, you need to disclose information about any properties owned:
- Provide the purchase date, price, and estimated current value.
- Include all details regarding mortgages, including providers and repayment amounts.
Be careful: Underreporting your assets can lead to complications and potential penalties.
Submitting the IR590: Your Options
Once you have completed the IR590, it’s time to submit it to the IRD. You can do this through various channels:
Online Submission
The IRD encourages digital submissions via their online platform. This method is typically faster and allows for immediate processing. To submit online, you will need:
- A RealMe digital ID for secure access.
- An internet connection and the ability to upload documents if necessary.
Mail Submission
If you prefer a traditional route, you can print the completed form and send it via post. Ensure you:
- Keep copies of everything for your records.
- Consider using registered mail for tracking purposes.
In-Person Submission
While not common, you may also choose to visit an IRD office. This option allows you to ask questions on the spot but may require waiting in line.
Following Up: What Happens Next?
After submitting your IR590, the IRD will review your disclosures and make a decision regarding your tax obligations. Here's what you can expect during the processing phase:
Notification from the IRD
Typically, you will receive a letter or email within a few weeks outlining their decision. If further information is needed, they will contact you directly.
Setting Up Payment Arrangements
If you're seeking to establish a payment arrangement due to tax debt, the IR590 enables you to propose a plan:
- Specify the amount you can pay now and the frequency of future payments.
- Be realistic in your proposal; the IRD is more likely to accept reasonable offers.
Potential Outcomes
Depending on your financial situation, the IRD may:
- Accept your payment plan, suppress penalties temporarily, or offer advice on further financial support.
- Decline your proposal if the financial information provided does not justify your request.
Consequences of Non-disclosure or Inaccuracy
It’s essential to understand that failing to accurately disclose your financial position can have serious repercussions.
Penalties and Interest
If it’s discovered that you have underreported income or assets, you may face penalties that include:
- Late payment penalties on outstanding tax debts.
- Interest on overdue amounts which continues to accrue during arrangements.
Impact on Future Borrowing
For those with student loans, an unpaid tax obligation could limit your future borrowing capacity. Specifically, if the outstanding amount exceeds $500 for over a year, consequences will restrict further student loan applications.
The Regulatory Framework: Understanding the Legislation
Understanding the legal backdrop of the IR590 can empower taxpayers to navigate their obligations more confidently. The form operates under various legislative frameworks, including:
- The Official Information Act 1982, which ensures transparency and access to information held by the government.
- The Plain Language Act 2022, aimed at making government documentation more accessible and easier to understand for all citizens.
These regulations support taxpayers, ensuring they are informed and have a clear understanding of their rights and obligations when engaging with the tax system.
A Practical Checklist for IR590 Submission
| Task | Status |
|---|---|
| Gather all necessary financial documents | ✔️ |
| Complete the IR590 form accurately | ✔️ |
| Decide on submission method (online/mail/in-person) | ✔️ |
| Propose a realistic payment plan if applicable | ✔️ |
| Follow up with the IRD after submission | ✔️ |
By adhering to this checklist, you not only streamline your submission process but also reduce the chances of errors that could lead to further complications.
In conclusion, the IR590 form is more than a mere formality; it is an essential tool for anyone who finds themselves in a difficult financial position. By understanding its role and the steps involved in its completion and submission, you can take proactive measures to manage your tax obligations effectively. Remember, the key to successfully navigating the IRD's requirements lies in transparency and open communication.
Understanding Disclosure Requirements for Financial Statements in New Zealand
In New Zealand, the disclosure of financial position is governed by the Financial Reporting Act and relevant accounting standards, including the New Zealand Equivalent to International Financial Reporting Standards (NZ IFRS). Understanding these requirements is essential for businesses to maintain transparency and accountability in their financial reporting.
The core objective of financial disclosure is to provide stakeholders, including investors, creditors, and shareholders, access to relevant financial information that enables them to make informed decisions. Companies must disclose their financial position, performance, and changes in financial position, as well as any risks they may face.
Key Components of Financial Disclosure
Statement of Financial Position: This document summarizes a company's assets, liabilities, and equity at a specific point in time. It provides stakeholders with a snapshot of the company's financial health.
Statement of Comprehensive Income: This outlines the company's performance over a given period, detailing revenues, expenses, and profits or losses. It can also include other comprehensive income, reflecting changes in equity that are not a result of transactions with owners.
Notes to the Financial Statements: These notes provide additional context and detail for the numbers presented in the financial statements. They may include accounting policies, breakdowns of specific line items, and disclosures about risks and uncertainties.
Cash Flow Statement: Essential for understanding the liquidity of a company, this statement shows the cash inflows and outflows over a specific period, categorized into operating, investing, and financing activities.
Management Commentary: This optional but valuable section allows management to explain the financial results, outline future expectations, and provide insights into the company’s strategy.
Variations for Different Entities
The level of detail and the specific disclosures required can vary significantly depending on the size and type of entity.
Large companies are required to comply with full NZ IFRS disclosures, which demand extensive information due to their potential impact on the market and investor decisions.
Medium-sized entities may use the tier 2 reporting framework under the Accounting Standards Framework, which is less demanding than full NZ IFRS but still requires a robust level of disclosure.
Small entities may opt for tier 3 reporting standards, allowing for simpler financial reports with less extensive disclosures, provided they meet certain criteria.
Compliance and Enforcement of Financial Disclosure Regulations
Ensuring compliance with financial disclosure regulations in New Zealand is essential for maintaining the integrity of the financial markets and protecting stakeholders' interests. The Financial Markets Authority (FMA) oversees and enforces compliance with these regulations.
Role of the Financial Markets Authority (FMA)
The FMA plays a vital role in monitoring company disclosures to ensure they are accurate, complete, and comply with relevant laws and accounting standards. The authority has the power to investigate complaints and irregularities in financial reporting and can impose penalties for non-compliance.
Importance of Audit
For companies required to disclose their financial positions, undergoing an independent audit is often a mandated process. Auditors assess the fairness and accuracy of the financial statements and ensure that they reflect the company’s true financial condition. They provide an additional layer of assurance to stakeholders about the reliability of the financial information.
Consequences of Non-Compliance
Failure to comply with financial disclosure requirements can lead to severe consequences, including:
Financial Penalties: Companies may face fines imposed by the FMA for inaccurate reporting or failure to disclose material information.
Legal Action: Stakeholders may pursue legal claims against companies for losses incurred due to misleading disclosures or omissions.
Reputation Damage: Non-compliance can severely damage a company’s reputation, leading to a loss of investor confidence and potential long-term financial challenges.
Therefore, businesses must prioritize compliance and ensure that their financial disclosures are accurate, timely, and transparent.
Transparency and Ethical Considerations in Financial Disclosure
Transparency in financial disclosures is not just a legal requirement; it is also a fundamental ethical obligation for businesses operating in New Zealand. Stakeholders expect openness regarding a company's financial health, and ethical practices in disclosure can significantly influence public trust and investor relationships.
Ethical Frameworks Guiding Financial Disclosure
The New Zealand Institute of Chartered Accountants (NZICA) emphasizes the importance of ethical behavior in financial reporting. Adhering to ethical frameworks can guide companies in making decisions about what information to disclose and how to present it.
The Role of Corporate Governance
Effective corporate governance structures play a critical role in ensuring that disclosures are not only compliant but also reflect ethical considerations. Strong governance mechanisms, such as audit committees and clear internal controls, can help mitigate the risk of fraudulent reporting or misrepresentation of financial positions.
Building Trust Through Transparency
Companies that prioritize transparency in their financial disclosures tend to foster better relationships with stakeholders, leading to:
Increased Investor Confidence: When businesses transparently share their financial information, investors are more likely to trust their management and make informed decisions based on accurate data.
Enhanced Reputation: Ethical practices in financial reporting can enhance a company’s reputation in the industry, attracting customers and business partners who value integrity.
Long-term Sustainability: Companies that commit to ethical financial disclosure practices are more likely to achieve sustainable growth, as they build a loyal base of stakeholders who believe in their mission and values.
In summary, the ethical dimension of financial disclosure in New Zealand is crucial for fostering trust and accountability, ensuring businesses operate responsibly and transparently.