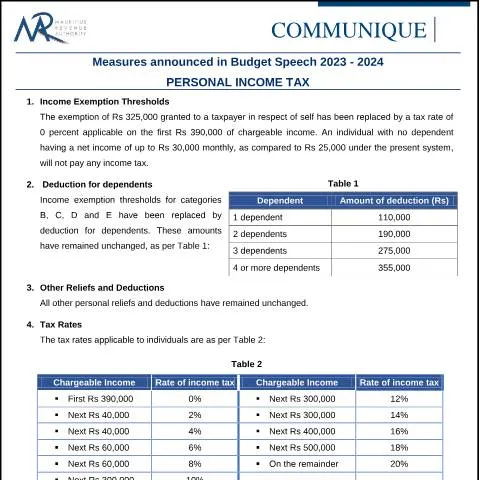
Overview of the Budget Speech 2023-2024: Personal Income Tax Measures in Mauritius
The Mauritius Revenue Authority (MRA) has issued a formal notice outlining the key changes to personal income tax provisions announced during the Budget Speech for the fiscal year 2023-2024. These measures aim to adjust the tax framework to better reflect current economic conditions and provide relief to taxpayers. This guide summarizes the main points of the new tax measures, their implications for individuals, and the official references for further information.
Context and Scope of the Tax Reforms
The recent amendments to personal income tax are part of the government's efforts to enhance fiscal fairness and stimulate economic activity. Effective from the income year starting on 1st July 2023, these measures modify existing thresholds, rates, and reliefs to align with the current cost of living and income distribution. The changes primarily focus on increasing the exemption threshold, adjusting deductions for dependents, and eliminating the solidarity levy. It is important for all individual taxpayers, especially those with income sources within the specified brackets, to understand these modifications to ensure compliance and optimize their tax planning.
Who Is Affected by These Changes?
The revised tax measures impact individual taxpayers earning income within the specified thresholds and categories. This includes:
- Taxpayers with net monthly income up to Rs 30,000, who, under the new regime, will not be liable to pay income tax.
- Individuals claiming dependents, as the previous exemption amounts have been replaced by a standardized deduction for dependents.
- All taxpayers subject to the applicable progressive tax rates, which now start at a higher exemption level.
Key Points of the New Personal Income Tax Measures
1. Increased Income Exemption Threshold
The exemption threshold has been raised from Rs 325,000 to Rs 390,000. This means that the first Rs 390,000 of chargeable income is now taxed at 0%, providing immediate relief to low and middle-income earners.
For example, an individual earning up to Rs 30,000 monthly (which totals Rs 360,000 annually) will not be subject to income tax under the new threshold, compared to Rs 25,000 monthly previously.
2. Replacement of Exemption for Dependents by Deduction
The previous system allowed for specific exemption amounts for categories B, C, D, and E dependents. These have now been replaced by a unified deduction for dependents, with the following amounts:
| Number of Dependents | Deduction (Rs) |
|---|---|
| 1 | 110,000 |
| 2 | 190,000 |
| 3 | 275,000 |
| 4 or more | 355,000 |
3. Adjustment of Tax Rates
The applicable progressive tax rates have been maintained but now commence after the Rs 390,000 exemption threshold. The rates are as follows:
| Chargeable Income (Rs) | Tax Rate |
|---|---|
| Up to 390,000 | 0% |
| Next 300,000 | 12% |
| Next 40,000 | 2% |
| Next 300,000 | 14% |
| Next 40,000 | 4% |
| Next 400,000 | 16% |
| Next 60,000 | 6% |
| Next 60,000 | 8% |
| Next 300,000 | 10% |
| Remaining amount | 20% |
4. Abolition of the Solidarity Levy
The solidarity levy, previously applicable to certain income brackets, has been abolished in the current fiscal year. This change simplifies the tax calculation process and reduces the overall tax burden for eligible taxpayers.
Implementation and Official References
The outlined measures are effective starting from the income received on or after 1st July 2023. Taxpayers are encouraged to review their income and deductions accordingly to ensure compliance with the new regulations.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
For detailed information, official forms, and guidance, taxpayers can consult the Mauritius Revenue Authority's official communications and the relevant sections on the government’s e-services portal.
Further details on the legal framework and official notices regarding these measures can be accessed through the Mauritius Revenue Authority’s official website or by contacting their offices directly.
Conclusion
The Budget Speech 2023-2024 introduces significant adjustments to personal income tax, primarily aimed at increasing exemption thresholds and simplifying deductions for dependents. These changes are designed to provide immediate relief to taxpayers and streamline the tax system. Citizens and residents are advised to stay informed and seek professional advice if needed to optimize their tax obligations under the new regime.