Overview of the VAT Measures Implemented in Budget Speech 2025-2026
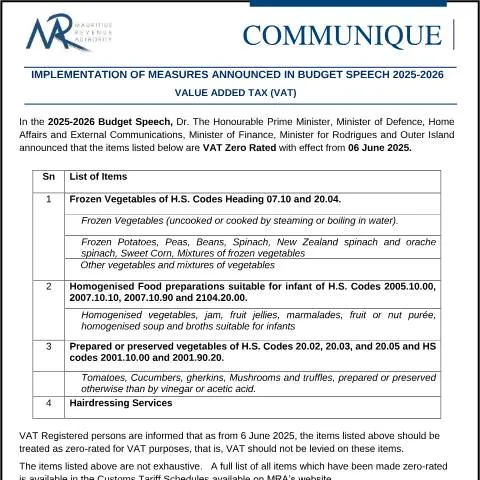
The Mauritius Revenue Authority (MRA) has issued an official notice regarding the implementation of new Value Added Tax (VAT) measures announced during the Budget Speech 2025-2026, delivered by the Prime Minister and Minister of Finance on 12 June 2025. These measures primarily concern the zero-rating of specific goods and services effective from 6 June 2025, aimed at supporting consumers and promoting certain sectors of the economy.
Scope and Purpose of the Notice
This official communication serves to inform VAT-registered persons and businesses about the recent amendments to the VAT regime, specifically the items that are now classified as zero-rated. The objective is to clarify the VAT treatment of these items, ensuring compliance and facilitating proper accounting and reporting practices for businesses involved in the supply and sale of these goods and services.
It is important to note that this notice does not constitute a comprehensive list of all zero-rated items but highlights key categories announced in the Budget Speech. The full list can be accessed through the Customs Tariff Schedules available on the official MRA website.
Key Items and Sectors Affected by the Zero-Rating
Frozen Vegetables
Effective from 6 June 2025, frozen vegetables classified under H.S. Codes 07.10 and 20.04 are now zero-rated. This includes a broad range of frozen produce such as potatoes, peas, beans, spinach, sweet corn, and vegetable mixtures. These items encompass both uncooked and cooked vegetables, including specific varieties like New Zealand spinach and orache.
Homogenised Food Preparations for Infants
The measure also applies to homogenised food preparations suitable for infants, classified under H.S. Codes 2005.10.00, 2007.10.10, 2007.10.90, and 2104.20.00. These include homogenised vegetables, fruit jams, jellies, marmalades, fruit or nut purées, as well as homogenised soups and broths intended for infant consumption.
Prepared or Preserved Vegetables
Additional items affected are prepared or preserved vegetables such as tomatoes, cucumbers, gherkins, mushrooms, and truffles, classified under H.S. Codes 20.02, 20.03, 20.05, as well as certain processed vegetables under H.S. Codes 2001.10.00 and 2001.90.20. These are to be treated as zero-rated regardless of preservation methods other than vinegar or acetic acid.
Hairdressing Services
Beyond tangible goods, the zero-rating extends to specific services, notably hairdressing services, which are now exempt from VAT as of the effective date. This measure aims to reduce the financial burden on consumers accessing personal grooming services.
Implications for VAT-Registered Entities
VAT-registered businesses and persons are advised that from 6 June 2025, the listed items and services should be treated as zero-rated for VAT purposes. This means that no VAT should be levied on the sale or supply of these goods and services, nor should input VAT be claimed on related purchases, subject to compliance with existing VAT regulations.
Businesses must update their accounting systems accordingly to reflect the zero-rating status and ensure proper documentation for audit and reporting purposes. It is also recommended to consult the full list of zero-rated items, available in the Customs Tariff Schedules, to verify the applicable classifications.
Additional Information and Resources
The official notice emphasizes that the list provided is not exhaustive. For a comprehensive overview, VAT-registered persons should consult the full list of zero-rated items accessible via the MRA’s official website at www.mra.mu/download/TariffInformation060625.pdf. This resource provides detailed classifications and descriptions to assist in compliance.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
For further assistance or clarification, VAT-registered persons and businesses are encouraged to contact the Mauritius Revenue Authority directly through their official communication channels, including the head office located at Ehram Court, Port Louis.
Legal and Administrative Context
The measures announced align with the broader fiscal policy objectives outlined in the 2025-2026 Budget, aiming to support household welfare and stimulate economic activity. The implementation follows the legal framework established under the VAT Act and related regulations, with the Mauritius Revenue Authority responsible for enforcement and compliance monitoring.
Businesses and individuals are reminded that non-compliance with VAT regulations, including incorrect treatment of zero-rated items, may attract penalties under the current legal provisions. Therefore, staying informed and adhering to the official guidelines is essential for legal compliance and smooth business operations.