Understanding the Research and Development Corporation Tax Credit Pre-filing Notification Form in Ireland
In Ireland, companies engaged in qualifying research and development (R&D) activities may be eligible for a Corporation Tax Credit under section 766C of the Taxes Consolidation Act 1997 (TCA 1997). To initiate the process of claiming this credit, businesses are required to submit a specific pre-filing notification form to the Revenue Commissioners. This article provides an overview of the purpose, requirements, and key considerations associated with the Research and Development Corporation Tax Credit Pre-filing Notification Form.
Purpose and Legal Context of the Pre-filing Notification
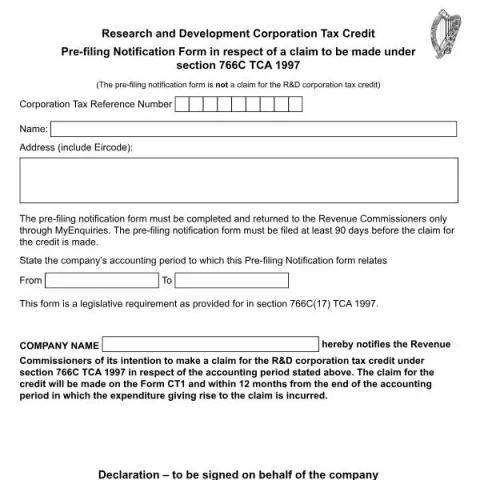
The primary purpose of the pre-filing notification (Form 766C) is to inform the Irish Revenue Commissioners of a company's intention to claim the R&D tax credit for a specific accounting period. It is important to note that this form is not a claim itself but a legislative requirement under section 766C(17) TCA 1997. The notification must be submitted at least 90 days prior to the submission of the actual claim, which is made via the standard Corporation Tax return (Form CT1).
By fulfilling this requirement, companies demonstrate compliance with Irish tax law and facilitate the processing of their R&D tax credit claims. The pre-filing notification helps Revenue plan for potential audits or reviews and ensures that companies are aware of their obligations in relation to R&D tax incentives.
When and How to Submit the Form
The pre-filing notification must be completed and submitted exclusively through the MyEnquiries portal, Ireland’s secure online platform for Revenue communications. Companies are advised to submit this form at least 90 days before they plan to make their formal R&D tax credit claim. Timely submission is crucial to avoid delays in processing and to ensure compliance with legal requirements.
Information Required on the Form
Section 1: Company Details and R&D Expenditure
- Corporation Tax Reference Number: The unique identifier assigned to the company by Revenue.
- Company Name and Address: Including the Eircode for precise location.
- Accounting Period: The start and end dates of the period for which the R&D claim is being prepared.
- Number of Employees Conducting R&D Activities: To gauge the scale of R&D operations.
- Number of R&D Projects: To provide an overview of active research initiatives.
- Expenditure Details: The total amount spent on R&D activities during the period, including any grants or external assistance received.
Section 2: Description of R&D Activities
Companies are required to provide a detailed description of the qualifying R&D activities undertaken during the specified accounting period. This description should include the nature of the projects, objectives, and any innovative aspects that qualify for the tax credit.
Section 3: Additional Information
This section allows companies to include any other relevant information or explanations that may assist Revenue in understanding the scope and nature of the R&D activities. Revenue may request further details or documentation if deemed necessary for the review process.
Declaration and Submission
The form must be signed by an authorized representative of the company, affirming that all information provided is accurate and complete to the best of their knowledge. The declaration confirms the company's intent to claim the R&D tax credit on Form CT1 within 12 months of the end of the relevant accounting period.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Failure to submit the pre-filing notification within the stipulated timeframe may result in delays or complications in processing the subsequent tax credit claim. Therefore, companies should ensure early preparation and submission of the form, aligning with their overall tax planning and compliance obligations.
Points of Attention and Practical Tips
- Timely Submission: Submit the pre-filing notification at least 90 days before the claim to avoid procedural issues.
- Accurate and Detailed Information: Provide comprehensive descriptions of R&D activities and expenditure to facilitate smooth processing.
- Use of MyEnquiries Platform: Ensure access to the portal and familiarity with its submission procedures.
- Record Keeping: Maintain detailed records of R&D projects, expenditure, and correspondence with Revenue for audit purposes.
Conclusion
The Research and Development Corporation Tax Credit Pre-filing Notification Form is a vital step for Irish companies planning to benefit from R&D tax incentives. By understanding the requirements and adhering to the submission deadlines, businesses can streamline their claim process, ensure compliance, and maximize their eligible tax credits. For further guidance, companies should consult the official Revenue Commissioners resources or seek professional tax advice.