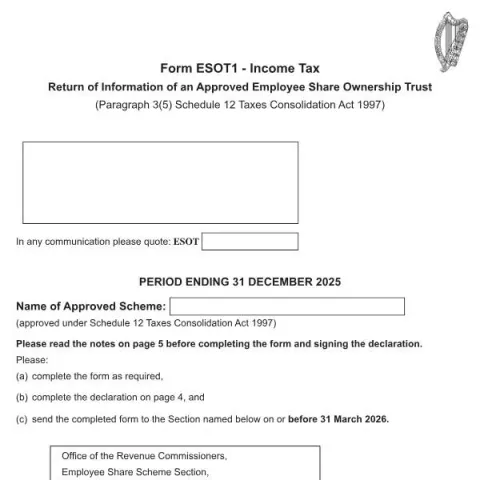
Understanding the ESOT1 Income Tax Return Form in Ireland
The Form ESOT1 is an official document issued by the Office of the Revenue Commissioners in Ireland. It is specifically designed for the reporting of information related to approved Employee Share Ownership Trusts (ESOTs) under Paragraph 3(5) of Schedule 12 of the Taxes Consolidation Act 1997. This form plays a crucial role for trustees managing such schemes, ensuring compliance with Irish tax regulations and providing transparency to the tax authorities.
What is the Purpose of the ESOT1 Form?
The ESOT1 form serves as a formal declaration and detailed report of the activities and financial movements within an approved employee share ownership scheme over a specified period, ending on 31 December of the relevant year. It is mandatory for trustees of approved ESOTs to submit this return by 31 March of the following year. The primary goal is to provide the Revenue Commissioners with comprehensive information about the scheme’s funds, share acquisitions, disposals, and other relevant transactions.
When Should the ESOT1 Form Be Used?
This form is applicable exclusively to schemes that have received approval under Schedule 12 of the Taxes Consolidation Act 1997. Trustees should complete the ESOT1 when reporting the scheme's activities for the calendar year ending 31 December. It is essential to submit the form annually to maintain compliance and avoid penalties for late or inaccurate reporting.
Key Sections and Data Requirements
1. Trustees Funds
This section requires trustees to declare the total funds received during the reporting period, along with a detailed breakdown of the sources, such as:
- Company contributions
- Deposit interest
- Borrowings
- Dividends
- Other sources (to be described)
Further, trustees must specify how these funds were utilized, including the amount spent on acquiring shares and other expenses incurred.
2. Acquisition and Sale of Shares
Trustees must detail the dates when shares were acquired, their market values at acquisition, and the number of shares purchased. Similarly, any sales of shares or securities must be reported with dates, sale values, and, where applicable, capital gains tax computations.
3. Share Transactions and Beneficiary Transfers
The form requests information about:
- Shares pledged as security
- Transfers or sales, including transfers upon death of beneficiaries
- Details of beneficiaries involved in transfers, including PPSN and transfer dates
4. Scheme Reorganizations and Amendments
Any reorganization, amalgamation, or alterations to the scheme since approval must be disclosed with relevant dates, market values, and securities involved.
Declaration and Submission
The form concludes with a declaration signed by the trustee, affirming that all information provided is accurate and complete. The completed ESOT1 must be sent to:
Office of the Revenue Commissioners,
Employee Share Scheme Section,
Personal Taxes Branch 1,
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
14/15 Upper O’Connell Street, Dublin 1,
D01 YT32
Failure to submit the form on time or providing incorrect information can lead to penalties under Irish tax law. Therefore, trustees should ensure careful completion and review of all sections before submission.
Points of Attention for Trustees
- Ensure all financial figures are accurately recorded, especially the market values at acquisition and sale dates.
- Keep detailed records of all transactions, including transfers, pledges, and reorganizations, to facilitate accurate reporting.
- Submit the form by the deadline to avoid penalties, and retain copies of the submitted return for record-keeping.
- If additional space is needed, supply information on a separate sheet, clearly referencing the relevant section.
In summary, the ESOT1 form is a vital compliance tool for trustees of approved employee share schemes in Ireland. Proper understanding and diligent completion ensure adherence to tax obligations and contribute to transparent scheme management.