Understanding the VAT 90 Claim Form for Gold Refunds in Ireland
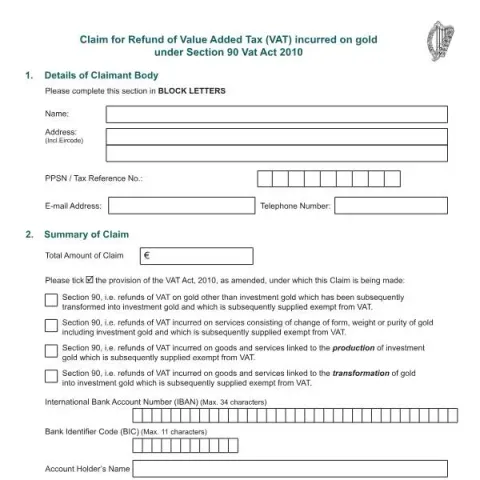
The VAT 90 form is an official document issued by the Revenue Commissioners of Ireland, designed for entities wishing to claim a refund of Value Added Tax (VAT) incurred on gold transactions under Section 90 of the VAT Act 2010. This form is essential for businesses involved in the purchase, transformation, or supply of gold that qualifies for VAT refunds, particularly in cases where the gold is subsequently supplied as exempt investment gold.
Purpose of the VAT 90 Form
The primary purpose of this form is to enable claimants to recover VAT paid on specific gold-related activities. These include:
- Purchases of gold that are later transformed into investment gold.
- Services involving the change of form, weight, or purity of gold.
- Goods and services linked to the production of investment gold.
- Transformation of gold into investment gold that is supplied exempt from VAT.
Claimants must complete this form accurately to ensure their VAT refunds are processed smoothly by the Revenue Commissioners.
Who Should Complete the VAT 90 Form?
This form is intended for businesses or individuals who have incurred VAT on gold transactions falling under the scope of Section 90 of the VAT Act 2010. Typically, these include:
- Gold traders and refiners involved in the transformation of gold into investment gold.
- Manufacturers or service providers performing transformations on gold.
- Importers of gold into Ireland who seek to recover VAT paid on importation and transformation services.
It is crucial that the claimant is eligible under the VAT legislation, meaning they are not registered for VAT or are not entitled to VAT refunds under other provisions, and that all details provided are truthful and complete.
How to Complete the VAT 90 Form
Section 1: Details of the Claimant
Provide full details in BLOCK LETTERS, including:
- Name and address (including Eircode)
- PPSN or tax reference number
- Email address
- Telephone number
Section 2: Summary of the Claim
Specify the total amount of VAT being claimed in euros (€). Indicate the relevant provision under Section 90 of the VAT Act 2010 by ticking the appropriate box, such as VAT on gold purchase, transformation services, or supply of investment gold.
Section 3: Declaration
The claimant must declare the accuracy of the information provided, affirming that they are not registered for VAT (or that registration is not required), and that they are not claiming VAT under any other provision. The declaration must be signed and dated, with authority to sign if applicable.
Section 4: Supporting Documentation
Ensure all relevant original invoices, import documents, and transformation service receipts are attached. These documents should clearly show details such as date, description, VAT amount, supplier’s details, and the nature of the transaction. Photocopies are acceptable if originals are to be returned.
Providing Details of the Transaction
The form requires detailed information about each transaction:
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
- Gold Purchase: including supplier details, purchase date, description, and VAT paid.
- Transformation Services: details of the transformer, services provided, and costs.
- Supply of Investment Gold: recipient details, description, and associated costs.
Submitting the VAT 90 Claim
Claims must be submitted within four years from the end of the taxable period in which the transaction occurred. The taxable periods are divided into bi-monthly segments, such as January/February, March/April, and so on.
Before submission, verify that all sections are completed, signatures are in place, and supporting documents are attached. The claim can be lodged via the Revenue’s online services or by mailing the completed form to the appropriate Revenue office.
Important Considerations and Common Errors
- Ensure all invoices are legible, dated, and include VAT details and supplier information.
- Double-check that the claim falls within the four-year time limit.
- Avoid submitting incomplete forms or missing supporting documentation, which can delay processing.
- Confirm that the declaration is signed and accurate to avoid penalties for false statements.
By carefully completing the VAT 90 form and attaching all necessary documents, claimants can efficiently recover VAT paid on eligible gold transactions, supporting their business operations and compliance with Irish VAT legislation.