When Income Tax Deduction Creates a Paper Trail: Understanding the R185 Certificate
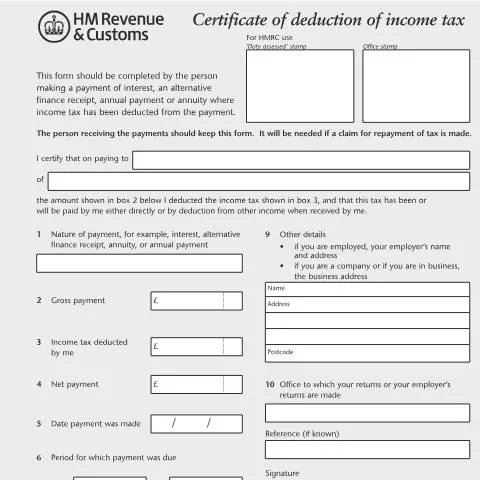
In the complex landscape of UK tax deductions, certain payments trigger specific documentation requirements that bridge the gap between payer and recipient. The R185 certificate represents one such crucial document, serving as formal evidence when income tax has been deducted from interest payments, annuities, or alternative finance receipts. This certificate becomes particularly significant when individuals or entities need to demonstrate legitimate tax deductions to HMRC or when pursuing tax repayment claims.
The R185 system operates on a straightforward principle: when someone makes a payment and deducts income tax from it, they must provide the recipient with documented proof of this deduction. This seemingly simple process carries substantial implications for both parties involved, creating a verifiable chain of accountability that HMRC can trace and recipients can rely upon for their own tax affairs.
The Mechanics of Tax Deduction Documentation
The R185 certificate captures essential details about the deduction process, creating a comprehensive record that serves multiple administrative purposes. When completed properly, this document establishes the gross payment amount, the specific tax deducted, and the resulting net payment received by the beneficiary.
The form requires precise information about the nature of the payment, whether it constitutes interest on a loan, an alternative finance receipt under Islamic banking principles, an annuity payment, or another form of annual payment. Each category carries different implications for how the deduction should be calculated and reported, making accurate classification essential.
| Payment Type | Common Scenarios | Deduction Basis |
|---|---|---|
| Interest payments | Private loans, trust distributions | Basic rate income tax |
| Alternative finance receipts | Islamic banking arrangements | Equivalent to interest treatment |
| Annuity payments | Pension distributions, insurance payouts | Based on income portion |
| Annual payments | Covenant payments, maintenance | Varies by arrangement |
The certificate must specify the period for which the payment was due, distinguishing between the actual payment date and the period it covers. This temporal precision becomes crucial when recipients need to allocate income to specific tax years or when HMRC investigates the timing of deductions.
Who Bears Responsibility for Issuing R185 Certificates
The obligation to complete and provide an R185 certificate falls squarely on the person or entity making the payment and deducting tax. This responsibility cannot be delegated to the recipient, though it may be handled by authorised representatives such as company secretaries, cashiers, or professional advisers acting on behalf of the payer.
Individuals managing trust distributions face particular obligations in this regard. When a trust makes payments to beneficiaries and deducts income tax, the trustees or their appointed administrators must ensure each recipient receives appropriate documentation. Personal representatives of estates carry similar responsibilities when distributing assets that generate taxable income.
Companies making interest payments on loans or bonds must issue R185 certificates to their creditors, while individuals who have arranged private lending agreements and deduct tax from interest payments are equally bound by these requirements. The certificate serves as proof that the payer has either already remitted the deducted tax to HMRC or will do so through their regular tax obligations.
Professional Representatives and Delegation
When professional advisers handle payment processes on behalf of clients, they may sign R185 certificates, but must clearly indicate their representative capacity. Accountants managing trust affairs, solicitors handling estate distributions, or company secretaries processing interest payments can all fulfil this function, provided they specify their role and relationship to the actual payer.
The signature section requires particular attention to this distinction. Simply signing as a representative without clarification could create confusion about who bears ultimate responsibility for the tax deduction and its proper remittance to HMRC.
Critical Information Requirements and Accuracy Standards
The R185 certificate demands specific information that must align with the payer's tax records and HMRC submissions. The payer's details section requires not just name and address, but also relevant reference numbers and the identity of the HMRC office handling their tax affairs.
For employed individuals, the certificate must include employer details, reflecting the reality that PAYE obligations may interact with the deduction process. Business operators must provide their trading address, while companies need to specify their registered office details. This information enables HMRC to cross-reference the certificate with existing taxpayer records.
The gross payment calculation represents perhaps the most critical element requiring accuracy. This figure must reflect the full amount before any tax deduction, calculated according to the applicable rates and thresholds in force at the time of payment. Recipients depend on this accuracy when completing their own Self Assessment returns or when claiming tax repayments.
Date Precision and Period Allocation
The certificate requires multiple date entries that serve different purposes in the tax system. The payment date determines which tax year the transaction falls into for both parties, while the period covered may span multiple months or even tax years for ongoing arrangements like annuities or regular interest payments.
When payments cover periods that straddle the 5 April tax year boundary, particular care is needed to ensure proper allocation. Recipients may need separate certificates for each tax year affected, or clear notation about how the payment should be divided between years.
The Recipient's Perspective: Safeguarding and Utilisation
For those receiving payments covered by R185 certificates, these documents serve as essential evidence for various tax-related processes. The certificate validates that tax has been deducted at source, potentially supporting claims for tax repayments when the recipient's actual tax liability falls below the amount deducted.
Individuals whose total income places them below the personal allowance threshold, or who qualify for reduced tax rates due to age allowances or other reliefs, may find R185 certificates crucial for recovering overpaid tax. The certificate provides HMRC with the documentation needed to verify deduction claims and process repayments efficiently.
Trust beneficiaries often encounter R185 certificates when receiving distributions that have been subject to tax deduction at the trust level. These certificates enable beneficiaries to claim credit for tax already paid on their behalf, preventing double taxation and ensuring their final tax liability reflects their personal circumstances rather than the trust's higher rates.
Integration with Self Assessment Returns
When completing Self Assessment returns, recipients must report the gross income shown on R185 certificates and claim credit for the tax deducted. The certificate provides the precise figures needed for the relevant sections of the SA100 return, ensuring consistency between the recipient's declaration and the payer's records.
The timing of payments covered by R185 certificates can affect which tax year they should be reported in. Recipients need to pay particular attention to the payment dates and periods shown on certificates to ensure correct allocation in their tax returns.
Handling Discrepancies and Administrative Challenges
When recipients identify errors in R185 certificates, the resolution process requires cooperation between both parties and potentially HMRC involvement. Common discrepancies include incorrect gross amounts, wrong tax calculations, or inaccurate date entries that could affect tax year allocation.
The payer bears responsibility for issuing corrected certificates when errors are identified. However, this process may require them to amend their own tax records and potentially adjust previous submissions to HMRC. Recipients should raise concerns promptly to allow sufficient time for corrections before Self Assessment deadlines.
Lost certificates present particular challenges, especially when recipients need them for tax repayment claims or Self Assessment completion. While payers can issue replacement certificates, they must ensure consistency with their original records and any submissions already made to HMRC.
HMRC Intervention and Verification
HMRC may request sight of R185 certificates during enquiries into either party's tax affairs. The certificates serve as supporting evidence for deductions claimed by payers and income declared by recipients. Discrepancies between certificates and tax return entries often trigger further investigation.
When certificates are missing or disputed, HMRC may accept alternative evidence of tax deductions, but this typically involves more extensive verification processes and potential delays in resolving tax affairs.
Practical Applications Across Different Financial Arrangements
The R185 certificate system accommodates various financial relationships where tax deduction obligations arise. Private lending arrangements between individuals often generate the need for these certificates, particularly when the lender operates under Self Assessment and must account for tax on interest received.
Estate administration frequently involves R185 certificates when assets generate income during the administration period. Personal representatives may need to deduct tax from distributions to beneficiaries, creating documentation obligations that extend beyond the basic estate accounts.
Alternative finance arrangements present unique challenges for R185 completion, as these structures must comply with both Islamic finance principles and UK tax law. The certificates help demonstrate that profit distributions from these arrangements receive equivalent treatment to conventional interest payments.
Corporate and Trust Environments
Companies issuing loan stock or making interest payments on borrowings use R185 certificates to document their tax deduction obligations. This process integrates with their corporation tax computations and helps ensure proper coordination between different aspects of their tax compliance.
Discretionary trusts making distributions that exceed beneficiaries' available income tax bands must issue R185 certificates to document the tax credit being passed along. This mechanism prevents the double taxation that would otherwise occur when trust income is distributed to beneficiaries.
Long-term Record Keeping and Compliance Considerations
Both payers and recipients should maintain R185 certificates for extended periods, as HMRC's enquiry powers can extend several years beyond the initial tax year. The certificates may become relevant not only for routine tax return preparation but also for responding to compliance checks or inheritance tax investigations.
The integration between R185 certificates and broader tax compliance extends beyond the immediate transaction. These documents contribute to the audit trail that HMRC uses to verify the integrity of the tax system, making their accuracy and retention important for maintaining public confidence in tax administration.
For recipients, R185 certificates represent more than simple receipts; they constitute evidence of tax credits that may become valuable in changing circumstances. Individuals whose income patterns vary between years may find previously issued certificates relevant for claims spanning multiple tax years, particularly when seeking repayments or responding to HMRC enquiries about their tax history.
Understanding Tax Deduction Scenarios and Rate Applications
The R185 certificate serves multiple functions depending on the specific circumstances of tax deduction from trust or estate income. Understanding when different tax rates apply is crucial for both trustees and beneficiaries navigating their tax obligations.
For discretionary trusts, the standard rate structure involves deductions at 45% on income above the standard rate band, which currently stands at £1,000 for most trusts. This higher rate reflects the tax treatment of accumulated income within discretionary structures. When trustees make distributions to beneficiaries, the R185 documents the tax already paid, enabling beneficiaries to claim appropriate relief based on their personal tax circumstances.
Interest in possession trusts follow different deduction patterns. Here, income typically flows through to beneficiaries with basic rate tax deducted at source. The R185 in these cases shows deductions at 20% for dividend income and savings income, though this can vary depending on the trust's specific terms and the nature of underlying investments.
Estate administration presents particular complexities during the administration period, typically the first tax year following death. Income arising during this period may be subject to basic rate deductions, with the R185 providing essential documentation for final estate accounts and beneficiary distributions. Personal representatives must carefully track these deductions, as they directly impact the net estate value and individual beneficiary tax liabilities.
Special consideration applies to vulnerable beneficiary trusts, where different tax treatment may apply under specific circumstances. These trusts, designed for disabled individuals or bereaved minors, can elect for alternative tax treatment that may affect the deduction rates shown on R185 certificates.
Foreign element complications arise when trusts hold overseas assets or when beneficiaries are non-UK residents. Double taxation agreements may influence the effective tax rates, and the R185 must accurately reflect UK tax deducted whilst considering potential foreign tax credit implications.
Compliance Obligations and Record-Keeping Requirements
Trustees and personal representatives face stringent compliance obligations regarding R185 certificate management, extending far beyond simple issuance. These responsibilities form part of broader fiduciary duties and carry significant legal implications for proper estate and trust administration.
Annual compliance cycles require systematic approaches to certificate preparation and distribution. Trustees must maintain comprehensive records of all income received, tax deducted, and distributions made throughout each tax year. This documentation supports not only R185 preparation but also trust tax return completion and potential HMRC enquiries.
Digital record-keeping has become increasingly important, particularly for complex trust structures with multiple beneficiaries or varied income sources. Trustees should maintain electronic copies of all R185 certificates issued, cross-referenced with underlying income records and distribution decisions. This systematic approach proves invaluable during compliance reviews or when addressing beneficiary queries years after initial distribution.
Professional adviser coordination represents another crucial compliance element. Where trusts engage accountants, solicitors, or specialist trust administrators, clear protocols must establish who bears responsibility for R185 preparation and distribution. Written agreements should specify these arrangements, particularly where multiple professionals are involved in trust administration.
Penalty implications for non-compliance can be severe. HMRC powers include penalties for late or incorrect certificate issuance, particularly where this affects beneficiary tax positions. Trustees may face personal liability for compliance failures, making proper R185 management essential for fiduciary protection.
Anti-money laundering considerations increasingly impact trust administration, including R185 certificate processes. Trustees must verify beneficiary identities before issuing certificates, maintaining appropriate due diligence records. This requirement can complicate certificate distribution, particularly for trusts with overseas beneficiaries or complex beneficial structures.
Data protection compliance under UK GDPR affects how trustees handle beneficiary information contained in R185 certificates. Proper data handling procedures must govern certificate preparation, distribution, and storage, with particular attention to electronic transmission security and retention period management.
Practical Challenges and Resolution Strategies
Real-world R185 certificate management presents numerous practical challenges that require systematic approaches and forward planning. These operational difficulties often emerge from the intersection of complex tax rules with practical administration realities.
Missing or incomplete beneficiary information represents one of the most common challenges trustees face. When beneficiaries change addresses without notification, or when trust deeds contain outdated contact details, certificate distribution becomes problematic. Trustees should establish annual contact verification procedures, requesting updated details from all beneficiaries at consistent intervals. Where beneficiaries cannot be located, trustees must document reasonable efforts to trace them, potentially involving professional tracing services for significant distributions.
Disputed distribution calculations frequently arise, particularly in discretionary trusts where beneficiaries may question trustee decisions or income allocations. The R185 certificate becomes crucial evidence in such disputes, making accurate preparation essential. Trustees should maintain detailed calculations supporting each certificate, including contemporaneous records of decision-making processes and income attribution methodologies.
Technical amendments and corrections present ongoing challenges when initial certificates contain errors or when subsequent information emerges affecting previous distributions. HMRC does not prescribe a specific correction process for R185 certificates, leaving trustees to develop appropriate procedures. Best practice involves issuing corrected certificates clearly marked as amendments, with accompanying explanatory letters detailing changes made and reasons for correction.
Multi-year distribution complications arise when trustees make distributions spanning multiple tax years or when income attribution becomes complex due to timing differences. Careful date management becomes crucial, ensuring certificates reflect the correct tax year for both income arising and distributions made. This requires sophisticated record-keeping systems capable of tracking income and deductions across multiple periods.
Professional liability considerations affect how trustees approach R185 certificate management, particularly where errors could impact beneficiary tax positions significantly. Many trustees secure appropriate professional indemnity insurance covering certificate preparation errors, whilst others engage specialist administrators to handle technical compliance aspects.
Technology integration challenges emerge as trustees seek to modernise certificate preparation and distribution processes. While electronic systems can improve efficiency and accuracy, they must comply with legal requirements for document authenticity and security. Trustees should evaluate digital solutions carefully, ensuring they meet regulatory standards whilst providing practical benefits for administration efficiency.
Cross-border complications multiply when trusts operate across multiple jurisdictions or serve non-UK resident beneficiaries. Different countries may not recognise R185 certificates for tax credit purposes, requiring additional documentation or alternative approaches to evidence UK tax deducted. Professional advice becomes essential for navigating these international elements effectively.