When Property Charges Require Future Lending Commitments
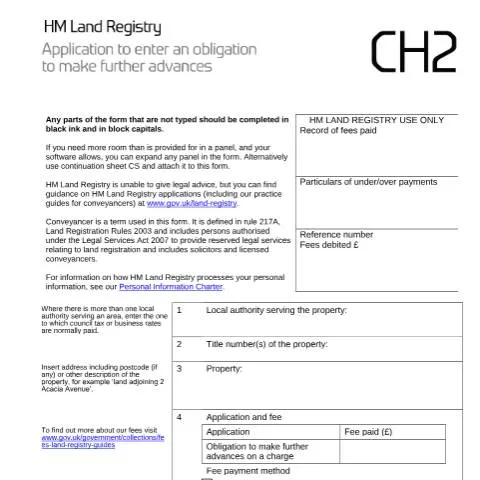
Property transactions involving legal charges don't always end with the initial mortgage advance. Many lending arrangements include provisions requiring the lender to provide additional funds later—perhaps for home improvements, business expansion, or refinancing existing debts. Form CH2 serves a crucial but often overlooked function: it creates an official record at HM Land Registry confirming that such an obligation exists, protecting both lender and borrower when future advances become necessary.
The obligation for further advances represents a binding commitment that goes beyond the original charge. Without proper registration through CH2, disputes can arise when borrowers attempt to access promised additional funding, or when competing creditors challenge the priority of later advances. This form establishes legal certainty in what could otherwise become complex priority battles between multiple creditors.
Understanding the Legal Framework Behind Further Advance Obligations
Under the Land Registration Act 2002, legal charges must be properly documented to maintain their priority position. When a charge contains an obligation to make further advances, this creates what's known as a continuing security arrangement. The original charge document may specify circumstances where additional lending must occur—such as when property values increase, or when the borrower meets certain financial criteria.
However, the mere existence of such clauses in the charge deed doesn't automatically notify third parties or subsequent creditors. Form CH2 bridges this gap by placing a clear note on the register, ensuring that anyone searching the title will discover the potential for future advances under the existing charge.
Priority Protection Mechanisms
The registration creates what's termed tacking protection—ensuring that future advances under the obligation rank equally with the original charge, rather than being subordinated to intervening interests. This proves particularly valuable when:
- Property values fluctuate significantly between the original charge and subsequent advances
- Multiple creditors hold interests in the same property
- Insolvency proceedings might affect the borrower's estate
- Family disputes arise over property ownership and debt priorities
Identifying When CH2 Application Becomes Necessary
Not every legal charge requires a CH2 application. The obligation must be specifically documented within the charge terms, creating a legal duty rather than merely a discretionary power to lend further. Common scenarios triggering CH2 applications include:
| Lending Scenario | Typical Obligation Terms | CH2 Required? |
|---|---|---|
| Development Finance | Staged release based on construction progress | Yes - if legally binding stages specified |
| Business Credit Line | Maximum facility with drawdown rights | Yes - if borrower has guaranteed access |
| Equity Release | Annual increases tied to property valuation | Usually yes - if automatic increases apply |
| Flexible Mortgage | Re-borrowing up to original limit | Sometimes - depends on specific terms |
Distinguishing Obligations from Discretionary Powers
The critical distinction lies between shall advance and may advance provisions. Where the charge states the lender "shall" or "will" make further advances upon specific conditions being met, an obligation exists. Conversely, provisions giving lenders discretion to advance further funds don't create binding obligations requiring CH2 registration.
Navigating the Application Process: Panel-by-Panel Requirements
Form CH2's structure reflects HM Land Registry's systematic approach to recording complex security arrangements. Each panel serves specific evidentiary and administrative purposes that applicants must understand to avoid delays or rejections.
Property Identification and Administrative Details
Panels 1-3 establish the foundational information. The local authority requirement in panel 1 often catches applicants off-guard—this refers to the council responsible for council tax or business rates, which may differ from other administrative boundaries in areas with multiple local authorities.
Title number accuracy proves crucial in panel 2, particularly for properties with multiple titles or where recent dealings have resulted in title splits or mergers. Cross-referencing with recent official copies prevents applications being rejected for targeting incorrect title numbers.
Charge Identification Complexities
Panel 5 addresses a common complication: multiple charges of the same date to the same lender. This situation frequently arises in commercial transactions where borrowers grant several charges simultaneously—perhaps one for working capital, another for equipment finance. The form requires clear identification through numbers or other distinguishing features to prevent confusion about which charge contains the further advance obligation.
When completing panel 5, reference the exact wording from the charge deed rather than paraphrasing. This ensures the register entry accurately reflects the legal commitment's scope and conditions.
Professional Representation and Signature Requirements
The application process involves strict requirements about who may sign and submit the form. Understanding these rules prevents delays and ensures proper legal representation throughout the process.
Conveyancer Definition and Scope
Form CH2 uses "conveyancer" as defined in rule 217A of the Land Registration Rules 2003, encompassing persons authorised under the Legal Services Act 2007 to provide reserved legal services. This includes solicitors and licensed conveyancers but excludes other property professionals who might handle related aspects of the transaction.
When a conveyancer acts for the applicant, they must sign panel 9. This creates professional responsibility for the application's accuracy and completeness. However, if no conveyancer is involved, each applicant must personally sign—a requirement that can complicate applications involving multiple lenders or corporate applicants.
Corporate Applicant Considerations
Corporate lenders face additional complexities when signing without conveyancer representation. Company officers must have appropriate authority to bind the corporation, and evidence of this authority may be required. For overseas corporate applicants, additional documentation proving corporate existence and signatory authority often becomes necessary.
Fee Structure and Payment Processing
HM Land Registry operates a cost-recovery fee structure for CH2 applications, with fees varying based on the property value and complexity of the obligation being registered. Payment methods include traditional cheques payable to 'Land Registry' and direct debit arrangements for professional customers with established accounts.
Professional customers often benefit from key number arrangements, which streamline processing and enable direct debit payment. However, these arrangements require prior agreement with HM Land Registry and typically involve minimum transaction volumes or deposit requirements.
Fee Calculation Considerations
Unlike simple charge registrations, CH2 applications may involve complex fee calculations when the further advance obligation relates to significant future sums. The current fee structure can be verified through the government's official fee guides, though applicants should note that fees are subject to periodic revision.
Post-Application Processing and Register Entries
Once submitted, CH2 applications undergo HM Land Registry's standard examination process, typically involving verification of the charge terms and confirmation that a genuine obligation exists. The resulting register entry creates a permanent record visible to all future searchers.
Register Entry Format and Content
Successful CH2 applications result in a note being added to the charges register, typically reading: "The charge dated [date] contains an obligation to make further advances". This concise entry alerts future parties to the existence of the obligation without detailing its specific terms, which remain documented in the original charge deed.
The entry remains on the register until the charge itself is discharged, ensuring long-term visibility of the further advance obligation. This permanence proves particularly valuable in complex commercial arrangements where ownership or lending arrangements may change over time.
Requisitions and Common Issues
HM Land Registry may raise requisitions when the charge terms don't clearly establish an obligation, when multiple interpretations are possible, or when the application conflicts with existing register entries. Common requisition subjects include:
- Ambiguous charge wording that could be interpreted as discretionary rather than obligatory
- Inconsistencies between the application and the registered charge terms
- Missing evidence of corporate authority for company applicants
- Incomplete or unclear identification of specific charges in multi-charge scenarios
Strategic Implications for Property Transactions
CH2 registration creates lasting implications extending beyond the immediate transaction. For borrowers, it provides security that promised funding remains legally enforceable. For lenders, it protects the priority position of future advances, potentially worth significant sums over the charge's lifetime.
However, the registration also alerts potential purchasers and subsequent lenders to existing commitments that could affect the property's marketability. This transparency serves the public interest while ensuring all parties understand the full extent of existing financial commitments.
Impact on Future Dealings
Properties with registered further advance obligations may require additional considerations during subsequent transactions. Purchasers' solicitors must investigate whether outstanding obligations exist and how they might affect the proposed transaction. Similarly, new lenders must understand how existing obligations might rank against their proposed security.
The CH2 register entry serves as an early warning system, prompting proper investigation of the underlying arrangements and ensuring informed decision-making by all transaction parties. This systematic approach reduces the risk of priority disputes and promotes confidence in property-based lending throughout England and Wales.
Practical Implementation and Documentation Requirements
The practical implementation of obligation for further advances clauses requires meticulous attention to documentation standards and procedural compliance. When a lender commits to providing additional funds under a CH2 charge, the original charge document must contain sufficiently precise terms to satisfy both legal requirements and operational needs.
The charge instrument should specify the maximum aggregate amount that may be advanced, including both the initial loan and any subsequent advances. This figure becomes crucial for priority purposes, as it determines the extent of the charge's protection against later encumbrancers. For instance, if a charge secures "all monies advanced or to be advanced up to £500,000", any advance within this limit maintains the original priority date, provided other conditions are met.
Timing requirements present particular challenges in practice. The obligation must exist at the time of registration, not merely at the time of each subsequent advance. This means lenders cannot retrospectively create binding commitments to justify priority claims. The charge document must demonstrate a present legal obligation to advance funds in specified circumstances, whether immediately or upon satisfaction of stated conditions.
Documentation of each advance requires careful record-keeping to establish the connection between the original obligation and the actual disbursement. Lenders typically maintain advance registers showing dates, amounts, purposes, and references to the underlying obligation. This documentation becomes essential if priority disputes arise, as the burden of proof lies with the party claiming the benefit of the earlier registration date.
The interplay with existing security arrangements adds complexity to implementation. Where multiple charges exist over the same property, the obligation for further advances must be considered alongside any restrictions or prohibitions in earlier charges. Some first charges contain clauses preventing the creation of further obligations without consent, which could invalidate subsequent arrangements.
Professional advisers must also consider the impact of corporate law requirements. For companies, the obligation to make further advances may constitute a financial assistance arrangement requiring compliance with Companies Act 2006 provisions. Directors must ensure adequate corporate authority exists for both the initial commitment and each subsequent advance, particularly where the advances exceed original board authorisations.
Strategic Considerations for Different Stakeholder Groups
The strategic implications of obligation for further advances vary significantly depending on the stakeholder's position and objectives. For commercial lenders, these arrangements offer powerful tools for maintaining competitive advantages while managing risk exposure across extended lending relationships.
Development financiers particularly value these structures when funding phased construction projects. A committed facility secured by a single charge provides certainty for both funding availability and security priority throughout the development timeline. This approach eliminates the risk of intervening charges affecting later phase funding, while giving developers confidence in financing continuity. However, lenders must carefully structure drawdown conditions to maintain control over project progression and risk exposure.
Corporate borrowers often seek these arrangements to support working capital facilities or acquisition programmes. The ability to draw additional funds under an existing charge avoids repeated security documentation and registration processes, reducing both costs and administrative burden. For borrowers with multiple subsidiaries, group facilities secured by obligations for further advances can provide flexible funding across the corporate structure while maintaining centralised security arrangements.
Property investors utilise these structures for portfolio expansion strategies. An initial acquisition funded through a charge containing further advance obligations allows subsequent property purchases to benefit from the same security priority. This proves particularly valuable in rapidly appreciating markets where securing early priority positions becomes crucial for long-term financing strategies.
From a risk management perspective, lenders must balance the benefits of committed facilities against potential exposure to deteriorating credit conditions. Unlike discretionary facilities, obligations for further advances create legal duties that cannot be easily avoided if borrower circumstances change. Sophisticated lenders incorporate material adverse change clauses, financial covenant requirements, and other protective mechanisms to maintain some control over advance decisions.
Insolvency practitioners encounter these arrangements frequently in corporate restructuring scenarios. The priority status of advances made under pre-existing obligations can significantly affect recovery prospects for other creditors. Understanding whether advances were truly obligatory or discretionary becomes crucial for challenging preferential payments or constructing creditor proposals.
For junior lenders and unsecured creditors, the existence of further advance obligations represents potential dilution of their recovery prospects. Due diligence processes must carefully examine existing charges for these commitments, as they may not be immediately apparent from standard security reviews. The contingent nature of these obligations makes them particularly difficult to assess and price into lending decisions.
Regulatory Framework and Compliance Obligations
The regulatory landscape surrounding obligations for further advances encompasses multiple oversight regimes, each imposing distinct compliance requirements on different market participants. Financial services regulation, consumer protection law, and corporate governance frameworks all intersect in this area, creating complex compliance matrices for lenders and borrowers.
Under the Financial Conduct Authority's regulatory framework, firms providing committed lending facilities must ensure appropriate governance around advance decisions, even where legal obligations exist. The FCA's Principles for Businesses require firms to treat customers fairly, which extends to how further advance obligations are structured and executed. This includes ensuring that advance terms remain appropriate for borrowers' circumstances and that any conditions precedent are reasonable and clearly communicated.
Consumer credit regulations add additional layers of complexity where further advances involve regulated agreements. The Consumer Credit Act 1974 and associated regulations may apply to each advance separately, potentially requiring individual credit assessments and disclosure documents. The interaction between pre-existing obligations and affordability requirements creates particular challenges, as lenders must balance legal commitments against regulatory duties to lend responsibly.
Data protection obligations under UK GDPR affect how lenders collect, process, and retain information related to further advance decisions. The legal basis for processing personal data may differ between the initial lending decision and subsequent advances, particularly where circumstances or purposes change over time. Lenders must maintain appropriate privacy notices and consent mechanisms throughout the facility lifetime.
Anti-money laundering requirements apply to each advance under an obligation, not just the initial lending decision. This creates ongoing due diligence obligations, particularly for facilities with extended drawdown periods or changing end-use purposes. The risk-based approach required under the Money Laundering, Terrorist Financing and Transfer of Funds Regulations 2017 must account for evolving customer and transaction risks across the facility lifecycle.
Corporate governance considerations affect how companies structure and manage further advance obligations. Directors' duties under the Companies Act 2006 extend to decisions about creating these obligations and subsequently fulfilling them. The duty to promote company success requires careful consideration of stakeholder interests, while the duty to exercise reasonable care, skill and diligence applies to both initial commitment decisions and ongoing advance management.
Tax implications create additional compliance requirements, particularly around interest deductibility and transfer pricing for group arrangements. HMRC's guidance on loan relationships and corporate finance transactions applies to further advances, potentially affecting the tax treatment of both interest payments and arrangement fees. The timing of tax recognition may differ from the legal obligation timing, creating planning opportunities and compliance challenges.
Prudential regulation through the Prudential Regulation Authority affects how banks and building societies account for further advance commitments in their capital and liquidity calculations. These off-balance-sheet commitments require specific regulatory capital allocation and may affect institutions' lending capacity for other opportunities. The interaction between accounting standards and regulatory requirements creates particular complexity around facility pricing and profitability assessment.