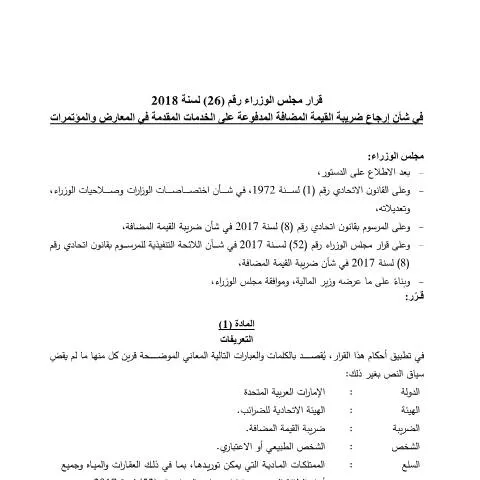
Understanding Cabinet Decision No (26) of 2018 on VAT Refunds for Exhibition and Conference Services in the UAE
The United Arab Emirates has established a comprehensive framework to facilitate the refund of Value Added Tax (VAT) paid on services provided during exhibitions and conferences. This guidance provides an overview of the key provisions of Cabinet Decision No (26) of 2018, focusing on its scope, eligibility criteria, and procedural considerations for businesses and individuals involved in such events.
Scope and Purpose of the Decision
Cabinet Decision No (26) of 2018 aims to promote the UAE as a global hub for exhibitions and conferences by offering mechanisms for VAT refunds on relevant services. It specifically addresses the circumstances under which VAT paid on services—such as venue rental, event management, catering, and technical support—can be reclaimed by eligible entities. The decision underscores the government's commitment to fostering a business-friendly environment while ensuring compliance with federal tax legislation.
Who is Eligible for VAT Refunds?
The regulation primarily targets foreign exhibitors, event organizers, and international visitors who incur VAT on services related to exhibitions and conferences held within the UAE. To qualify for a refund, applicants must meet specific criteria, including:
- Provision of valid documentation proving the payment of VAT on eligible services;
- Participation in an officially recognized exhibition or conference event conducted in accordance with UAE regulations;
- Compliance with the procedural requirements set forth by the Federal Tax Authority (FTA).
It is important to note that UAE residents and companies registered for VAT within the country are generally not eligible for refunds under this specific decision, as they are typically entitled to recover VAT through their regular tax filings.
Key Provisions and Refund Procedures
Application Process
Eligible applicants must submit a formal application through the designated portals of the Federal Tax Authority (FTA). The process involves uploading supporting documents, such as invoices, proof of payment, and event participation certificates, via the official online platform. The FTA emphasizes the importance of accurate and complete documentation to facilitate efficient processing.
Processing and Approval
Once the application is submitted, the FTA reviews the documentation to verify eligibility and compliance with legal requirements. The authority may request additional information or clarification during this phase. Upon approval, the VAT refund is processed and credited to the applicant’s designated account, typically within the stipulated timeframe set by the FTA’s operational guidelines.
Limitations and Conditions
The decision specifies certain limitations, including the types of services eligible for refunds and the maximum amounts recoverable. Refunds are only applicable to VAT paid directly related to the event, excluding any VAT embedded in other costs or expenses not directly linked to the exhibition or conference.
Legal References and Further Guidance
For detailed legal provisions, procedural specifics, and updates, stakeholders are advised to consult the official publications and resources provided by the Federal Tax Authority (FTA). The FTA’s digital platforms, including u.ae and the dedicated VAT portal, serve as primary sources for official notices, application procedures, and compliance guidelines related to VAT refunds under this decision.
In summary, Cabinet Decision No (26) of 2018 represents a strategic initiative to streamline VAT refunds for services provided during exhibitions and conferences, thereby enhancing the UAE’s appeal as a global event destination. Adhering to the outlined procedures and maintaining proper documentation are essential for beneficiaries seeking to benefit from this regulation.