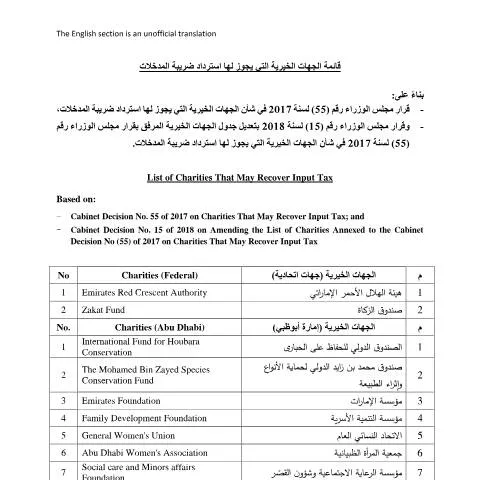
Understanding the Cabinet Decision No (55) of 2017 on Charities Eligible for Input Tax Refunds in the UAE
The United Arab Emirates has established a comprehensive legal framework governing the application of Value Added Tax (VAT) within its jurisdiction. Among the key regulations is the Cabinet Decision No (55) of 2017, which delineates the specific categories of charitable organizations that are eligible to claim an input tax refund. This guide aims to clarify the scope, eligibility criteria, and procedural considerations for charities seeking VAT refunds under this regulation, emphasizing the importance of compliance with federal tax legislation.
Scope and Purpose of the Cabinet Decision
The primary objective of Cabinet Decision No (55) of 2017 is to identify and regulate the circumstances under which charitable entities can recover VAT paid on their eligible expenses. It complements the broader UAE VAT framework by providing targeted provisions for charities, ensuring they are not unduly burdened by tax costs that are integral to their operations. The decision reflects the UAE’s commitment to supporting philanthropic activities while maintaining strict adherence to tax compliance standards.
This regulation applies to charities that operate within the UAE and are recognized as qualifying entities under the specified legal criteria. It aims to facilitate transparency and accountability in the VAT refund process, thereby encouraging compliance and fostering a supportive environment for charitable work.
Who Is Eligible for VAT Refunds?
Not all charities automatically qualify for input tax refunds. The regulation specifies particular categories and conditions that organizations must meet. Eligible charities typically include:
- Registered non-profit organizations operating in accordance with federal and emirate-level regulations.
- Entities engaged in activities that are deemed charitable, humanitarian, or social welfare-oriented.
- Organizations that maintain proper accounting records and are compliant with the UAE’s tax registration requirements.
It is essential for eligible charities to ensure their registration status and operational scope align with the criteria outlined in the legislation. Non-compliance with registration or operational standards may disqualify an organization from claiming input tax refunds.
Key Provisions and Requirements
Eligible Expenses
The regulation specifies that only VAT incurred on expenses directly related to charitable activities may be claimed. These include costs associated with program delivery, administrative operations, and other activities that serve the charitable purpose. Expenses outside this scope, such as purely commercial transactions, are generally excluded.
Documentation and Record-Keeping
Charities must maintain detailed records of all transactions, including VAT invoices, receipts, and proof of payment. Proper documentation is crucial for substantiating claims during audits or reviews by tax authorities. The UAE’s digital platforms facilitate the submission and verification of such records through the federal and emirate-level portals.
Application Process
Applicants are required to submit their refund claims via the relevant online portal, such as the Federal Tax Authority (FTA) portal or the specific emirate’s tax services platform. The process involves providing detailed information about eligible expenses, attaching supporting documentation, and ensuring compliance with all procedural requirements. The authorities review the submissions and process refunds accordingly, subject to verification.
References and Regulatory Oversight
The implementation and oversight of VAT refunds for charities are primarily managed by the UAE’s Federal Tax Authority (FTA). The FTA provides guidance, conducts audits, and enforces compliance with the applicable tax laws. For detailed legal provisions and procedural guidance, organizations should consult official publications and resources provided by the FTA and relevant emirate authorities.
Additionally, the legislation aligns with broader federal policies aimed at supporting social and humanitarian initiatives, emphasizing the UAE’s strategic commitment to fostering a robust charitable sector within a compliant tax environment.
Conclusion
Cabinet Decision No (55) of 2017 plays a vital role in clarifying the conditions under which charities can benefit from input tax refunds in the UAE. By establishing clear eligibility criteria and procedural standards, it ensures that charitable organizations operate transparently and in full compliance with federal tax laws. For charities seeking to optimize their VAT recovery efforts, understanding and adhering to these regulations is essential, and they should regularly consult official sources and authorities to stay updated on any amendments or procedural changes.