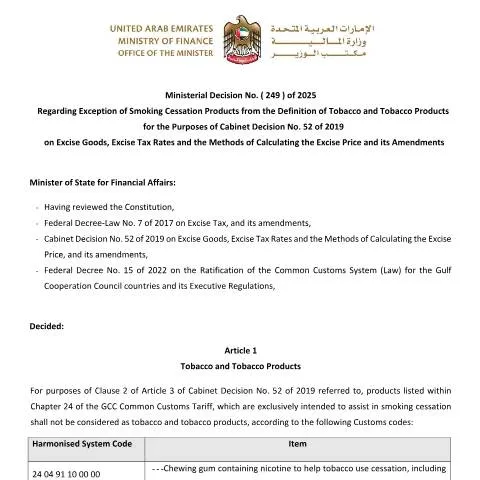
Overview of Ministerial Decision (249) of 2025 on Tobacco and Smoking Cessation Products
The United Arab Emirates (UAE) continues to refine its regulatory framework concerning tobacco and related products to ensure public health and fiscal compliance. The recent Ministerial Decision (249) of 2025, issued by the Ministry of Finance, introduces specific provisions regarding the classification and taxation of smoking cessation products. This decision aims to clarify the legal status of these products within the broader scope of tobacco legislation, facilitating compliance for businesses and consumers alike.
Scope and Purpose of the Decision
Ministerial Decision (249) of 2025 primarily addresses the categorization of smoking cessation products, such as nicotine replacement therapies (NRTs) and other similar items, which are intended to assist individuals in quitting tobacco use. The decision explicitly states that these products are to be excluded from the definition of tobacco and tobacco products within the UAE's tax legislation framework. The primary objective is to differentiate these products from traditional tobacco items, thereby affecting their taxation, importation, and sale procedures.
This differentiation reflects the UAE's commitment to public health initiatives aimed at reducing tobacco consumption, while also providing a clear legal pathway for the legal trade of cessation aids. The decision aligns with the broader legal and health policies of the country, emphasizing the importance of targeted regulation for products designed to promote health benefits.
Impacted Entities and Stakeholders
The decision impacts a range of stakeholders involved in the manufacturing, importation, distribution, and retail of smoking cessation products. This includes:
- Pharmaceutical companies producing nicotine replacement therapies and other cessation aids
- Importers and distributors handling these products into the UAE market
- Retailers and pharmacies selling smoking cessation products to consumers
- Regulatory authorities overseeing compliance with tax and health legislation
Importantly, the decision provides clarity for these entities regarding the tax treatment and legal classification of cessation products, streamlining their market entry and commercial activities.
Key Provisions and Implications
Exclusion from Tobacco Definition
The core provision of the decision is the formal exclusion of smoking cessation products from the legal definition of tobacco and tobacco products. This exemption means that such products are not subject to the same excise tax rates and import restrictions as traditional tobacco items.
Taxation and Customs Procedures
As a consequence, entities importing or selling cessation aids must adhere to the specific tax and customs procedures applicable to non-tobacco health products. This typically involves compliance with relevant customs declarations and ensuring proper documentation to reflect the exempt status of these products.
Regulatory Compliance
Manufacturers and suppliers are advised to maintain clear records demonstrating the nature and purpose of their products to avoid misclassification. The decision encourages transparency and compliance with the UAE's legal standards for health-related products.
Legal and Administrative References
For further guidance, stakeholders are encouraged to consult the relevant authorities, including the Ministry of Finance, which issued the decision, and the Federal Tax Authority (FTA), responsible for implementing and overseeing tax regulations. These bodies provide detailed instructions and support to ensure adherence to the new provisions.
Additionally, the decision aligns with the UAE's ongoing efforts to modernize its legal framework on health and taxation, reflecting the country's strategic priorities in public health and economic regulation.
Conclusion
Ministerial Decision (249) of 2025 marks a significant step in the UAE's regulatory approach to tobacco-related products. By explicitly excluding smoking cessation aids from the definition of tobacco and tobacco products, the decision facilitates a clearer legal environment for manufacturers, importers, and consumers of these health-focused products. Stakeholders are advised to stay informed of the detailed procedures and ensure compliance with the relevant authorities to benefit from this regulatory clarification and contribute to the UAE's public health objectives.