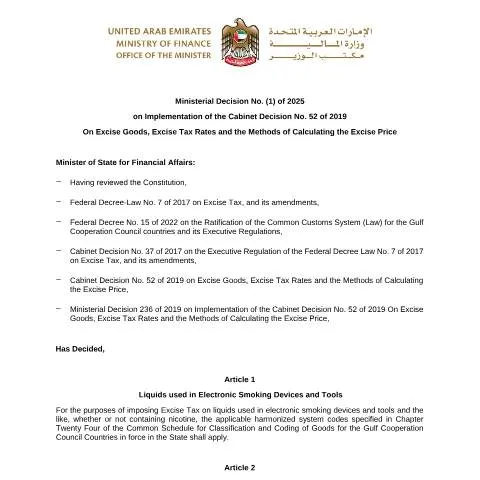
Overview of the Ministerial Decision Implementing CD 52 of 2019 and Its Amendments
The Ministerial Decision implementing Cabinet Decision (CD) 52 of 2019 and its subsequent amendments represents a significant legislative framework within the United Arab Emirates (UAE) tax landscape. This regulation aims to clarify and operationalize the provisions outlined in the original cabinet decision, thereby ensuring effective compliance, administration, and enforcement of tax policies across various sectors within the country.
Scope and Purpose of the Ministerial Decision
This Ministerial Decision is designed to provide detailed guidance on the implementation of the provisions set forth in CD 52 of 2019. It addresses key procedural aspects, administrative procedures, and compliance obligations for taxpayers and relevant authorities. The overarching goal is to establish a clear, consistent, and efficient framework that aligns with the UAE’s broader strategic objectives for tax regulation, transparency, and economic diversification.
Specifically, the decision delineates the roles and responsibilities of federal tax authorities, clarifies the mechanisms for tax registration, reporting, and payment, and sets forth the procedures for handling disputes and audits. It also incorporates updates introduced through amendments, ensuring that the legislative framework remains current and adaptable to evolving economic and fiscal conditions.
Who Is Affected by This Decision?
The implementation of this Ministerial Decision impacts a broad spectrum of stakeholders within the UAE’s tax ecosystem:
- Taxpayers and Business Entities: Companies and individuals engaging in taxable activities are required to adhere to the procedures and obligations outlined in the decision, including registration, record-keeping, and reporting standards.
- Federal Tax Authorities: The Federal Tax Authority (FTA) is responsible for enforcing the provisions, managing tax registrations, processing filings, and conducting audits in accordance with the decision’s guidelines.
- Legal and Advisory Professionals: Tax consultants, legal advisors, and auditors must familiarize themselves with the detailed procedures to provide accurate guidance and ensure compliance for their clients.
- Government Entities: Other relevant authorities involved in economic regulation, customs, and financial oversight are also affected, as they coordinate with the FTA to ensure seamless implementation.
Key Provisions and Operational Highlights
Tax Registration and Deregistration
The decision specifies the processes for registering taxable persons with the Federal Tax Authority, including the criteria for mandatory registration and the documentation required. It also outlines procedures for voluntary deregistration when applicable, ensuring flexibility and clarity for taxpayers.
Filing and Payment Procedures
Clear guidelines are provided on the deadlines and formats for submitting tax returns. The decision emphasizes the use of digital platforms to facilitate online filings, payments, and communication with the FTA, aligning with the UAE’s digital transformation initiatives.
Audit and Dispute Resolution
Procedures for conducting tax audits are detailed, including notification requirements and the rights of taxpayers during audits. The decision also establishes mechanisms for resolving disputes, encouraging transparency and fairness in enforcement actions.
References and Authority
This Ministerial Decision is issued under the authority of the UAE government, specifically the relevant ministerial and federal tax regulations. It is part of the broader legal framework that governs tax administration in the country, and its implementation is overseen by the Federal Tax Authority (FTA).
Taxpayers and professionals are advised to regularly consult official sources for updates and detailed procedural guidance related to this decision. The FTA’s digital platforms and official publications serve as primary references for compliance and procedural clarifications.
Conclusion
The Ministerial Decision implementing CD 52 of 2019 and its amendments plays a crucial role in shaping the UAE’s tax compliance environment. By providing clear operational procedures and reinforcing digital enforcement mechanisms, it supports the country’s strategic objectives of fostering a transparent, efficient, and business-friendly tax system. Stakeholders are encouraged to familiarize themselves with the provisions of this decision to ensure adherence and optimize their engagement with the UAE’s evolving tax regulations.