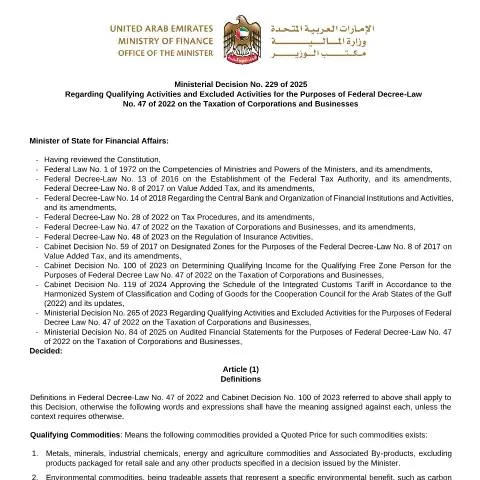
Overview of Ministerial Decision No. 229 of 2025 on Qualifying and Excluded Activities for Corporate Taxation in the UAE
In accordance with the provisions of Federal Decree-Law No. 47 of 2022 concerning the taxation of corporations and businesses, the United Arab Emirates has issued Ministerial Decision No. 229 of 2025. This decision clarifies the scope of activities that qualify for favorable tax treatment and those that are explicitly excluded from certain tax benefits. It aims to provide clarity for businesses operating within the UAE’s evolving tax framework, ensuring compliance while promoting transparency and legal certainty.
Context and Purpose of the Decision
The UAE’s move towards a comprehensive corporate taxation system necessitated a clear delineation of activities that are eligible for tax incentives or exemptions. Ministerial Decision No. 229 of 2025 serves as a critical regulatory instrument to define the boundaries of qualifying activities, thereby facilitating adherence to the legal framework established by the Federal Decree-Law. The decision also helps to prevent ambiguity in tax reporting and compliance, supporting the UAE’s broader objectives of economic diversification and attracting foreign investment.
Scope and Key Provisions
Qualifying Activities
The decision identifies specific activities that are deemed to contribute positively to the UAE’s economic objectives and are eligible for certain tax benefits. These typically include sectors aligned with national development plans, such as:
- Technology and innovation-driven enterprises
- Research and development activities
- Export-oriented manufacturing
- Renewable energy projects
- Financial services and fintech innovations
Entities engaged in these qualifying activities may benefit from reduced tax rates, exemptions, or other incentives as stipulated under the overarching framework of the federal tax law.
Excluded Activities
Conversely, the decision explicitly lists activities that are excluded from qualifying status due to their nature or potential impact on the UAE’s economic or social policies. Typical excluded activities include:
- Activities related to speculative financial trading
- Real estate speculation and certain property development activities
- Activities involving illegal or unethical practices
- Businesses primarily engaged in import-export without value addition
Such exclusions are designed to prevent abuse of the tax system and ensure that incentives are targeted towards activities that support sustainable economic growth.
Implementation and Compliance
Businesses operating within the UAE are advised to review their activities in light of the definitions provided in Ministerial Decision No. 229 of 2025. Compliance involves accurately categorizing activities during registration and reporting processes, which are primarily managed through the relevant federal and emirate-level digital portals.
The decision emphasizes the importance of maintaining detailed documentation and records to substantiate the classification of activities. This is crucial for audits and for claiming any applicable tax benefits under the law.
References and Regulatory Framework
This decision complements other legal provisions and guidelines issued by the Federal Tax Authority (FTA), which oversees the implementation and enforcement of the tax law. It also aligns with directives from the Ministry of Finance (MOF) and other relevant authorities involved in the UAE’s tax regime.
For detailed guidance, businesses are encouraged to consult the official publications and resources provided by the FTA and other related authorities through their digital platforms.
Conclusion
Ministerial Decision No. 229 of 2025 plays a pivotal role in operationalizing the UAE’s corporate tax law by providing clear definitions of qualifying and excluded activities. Its adoption reflects the UAE’s commitment to establishing a transparent, fair, and attractive business environment that aligns with international standards. Businesses should regularly review their activities against this framework to ensure ongoing compliance and to optimize their tax planning strategies within the legal boundaries set by the authorities.