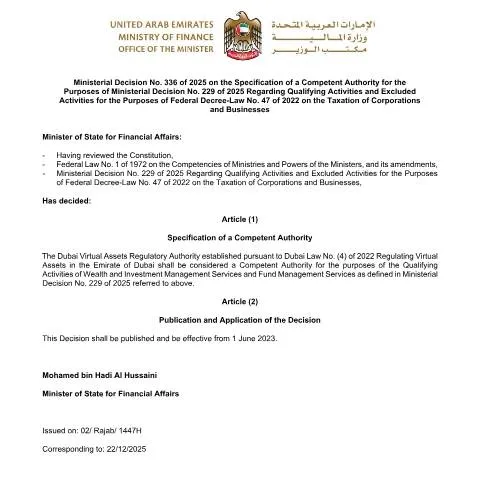
Overview of Ministerial Decision No. 336 of 2025 on Taxation Competent Authority
In line with the UAE’s ongoing efforts to enhance transparency and streamline tax regulation compliance, Ministerial Decision No. 336 of 2025 has been issued to specify the designated authority responsible for the implementation and oversight of certain provisions related to corporate and business taxation. This decision is part of the broader framework established under Federal Decree-Law No. 47 of 2022 concerning the taxation of corporations and businesses, and it aims to clarify the roles and responsibilities of the relevant authorities involved in qualifying and excluded activities.
Scope and Purpose of the Decision
The primary objective of Ministerial Decision No. 336 of 2025 is to designate the competent authority tasked with overseeing activities that qualify for tax incentives or exemptions, as well as those activities that are explicitly excluded from such benefits. This delineation is essential for ensuring consistent application of tax laws across the UAE’s federal and emirate-specific jurisdictions.
By establishing a clear authority, the decision supports the UAE’s strategic goal of fostering a business-friendly environment while maintaining compliance with international standards of tax transparency and fairness. It also facilitates the effective administration of tax regimes, providing clarity for taxpayers and tax officials alike.
Who is Affected by this Decision?
This decision impacts a broad spectrum of entities operating within the UAE, including:
- Corporate entities registered under federal or emirate-level regulations
- Business establishments engaging in activities subject to federal taxation laws
- Tax advisors and legal consultants assisting clients in compliance matters
Particularly, it influences entities involved in activities that are either classified as qualifying for tax benefits or explicitly excluded from such classifications, as per the provisions of Ministerial Decision No. 229 of 2025.
Key Provisions and Clarifications
Designation of the Competent Authority
The decision explicitly designates the authority responsible for the administration of qualifying and excluded activities related to corporate taxation. This authority is tasked with ensuring consistent interpretation of the relevant laws, issuing necessary guidelines, and managing applications for tax benefits or exclusions.
Activities and Classifications
While the detailed list of activities is outlined in the related ministerial decisions, this decision emphasizes the importance of clear classification to facilitate compliance and prevent ambiguities. Entities are encouraged to consult the designated authority for guidance on whether their activities fall within qualifying or excluded categories.
Implementation and Compliance
Taxpayers are expected to adhere to the guidelines issued by the designated authority, which will oversee the approval process for activities seeking tax benefits or exclusions. The authority also has the mandate to update classifications as necessary to reflect changes in the economic landscape or legal framework.
References and Regulatory Framework
This decision complements the overarching legal framework established by the UAE’s federal tax laws and the related ministerial decisions, notably Ministerial Decision No. 229 of 2025. It underscores the commitment of the UAE to maintain a transparent, efficient, and compliant tax system.
For further details, entities and individuals are advised to consult the official publications issued by the Federal Tax Authority (FTA) and other relevant authorities. All procedures and classifications are accessible through the official portals, ensuring a high degree of digital accessibility and administrative efficiency.
Conclusion
Ministerial Decision No. 336 of 2025 plays a vital role in clarifying the responsibilities and scope of the competent authority concerning corporate taxation activities in the UAE. Its implementation aims to streamline processes, promote compliance, and support the country’s strategic economic objectives. Stakeholders are encouraged to stay informed through official channels to ensure adherence to the latest regulations and guidelines issued by the relevant authorities.