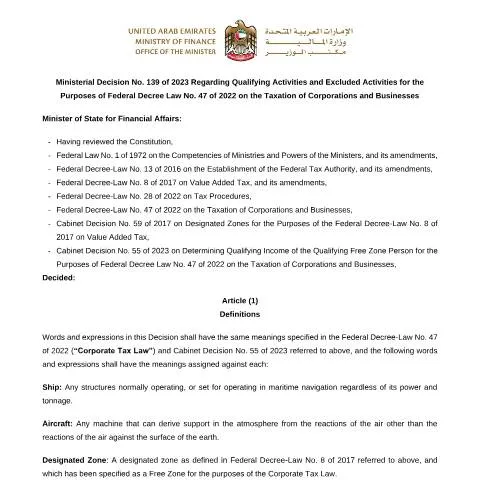
Overview of Ministerial Decision No (139) of 2023 on Tax-Related Activities in the UAE
The United Arab Emirates continues to refine its tax framework to ensure clarity and compliance for businesses operating within its jurisdiction. Ministerial Decision No (139) of 2023, issued by the UAE Ministry of Finance, plays a pivotal role in delineating the scope of activities that are considered qualifying for tax purposes under Federal Decree Law No (47) of 2022 concerning corporate and business taxation. This decision provides essential guidance for companies, tax consultants, and government authorities to determine which activities are subject to the new tax regime and which are excluded from its scope.
Purpose and Scope of the Decision
The primary objective of Ministerial Decision No (139) of 2023 is to specify the activities that qualify for tax obligations under the federal corporate tax law. It aims to facilitate a clear understanding among taxpayers regarding their responsibilities and to promote compliance with the UAE’s evolving tax legislation. The decision applies to all entities engaged in activities within the UAE that fall under the definitions provided by the federal law, with particular emphasis on distinguishing activities that are taxable from those that are exempt or excluded.
Defining Qualifying and Excluded Activities
Qualifying Activities
The decision enumerates certain categories of activities deemed to be directly related to the generation of taxable income. These include, but are not limited to, commercial trading, manufacturing, and certain professional services. Businesses engaged in qualifying activities are required to adhere to the regulations set forth in the federal tax law, including registration, filing, and payment obligations.
Excluded Activities
Conversely, the decision explicitly identifies activities that are excluded from the scope of the corporate tax law. These typically encompass activities with specific legal or policy exemptions, such as government operations, certain educational and healthcare services, and activities related to international organizations. Recognizing these exclusions helps prevent unnecessary tax liabilities and simplifies compliance for entities involved in such activities.
Implications for Businesses and Tax Compliance
This decision significantly impacts how businesses assess their tax obligations. Entities must carefully review their activities to determine whether they fall within the qualifying or excluded categories defined by the decision. Accurate classification is crucial, as it influences tax registration requirements, reporting obligations, and potential exemptions.
Furthermore, the decision emphasizes the importance of maintaining detailed documentation to substantiate activity classifications. Businesses are encouraged to leverage digital platforms provided by the UAE government to facilitate registration, reporting, and compliance processes. The UAE’s focus on digitalization ensures that businesses can efficiently manage their tax-related obligations through secure and user-friendly online portals.
Relevance to the UAE’s Broader Tax Framework
Ministerial Decision No (139) of 2023 complements the overarching objectives of the UAE’s tax reform, aiming to create a transparent, predictable, and business-friendly environment. By clearly defining qualifying and excluded activities, the decision supports the government’s efforts to attract diverse economic activities while ensuring appropriate tax collection and compliance.
It also aligns with the UAE’s commitment to international standards of tax transparency and cooperation, providing clarity for foreign investors and multinational corporations operating within the country.
Conclusion
In summary, Ministerial Decision No (139) of 2023 offers vital guidance on the scope of activities relevant to the UAE’s corporate tax regime. It delineates the boundaries between taxable and exempt activities, thereby aiding businesses in their compliance efforts and fostering a stable tax environment. Entities engaged in or planning to undertake activities within the UAE are advised to review this decision carefully and consult with authorized tax professionals or government portals to ensure adherence to all applicable regulations.