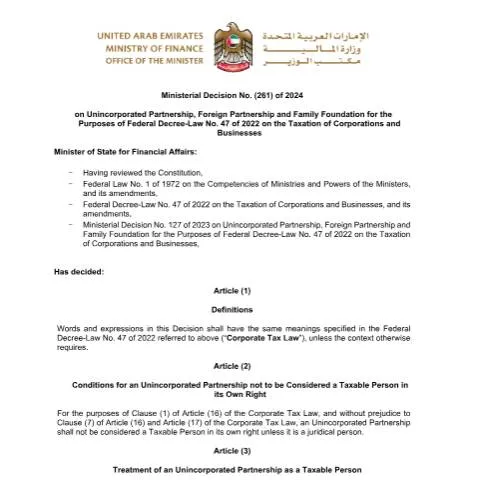
Overview of Ministerial Decision No (261) of 2024 on Taxation of Unincorporated and Family Entities
Ministerial Decision No (261) of 2024, issued by the Ministry of Finance of the United Arab Emirates, introduces specific provisions concerning the tax treatment of unincorporated partnerships, foreign partnerships, and family foundations. This decision aligns with the broader framework established under Federal Decree-Law No (47) of 2022, which governs the taxation of corporations and businesses within the UAE. Its primary objective is to clarify the legal and administrative treatment of these entities for tax purposes, ensuring compliance with the UAE’s evolving fiscal policies and digital governance standards.
Scope and Application of the Decision
This ministerial decision applies to unincorporated partnerships, foreign partnerships operating within the UAE, and family foundations that are subject to the provisions of Federal Decree-Law No (47) of 2022. It aims to specify the criteria under which these entities are recognized for tax obligations, delineate their reporting requirements, and establish the procedures for compliance within the federal tax system managed by the Federal Tax Authority (FTA).
Notably, the decision emphasizes the importance of transparency and proper documentation, which are facilitated through the digital platforms managed by the UAE government, including the UAE Pass and the FTA’s online portals. Entities falling under this scope are encouraged to utilize these digital tools for registration, tax filings, and compliance verification.
Main Provisions and Regulatory Clarifications
Recognition of Unincorporated and Foreign Partnerships
The decision provides a framework for recognizing unincorporated partnerships and foreign partnerships as taxable entities. It specifies that such entities must register with the FTA if they generate taxable income within the UAE. Registration procedures are streamlined through the federal digital platforms, ensuring a unified process that aligns with the UAE’s digitalization goals.
Taxation and Filing Obligations
Unincorporated and foreign partnerships are required to maintain accurate financial records and submit periodic tax returns via the FTA’s electronic system. The decision clarifies the scope of taxable income, including income derived from activities within the UAE, and emphasizes the importance of proper documentation to substantiate tax filings.
Family Foundations and Tax Compliance
Family foundations established within the UAE are now explicitly included under the scope of this decision. The provisions stipulate that these foundations, when engaged in economic activities or holding assets generating income, must adhere to the same registration and reporting obligations as other entities. This ensures consistent tax treatment and enhances transparency for family-owned entities.
Procedural and Administrative Aspects
The decision underscores the role of digital platforms in facilitating compliance. Entities are encouraged to utilize the UAE Pass for identity verification and access to the FTA’s e-services. The procedures for registration, filing, and amendments are designed to be fully digital, reducing administrative burdens and promoting efficiency.
Implications for Entities and Taxpayers
This decision signifies a shift towards comprehensive digital governance and increased oversight of non-corporate entities operating within the UAE. Entities such as partnerships and family foundations must now integrate their operations into the federal tax system, ensuring accurate reporting and adherence to legal obligations.
For taxpayers, this means enhanced clarity on their tax responsibilities and access to centralized digital tools for compliance. It also reinforces the importance of maintaining proper financial records and engaging with the FTA’s online systems to avoid penalties and ensure smooth operations.
Overall, Ministerial Decision No (261) of 2024 aims to foster a transparent, efficient, and compliant tax environment for diverse entity types, aligning with the UAE’s broader vision of digital transformation and fiscal integrity.