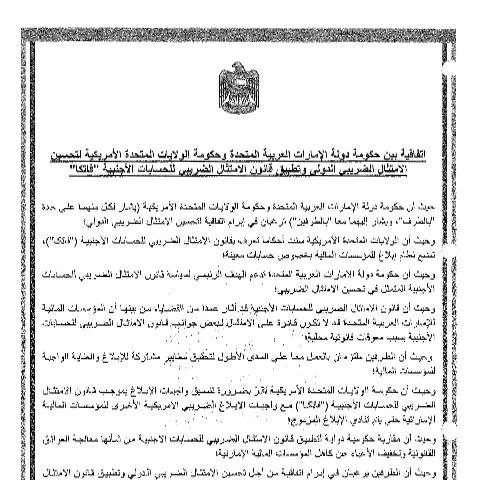
The Significance of the Intergovernmental Agreement between the UAE and the USA
The Intergovernmental Agreement between the United Arab Emirates (UAE) and the United States (US) serves as a pivotal document in the realm of financial transparency and information exchange. Specifically, this agreement aims to enhance the UAE's compliance with international tax standards, particularly in relation to the Foreign Account Tax Compliance Act (FATCA). Through this framework, it facilitates a structured approach for reporting financial information pertaining to US taxpayers, ensuring that both nations uphold their commitments to combat tax evasion.
Understanding the Role of the Reporting Document
This document, referred to as "الاتفاقية الحكومية الدولية الإماراتية-الأمريكية" (the intergovernmental agreement), outlines the responsibilities of financial institutions within the UAE. Its primary role is to provide a compliant reporting mechanism for US account holders. Thus, it simplifies the process of reporting and promotes transparency. Financial institutions must facilitate the collection and reporting of information pertaining to qualifying accounts held by US persons.
Key Responsibilities for Financial Institutions
- Identify US Account Holders: Financial institutions are required to identify accounts held by US citizens or residents.
- Report Information: They must report specified financial information to the relevant authorities in both the UAE and the US.
- Cooperate with Authorities: Institutions are mandated to cooperate with tax authorities to ensure compliance with FATCA.
Who Should File This Document?
The submission of this document is mandatory for financial entities operating within the UAE that engage with US account holders. This encompasses a wide range of institutions, including banks, investment funds, and insurance companies. Moreover, it applies to entities classified as non-financial foreign entities under US law, thereby expanding the scope of accountability.
Specific Cases: Foreign Individuals and Minors
When dealing with foreign individuals, particularly minors, additional considerations come into play. The financial institution must ensure that:
- Accounts held by minors are accurately reported under the guardian's oversight.
- Foreign individuals are made aware of their reporting obligations under US law.
Navigating the Submission Process
How to Complete and Submit the Document
Completing the document requires precision and attention to detail. Financial institutions must gather necessary information, ensuring adherence to the guidelines set forth in the agreement. The following steps outline the process:
- Gather Information: Collect relevant taxpayer information, including names, addresses, and taxpayer identification numbers.
- Complete the Form: Enter the gathered data into the specified fields of the reporting document.
- Review for Accuracy: Conduct a thorough review to ensure accuracy and compliance with both UAE and US regulations.
- Submit Electronically: Use the designated electronic channels for submission to ensure timely processing.
Submission Channels: Online vs. Paper
It is crucial to understand the channels available for submission:
| Channel | Description | Pros | Cons |
|---|---|---|---|
| Online Submission | Submitting via designated platforms ensures a quicker process. | Fast processing, tracking capabilities. | Requires internet access and technical know-how. |
| Paper Submission | Submitting physical documents through postal services. | Tangible evidence of submission. | Longer processing times, potential for loss during transit. |
Timelines: Key Dates for Submission
Understanding the timeline is crucial for compliance. The following dates should be noted:
- Initial Reporting Deadline: Typically set at the end of the tax year.
- Annual Updates: Financial institutions must provide updated information annually.
- Notifications: Institutions should notify account holders of their reporting obligations at least 30 days prior to the deadline.
Consequences of Non-Compliance
Failure to adhere to the requirements set out in the intergovernmental agreement can lead to significant repercussions. These may include:
- Financial Penalties: Institutions may face fines for failing to report accurately.
- Legal Consequences: Non-compliance can result in legal action from tax authorities.
- Reputational Damage: Institutions may suffer damage to their reputation, affecting customer trust.
What Happens After Submission?
Once the document is submitted, several processes unfold:
- The financial institution awaits acknowledgment from authorities regarding receipt and compliance.
- Follow-up may occur if additional information is required.
- Annual audits may be conducted to ensure adherence to reporting requirements.
The Broader Implications of the Agreement
This intergovernmental agreement not only reinforces the UAE's commitment to global tax standards but also enhances bilateral relations with the United States. By facilitating the exchange of financial information, it helps combat tax evasion and promotes a fair global financial system.
Expectations from Financial Institutions
With the implementation of this agreement, financial institutions are expected to:
- Invest in training staff on compliance and reporting requirements.
- Enhance systems for data collection and reporting to meet international standards.
- Engage in ongoing communication with authorities to ensure alignment with evolving regulations.
Understanding the UAE-US Double Taxation Agreement
The UAE-US Double Taxation Agreement (DTA) is a significant treaty that aims to avoid double taxation and prevent fiscal evasion concerning taxes on income. This agreement, in line with international standards, is designed to encourage investment, economic cooperation, and trade between the two nations. As a legal framework, it provides clarity and benefits to businesses and individuals engaged in cross-border activities. Understanding the specific provisions of this DTA is essential for both residents and expatriates in the UAE.
Key Provisions of the DTA
The DTA encompasses various provisions tailored to mitigate taxation challenges. For instance, it primarily addresses taxation on various income types, such as dividends, interest, and royalties, ensuring that these are taxed at reduced rates or are exempt under specific conditions. It also outlines the residency criteria, which is pivotal to determine the eligibility of taxpayers for the benefits of the agreement.
Under the DTA, residents of the UAE earning income from the US may benefit from reduced withholding tax rates. For instance, dividends may be taxed at a maximum rate of 5% if the beneficial owner holds at least 10% of the company’s voting stock. Interest income is typically exempt from US taxation if it meets certain conditions, while royalties may face a reduced withholding tax rate.
Application and Compliance Requirements
To benefit from the provisions of the DTA, individuals and corporations must comply with specific documentation and procedural requirements. Generally, this includes obtaining a Tax Residency Certificate (TRC) from the Federal Tax Authority (FTA) in the UAE. This certificate serves as proof of residency for tax purposes and is crucial for claiming the benefits outlined in the DTA.
Moreover, it is essential to maintain accurate records of income and tax withheld to substantiate claims under the agreement. Taxpayers must also be aware of filing obligations in both jurisdictions, as compliance with local tax laws is paramount to avoid penalties.
Implications for Expatriates Living in the UAE
For expatriates residing in the UAE, the DTA has considerable implications on their financial planning and tax liabilities. Depending on their residency status and source of income, the benefits of the agreement can significantly reduce their overall tax burden while ensuring compliance with respective tax authorities.
Financial Planning and Retirement Considerations
Expatriates are encouraged to integrate the advantages of the DTA into their financial planning strategies. For instance, those investing in US-based assets or receiving income from US sources should consider the DTA when making investment decisions. It may influence their choices regarding retirement contributions, whether to establish a US retirement account, or how to strategize withdrawals to maximize tax efficiency.
In addition, expatriates should be mindful of the implications of domicile status in relation to estate planning. The DTA offers various avenues for estate tax considerations, particularly for expatriates intending to transfer wealth or assets to beneficiaries in the UAE or the US. Understanding how the DTA interacts with local inheritance laws is crucial in formulating a comprehensive estate plan.
Challenges and Considerations for Foreign Businesses
Foreign businesses operating within the UAE or seeking to establish a presence may face unique challenges despite the DTA. While the agreement promotes bilateral trade and investment, businesses must navigate the complexities of the UAE's regulatory environment, including local licensing requirements and compliance with the Economic Substance Regulations. Moreover, understanding the local tax landscape is vital, as the UAE implements different regulatory frameworks across its emirates.
Foreign entities should also be aware of the implications of the DTA on cross-border transactions. For instance, they may need to reassess their pricing strategies, considering the withholding tax implications when repatriating profits to the US. Additionally, familiarity with the tax incentives available in the UAE, such as Free Trade Zones, is essential to leverage the DTA effectively.
The Role of the UAE Federal Tax Authority (FTA)
The UAE Federal Tax Authority (FTA) plays a pivotal role in the implementation and administration of the DTA between the UAE and the US. As the central body responsible for tax affairs in the UAE, the FTA ensures compliance with tax regulations and facilitates the necessary approvals for taxpayers seeking to benefit from the DTA.
Tax Residency Certificate (TRC) Issuance Process
For individuals and businesses to claim tax relief under the DTA, the issuance of a Tax Residency Certificate (TRC) is an essential step. The TRC serves as proof of residency and is crucial for substantiating claims for reduced or exempt withholding tax under the agreement. The application process typically requires the submission of financial statements, proof of residency, and documentation evidencing income sources. The FTA processes these applications digitally, emphasizing efficiency and transparency, enabling a smoother experience for applicants.
Guidelines for Compliance and Reporting
The FTA also provides guidelines for compliance and reporting requirements related to the DTA. Taxpayers are expected to report their income accurately and provide necessary documentation to support claims for tax relief. This includes maintaining accurate records and adhering to the UAE’s tax regulations to avoid penalties. The FTA conducts audits to ensure compliance, thus stressing the importance of adhering to legal obligations while benefiting from the DTA.
Educational Initiatives and Resources
The FTA actively engages in educational initiatives and provides resources aimed at informing taxpayers about the DTA and its implications. This includes workshops, webinars, and online resources that elucidate the tax rights and obligations of residents concerning the DTA. Taxpayers are encouraged to utilize these resources for comprehensive understanding and compliance, thereby fostering a culture of tax awareness and responsibility within the community.