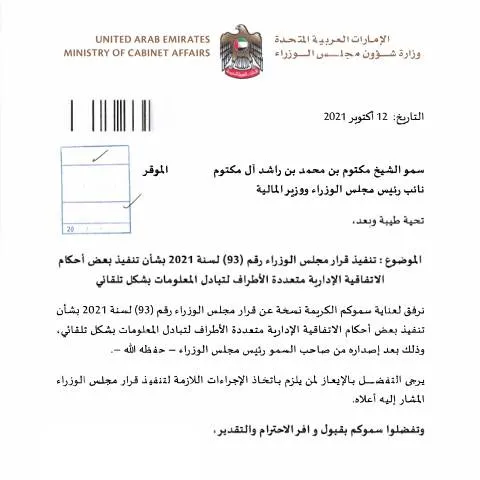
The Significance of the Ministerial Resolution No. (93) of 2021
In the evolving landscape of international financial compliance, the Ministerial Resolution No. (93) of 2021 regarding the implementation of certain provisions of the Multilateral Competent Authority Agreement on Automatic Exchange of Financial Account Information (التبادل التلقائي للمعلومات) plays a crucial role. This resolution not only aligns the United Arab Emirates (UAE) with global standards but also enhances the UAE's commitment to transparency in financial information exchange.
Understanding the Scope of the Resolution
This resolution is designed to facilitate the automatic exchange of information among member countries, thereby preventing tax evasion and promoting fiscal accountability. It lays out the responsibilities of both the financial institutions and the regulatory authorities within the UAE.
- Objective: To ensure compliance with the UAE's obligations under international agreements.
- Implementation: It delineates the framework for how financial institutions must report account information to the relevant authorities.
- Regulatory Oversight: The resolution assigns roles to various ministries, particularly the Ministry of Finance and the regulatory authorities.
Who is Responsible for Submitting the Document?
Entities required to submit the reports as per the resolution include financial institutions, which are defined under the UAE's laws and regulations. These institutions include banks, investment firms, and any other entities that manage financial accounts.
Furthermore, the resolution also specifies that the regulatory authorities, including the Ministry of Finance and relevant financial authorities, will oversee compliance and ensure that institutions meet their reporting obligations.
Categories of Institutions to Consider
| Type of Institution | Examples | Reporting Obligations |
|---|---|---|
| Banking Institutions | Commercial banks, Islamic banks | Must report financial accounts held by foreign residents. |
| Investment Firms | Securities brokers, asset management companies | Required to disclose account information relevant to foreign investors. |
| Insurance Companies | Life insurance firms | Must provide information on certain insurance contracts. |
Preparing for Submission: Essential Documentation
To fulfill the reporting requirements effectively, institutions must prepare comprehensive data packages. The key elements include:
- Account Holder Identification: Exact details about the account holders, including their names, addresses, and taxpayer identification numbers.
- Financial Data: Information related to the accounts maintained during the reporting period, including balances, interest earned, and account transactions.
- Compliance Documents: Proof of adherence to the internal control measures instituted to ensure compliance with the resolution.
Steps to Prepare Documentation
- Gather relevant account information from the bank's database.
- Verify the accuracy of account holder data.
- Compile financial data for each account as specified in reporting guidelines.
- Review compliance documents and ensure that they are up-to-date.
Submission Channels for Compliance
Institutions must understand the available channels for submitting their reports. The channels include:
- Online Submission: Preferred method through the official portals provided by the Ministry of Finance and regulatory authorities.
- Physical Submission: Less common but still allowed; institutions can submit hard copies of their reports.
- Direct Communication: In certain cases, institutions may need to engage directly with regulatory bodies for clarifications or additional requirements.
Online Submission: Detailed Steps
For institutions opting for online submission, the process typically involves the following steps:
- Log in to the official portal using secure credentials.
- Select the appropriate form based on the type of institution.
- Input all required information in the specified fields.
- Upload supporting documents and double-check for completeness.
- Submit the report before the deadline.
Timelines: Key Dates for Submission
Adhering to timelines is crucial. The resolution outlines reporting periods and deadlines:
- Annual Reporting Cycle: Reports must typically cover the financial year and be submitted by the end of June each year.
- Extension of Deadlines: Extensions may be granted under exceptional circumstances but require prior approval from the relevant authority.
Post-Submission: What Happens Next?
After submitting the reports, institutions will enter a follow-up phase:
- Verification Process: Regulatory authorities will review submitted data for accuracy and compliance.
- Feedback Mechanism: Institutions may receive feedback or requests for additional information.
- Compliance Review: Regular audits may occur to ensure ongoing compliance with the reporting standards.
Distinctions from Similar Regulatory Documents
Understanding the nuances that distinguish this resolution from other financial compliance documents is essential. Key differences include:
- Scope of Information: Unlike other frameworks, this resolution focuses specifically on automatic exchanges of information related to financial accounts.
- International Alignment: It is part of a broader effort to comply with OECD and G20 standards, making it unique in its international focus.
- Regulatory Authority Engagement: There is a clearer outline of roles between different regulatory bodies, which can differ significantly from previous regulations.
Critical Features of the Resolution
Some essential features that set this resolution apart include:
- Digital Reporting Solutions: Emphasis on digital submission enhances efficiency and reduces human error.
- Comprehensive Guidelines: The resolution provides explicit instructions on what constitutes reportable data.
- Compliance Penalties: Clearly articulated penalties for non-compliance, incentivizing accurate reporting.
Conclusion: The Path to Transparency
The implementation of Ministerial Resolution No. (93) of 2021 signifies the UAE's commitment to global financial standards and transparency. By adhering to its guidelines, institutions not only comply with legal obligations but also contribute to a more accountable financial ecosystem. Entities must invest time and resources into understanding the requirements, preparing accurate submissions, and ensuring compliance to foster trust and integrity in international finance.
Understanding the Cabinet Resolution No. (93) of 2021
The Cabinet Resolution No. (93) of 2021, concerning the implementation of certain provisions of the Multilateral Convention on Automatic Exchange of Information (AEOI), represents a significant step for the UAE in enhancing transparency and compliance within the global financial landscape. This resolution aligns the UAE’s practices with international standards set by the Organisation for Economic Co-operation and Development (OECD). The AEOI aims to combat tax evasion and promote global tax compliance by facilitating the automatic exchange of financial information between participating jurisdictions.
Through this resolution, the UAE solidifies its commitment to international tax cooperation, thereby fostering a compliant environment for both individuals and businesses. One key aspect of the Cabinet Resolution is the emphasis on the automation of data exchange processes, which is designed to streamline compliance for stakeholders involved in financial activities. Underlying the resolution are specific guidelines that outline the obligations of financial institutions in the UAE to collect, verify, and report information regarding foreign account holders. This shift not only aligns with global tax standards but also positions the UAE as a responsible player in the international financial system.
Impact on Businesses and Individuals in the UAE
The implications of Cabinet Resolution No. (93) extend to both businesses and individuals residing in the UAE. For businesses within the financial sector, particularly banks, insurance companies, and investment funds, there is a necessity to adapt to the new reporting requirements. Financial institutions are mandated to assess their client base to identify reportable accounts, which includes foreign individuals and entities. This necessitates investing in robust compliance systems to ensure that all required information is captured accurately and reported in accordance with AEOI standards.
For individuals, particularly expatriates and foreign investors, this resolution underscores the importance of understanding their tax obligations not just in the UAE, but also in their home countries. Individuals with financial accounts in the UAE need to be aware of how their information may be shared with tax authorities in other jurisdictions. This awareness is crucial, as it encourages individuals to maintain compliance with their home country’s tax laws, thereby avoiding potential penalties or legal repercussions.
The resolution also promotes a culture of voluntary compliance among taxpayers. By establishing clear guidelines and requirements, it helps build an environment where individuals and businesses feel secure in fulfilling their tax obligations. Notably, the resolution does not only focus on compliance but also ensures that privacy and data protection measures are in place, providing stakeholders with confidence in the handling of their financial information.
Future Implications and Trends in Information Exchange
As the UAE continuously evolves its regulatory framework, the future implications of Resolution No. (93) could lead to further advancements in information exchange and compliance management. The trend towards digitalization within governmental processes indicates that future developments may involve enhanced technological solutions for reporting and data sharing. The UAE’s digital government initiatives, including the Emirates ID and UAE Pass, will play a crucial role in facilitating secure and efficient data exchanges among various stakeholders.
Moreover, as countries around the world increasingly adopt and refine their regulations concerning automatic information exchange, the UAE may also find itself participating in additional bilateral agreements with other jurisdictions. These agreements may extend the automatic exchange framework, providing a broader scope of compliance obligations for businesses and individuals. The ongoing collaboration between the UAE government and international organizations will likely influence the trajectory of these developments, as the UAE works to maintain its competitive advantage as a global financial hub.
In conclusion, the Cabinet Resolution No. (93) serves as a pivotal element in the UAE’s commitment to ensuring transparent financial practices. By understanding the intricacies of this resolution, stakeholders can better navigate the complexities of compliance and harness opportunities that arise from a more interconnected global economy.