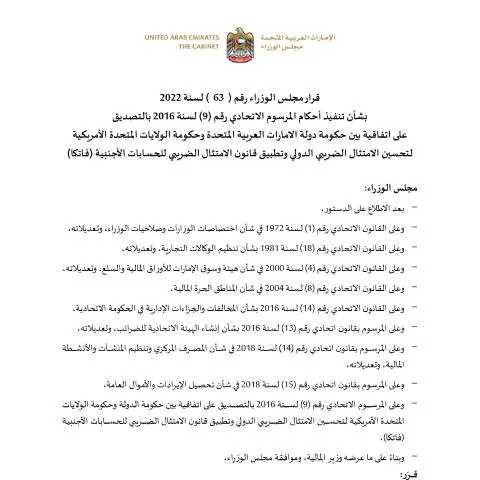
Understanding the Cabinet Decision No. (63) of 2022 on Automatic Exchange of Information
The United Arab Emirates (UAE) has taken significant steps to enhance its compliance with international tax transparency standards through the issuance of Cabinet Decision No. (63) of 2022. This decision formalizes the implementation of provisions stemming from Federal Decree-Law No. (9) of 2016, specifically concerning the Automatic Exchange of Information (AEOI) framework between the UAE and the United States of America. This guide provides an overview of the decision’s scope, its implications for relevant entities, and the mechanisms established to facilitate compliance.
Context and Scope of the Decision
The decision is part of the UAE’s broader commitment to align with global efforts to combat tax evasion and promote transparency. It operationalizes the legal obligations set forth in the federal legislation that mandates the automatic sharing of financial account information with foreign tax authorities, notably the United States. The framework aims to ensure that financial institutions and related entities within the UAE adhere to international standards for reporting and information exchange, thereby fostering a cooperative environment for tax compliance and financial integrity.
Who Is Affected by the Decision?
This decision primarily impacts financial institutions, including banks, investment entities, and other reporting financial entities operating within the UAE. These institutions are required to identify accounts held by U.S. persons or entities with U.S. connections and to report relevant financial information to the UAE Federal Tax Authority (FTA). The FTA then facilitates the exchange of this information with the U.S. Internal Revenue Service (IRS) in accordance with the relevant bilateral agreement.
Additionally, entities involved in cross-border financial activities, including asset managers and custodians, should be aware of their obligations under this framework. The decision underscores the importance of maintaining accurate client information and implementing compliance procedures aligned with the UAE’s international commitments.
Key Points of the Cabinet Decision
- Implementation of International Standards: The decision enforces the UAE’s commitment to the Common Reporting Standard (CRS) and the U.S.-UAE Intergovernmental Agreement (IGA) for the exchange of financial account information.
- Reporting Requirements: Financial institutions must identify reportable accounts and submit annual reports to the FTA, following prescribed formats and deadlines.
- Data Confidentiality and Security: The decision emphasizes strict confidentiality measures and secure handling of exchanged information, in accordance with applicable laws and regulations.
- Legal and Administrative Framework: The decision provides the legal basis for cooperation between the UAE and the U.S., ensuring that the exchange process adheres to legal standards and safeguards.
Implementation and Compliance Mechanisms
The UAE’s digital infrastructure plays a crucial role in facilitating compliance with this decision. Financial institutions are expected to utilize the designated electronic portals managed by the Federal Tax Authority (FTA) to report relevant information. These portals are designed to streamline the reporting process, ensure data accuracy, and enhance security.
Entities are advised to review their internal procedures for client due diligence, account monitoring, and data management to align with the requirements of the decision. The FTA provides guidance and support to ensure that reporting entities understand their obligations and can implement necessary compliance measures effectively.
References and Further Guidance
For detailed information, entities are encouraged to consult the official publications and guidelines issued by the Federal Tax Authority and other relevant authorities. These resources outline the specific procedures, reporting formats, and legal obligations under the UAE’s AEOI framework.
In summary, Cabinet Decision No. (63) of 2022 reinforces the UAE’s commitment to international tax transparency and provides a clear legal and operational framework for the automatic exchange of financial information with the United States. Financial institutions and related entities should proactively adapt their compliance programs to meet these obligations, ensuring compliance with both national legislation and international standards.