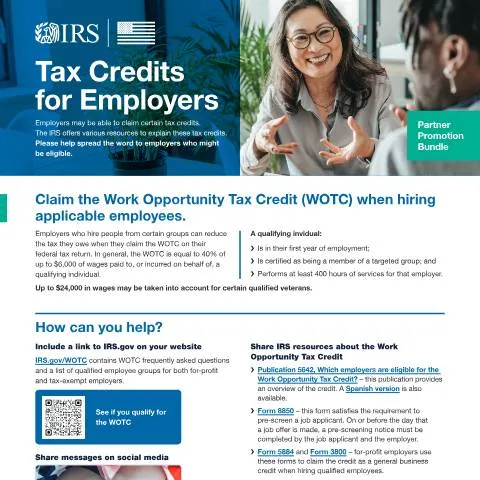
A Comprehensive Guide to IRS Publication 6041
Navigating the labyrinth of tax regulations and forms can be daunting, especially when it comes to understanding specific IRS publications. IRS Publication 6041 is particularly crucial for employers seeking to understand their responsibilities regarding tax credits for hiring employees from certain targeted groups. This publication provides essential guidelines on how to leverage tax credits to optimize financial obligations.
The Intricacies of IRS Publication 6041
IRS Publication 6041, with its focus on tax credits, is a critical resource for businesses that want to maximize their tax savings. It lays the groundwork for employers who hire people from specific groups, such as veterans and long-term unemployed individuals, by explaining the Work Opportunity Tax Credit (WOTC). This incentive can lead to substantial savings, equating to 40% of the first $6,000 in wages paid to qualifying employees.
Why Employers Should Pay Attention
The stakes are high when it comes to tax credits; employers who fail to understand or utilize these opportunities may miss out on significant financial benefits. Publication 6041 aims to demystify the eligibility criteria and application processes, making it easier for employers to navigate the complexities of tax credits.
Distinguishing Features of Publication 6041
While many may confuse Publication 6041 with other tax-related documents, its specific focus on tax credits sets it apart. Other IRS publications, such as Form 8850 (which is used to pre-screen applicants) and Form 5884 (for claiming the WOTC), serve different purposes. Publication 6041 consolidates the necessary information, including eligibility requirements and procedures into a single, comprehensive document.
Understanding the Work Opportunity Tax Credit (WOTC)
The Work Opportunity Tax Credit (WOTC) is integral to IRS Publication 6041. It incentivizes employers to hire individuals who face significant barriers to employment. This program not only aids employees but also strengthens the economy by reducing unemployment rates among targeted groups.
Eligibility Criteria for WOTC
- A new employee must be certified as a member of a targeted group.
- Employees must work a minimum of 400 hours for the employer.
- Specific groups eligible for WOTC include:
- Veterans
- Individuals receiving SNAP benefits
- Ex-felons
- Long-term unemployed individuals
Calculating Your Credit
The tax credit amount varies based on the employee’s target group and the wages paid. Generally, employers can claim 40% of the first $6,000 in wages paid to qualifying individuals, leading to a maximum credit of $2,400 per eligible hire. For veterans, the credit can go up to $9,600, depending on their circumstances.
Completing the Process: Steps for Employers
Employers must follow a series of steps to claim the tax credits effectively. This section will guide you through the essential phases, ensuring that you adhere to IRS regulations.
Step-by-Step Claim Process
- Pre-screening Applicants: Complete Form 8850 on or before the job offer date.
- Obtaining Certification: Submit the completed Form 8850 to your state workforce agency for certification.
- Filing for the Credit: If certified, complete Form 5884 and attach it to your federal tax return.
- Record Keeping: Maintain records of all documentation related to the WOTC for at least four years.
Common Mistakes to Avoid
Employers often make mistakes that can jeopardize their ability to claim the WOTC. Here are some pitfalls to steer clear of:
- Failing to submit Form 8850 on time.
- Not retaining sufficient documentation.
- Assuming all new hires qualify without verification.
Alternative Options and Special Cases
Not all employers will qualify for the WOTC, nor will all employees fit neatly into the established categories. Understanding alternative options and special cases is vital for maximizing your tax benefits.
Special Circumstances
Some situations require a deeper understanding of eligibility, particularly for employers hiring individuals from diverse backgrounds. Here are a few scenarios:
- Foreign Nationals: Employers hiring foreign nationals on work visas may still qualify for the WOTC if the individual falls into a targeted group.
- Minors: While generally not a targeted group for the WOTC, minors working part-time may still qualify if they fall within certain categories.
- Complex Employment Structures: Businesses with multiple subsidiaries may need to navigate inter-company hiring practices to ensure compliance.
Submission Channels: Electronic vs. Paper Filing
Employers have options when it comes to submitting their claims and documentation. Understanding the advantages and disadvantages of each can streamline the process significantly.
Online Submission Benefits
Filing electronically is becoming the norm and offers several advantages:
- Faster processing times
- Immediate confirmation of submission
- Reduced likelihood of errors
Paper Filing Considerations
While some employers might still prefer paper filing, this method does come with challenges:
- Longer processing times
- Increased risk of lost documents
- Potential delays in receiving credits
The Historical Context Behind Publication 6041
Understanding the historical context of IRS Publication 6041 provides essential insights into its development and relevance in today’s tax landscape.
Legislative Backdrop
The WOTC program has its roots in the Small Business Job Protection Act of 1996, designed to encourage the hiring of individuals from disadvantaged backgrounds. Over the years, the publication has evolved to reflect changes in labor market conditions and demographic shifts.
Impact of Economic Changes
The fluctuations in the economy often dictate the demand for programs like WOTC. During economic downturns, the programs are more vital as they compel employers to rethink hiring strategies. IRS Publication 6041 has adapted to highlight these changing needs, emphasizing the importance of tax credits as tools for stimulating employment.
Target Audience and Unique Scenarios
IRS Publication 6041 primarily targets employers but understanding the nuances of different profiles can provide further clarity on who may benefit from the information contained in this resource.
Employer Profiles
- Small Businesses: Often lack resources to navigate tax complexities but can greatly benefit from WOTC.
- Large Corporations: Typically have dedicated HR and finance teams but may overlook targeted groups when hiring.
- Non-Profits: Can also benefit from WOTC when hiring eligible individuals, although they must navigate unique organizational challenges.
Exception Cases
Not all hiring scenarios are straightforward. Employers must pay special attention to the following scenarios:
- Seasonal hires may not qualify due to the short duration of employment.
- Employee relocations might complicate initial eligibility based on state-specific requirements.
- Individuals transitioning from public assistance programs have additional documentation requirements.
Ensuring Compliance and Maximizing Benefits
Staying compliant while maximizing the benefits of IRS Publication 6041 requires diligent attention to detail and an understanding of the ongoing changes in tax law.
Best Practices for Employers
To successfully navigate the complexities of tax credits, employers should consider the following best practices:
- Stay updated on IRS guidelines by regularly reviewing relevant publications.
- Utilize available resources for training HR personnel on WOTC eligibility and requirements.
- Consult with tax professionals for tailored advice based on specific hiring situations.
Ongoing Changes and Updates
The IRS periodically revises its publications to reflect changes in tax laws, economic conditions, and employer needs. Keeping abreast of these updates is crucial for making informed hiring and tax decisions.
In summary, IRS Publication 6041 is not just a resource; it is a vital tool for navigating the complexities of tax credits associated with hiring. Employers who leverage this publication stand to gain significantly, not just in financial terms but also by contributing positively to the workforce. By understanding and implementing the guidelines set forth in Publication 6041, businesses can create a more inclusive hiring environment that benefits both the employer and the employee.
Understanding IRS Publication 6041: A Comprehensive Overview
IRS Publication 6041 serves as a vital resource for both tax professionals and individuals navigating the complexities of tax reporting obligations, particularly concerning payments made to corporations and other entities. This publication outlines the specific requirements for reporting payments that must be reported to the IRS, which is crucial for compliance with federal tax laws.
The IRS requires that certain payments be reported via Form 1099, which is critical for ensuring that all parties are meeting their tax obligations. The publication details the types of payments that fall under this requirement—ranging from rents to nonemployee compensation—and clarifies the thresholds at which reporting becomes necessary. Understanding these nuances can significantly affect how taxpayers and businesses file their taxes. For example, payments made to attorneys or for services rendered by independent contractors often require additional attention in reporting.
Common Reporting Errors and How to Avoid Them
One of the most common issues taxpayers face when dealing with IRS Publication 6041 is the potential for reporting errors. Accurate reporting is essential, as mistakes can lead to penalties, interest on unpaid taxes, or even audits. Understanding the common pitfalls can aid in ensuring compliance.
First, be aware of the specific payment types that mandate reporting. For instance, payments made for personal services are generally reportable, while those made for personal purchases are not. An entity may mistakenly attempt to report a reimbursement as income, leading to complications. Additionally, errors often arise from incorrect taxpayer identification numbers (TINs). Taxpayers must ensure that TINs match the names and structures of the organizations or individuals they are compensating. The IRS employs a system called TIN Matching, which can help identify discrepancies before filing.
Another area of concern includes the timing of payments. Payments must be reported in the year they are made, which can cause confusion for those who operate on a fiscal rather than calendar year. IRS Publication 6041 provides guidance on how to align your reporting with the correct fiscal calendar, ensuring you’re compliant with federal standards.
The Role of Technology in Streamlining Compliance
In an increasingly digital world, technology plays an essential role in simplifying the tax reporting process outlined in IRS Publication 6041. Various software solutions can help businesses manage their payments and reporting obligations more efficiently, minimizing the risk of errors and ensuring compliance with IRS requirements.
Many tax software platforms are equipped with features that assist users in tracking payments made to different entities, automatically categorizing them according to IRS guidelines. This not only speeds up the reporting process but also reduces the likelihood of misreporting. Additionally, these platforms often provide updates based on the latest IRS regulations, ensuring that businesses remain compliant with current laws.
Furthermore, the IRS itself has embraced technology by introducing e-filing options for Form 1099 and other related forms. E-filing is often faster and provides immediate confirmation, which is beneficial for businesses operating under tight deadlines. Taxpayers should familiarize themselves with the e-filing process and the specific requirements for electronic submissions, as this can enhance compliance and efficiency.
As technology continues to evolve, staying informed about the tools and best practices for tax reporting will be crucial for both individual taxpayers and businesses. Leveraging technology effectively can lead to improved accuracy in compliance and a smoother overall tax experience.