Diving into IRS Form 8804-W: Understanding the Essentials
Completing your tax obligations as a partnership in the United States can be a complex endeavor, especially when dealing with foreign partners. One critical document in this landscape is the IRS Form 8804-W, designed to facilitate installment payments of Section 1446 tax for partnerships. This form plays a pivotal role for partnerships with foreign partners, ensuring compliance with U.S. tax regulations while also aiding in the appropriate reporting of income.
Contextualizing the Need for Form 8804-W
The IRS requires partnerships with foreign partners to manage and report their estimated tax liabilities related to effectively connected taxable income (ECTI). The necessity of Form 8804-W arises when a partnership anticipates owing taxes on ECTI that is allocable to foreign partners. As such, this form is significant for managing anticipated tax payments for the current tax year while considering the unique circumstances of each partnership.
Who Should File Form 8804-W?
Form 8804-W is specifically tailored for partnerships that have foreign partners and expect to owe taxes on ECTI. The following categories of partnerships typically need to file this form:
- Partnerships with corporate foreign partners.
- Partnerships with non-corporate foreign partners.
- Partnerships that expect to make estimated installment payments on behalf of their foreign partners.
Moreover, it’s crucial to grasp that any partnership making installment payments for section 1446 taxes must not only consider the tax obligations for the current year but also those for the preceding year as well.
Breaking Down the Filing Process: Step by Step
Filing Form 8804-W requires careful preparation and consideration of various components related to the partnership's tax situation. Below is a detailed guide to navigating this process:
Step 1: Gather Necessary Information
Before completing Form 8804-W, partnerships should gather the following:
- Allocable share of ECTI expected for the current tax year for all foreign partners.
- Details regarding the foreign partners, including corporate and non-corporate allocations.
- Information on state and local taxes that may affect tax liability.
- Data from Form 8804-C if applicable for certified foreign partner-level items.
Step 2: Completing the Form
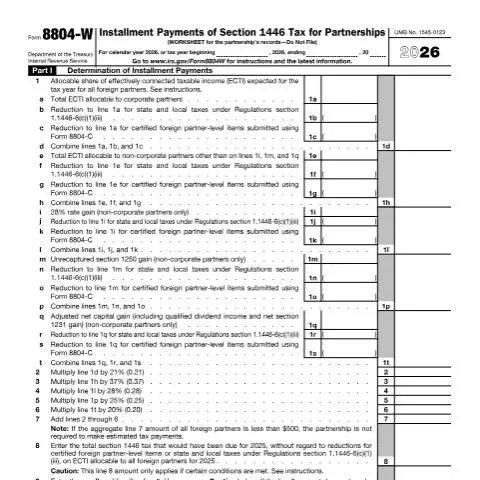
Form 8804-W is structured to guide partnerships through determining their installment payments. Key sections include:
- Part I: Determination of Installment Payments - This section allows partnerships to establish the total ECTI and calculate necessary payments based on different partner types.
- Part II: Adjusted Seasonal Installment Method - This section is relevant if the partnership opts to employ an adjusted seasonal installment method, which can benefit partnerships with distinct income patterns over the year.
Each part requires precise calculations and a thorough understanding of the tax obligations underpinning the partnership arrangements.
Step 3: Installment Payment Calculations
Partnerships must perform calculations for estimated taxes owed by multiplying ECTI values by the applicable tax rates. It's important to note:
- The tax rate may differ based on whether the partners are corporate or non-corporate.
- Reductions for state and local taxes should be factored in appropriately.
- There's a crucial caution regarding amounts entered on the form that could affect eligibility for safe harbor provisions.
Remember, if the total section 1446 tax for foreign partners is less than $500, the partnership is not required to make estimated tax payments, simplifying compliance efforts.
Timelines and Deadlines for Submission
Understanding the timeline involved in completing and submitting Form 8804-W is essential for compliance. Here’s what partnerships should keep in mind:
Filing Deadlines
For each calendar year, the deadlines align with the general tax timeline:
- Estimated tax payments are due on a quarterly basis, typically spanning April 15, June 15, September 15, and January 15 of the following year.
- Partnerships should ensure they meet these deadlines to avoid penalties and interest charges.
Follow-Up Actions Post-Filing
Once the form is filed, partnerships should:
- Monitor for any notices or communications from the IRS regarding their submissions.
- Maintain detailed records of all calculations and documents submitted for future reference.
- Prepare for any adjustments or amendments that may be required based on changes in ECTI or partner status.
Addressing Potential Challenges: Errors and Appeals
Even with meticulous preparation, errors can occur during the filing process. Understanding how to rectify these missteps is crucial for partnerships.
Common Errors to Avoid
Here are some frequent pitfalls that partnerships should be wary of when completing Form 8804-W:
- Incorrect calculations that misrepresent tax liabilities.
- Failure to account for all foreign partners or their respective ECTI.
- Not adequately documenting state and local tax reductions.
What to Do If You Encounter Issues
If a partnership discovers an error post-filing, they should:
- File an amended form promptly to correct the information.
- Consult with a tax professional to ensure that the amendments comply with IRS guidelines.
- Prepare for potential follow-up communications from the IRS regarding the errors, including possible audits or inquiries.
Understanding Special Considerations: Variations in Partner Profiles
Each partnership may present unique challenges based on the types of partners involved. Here, we explore distinct cases:
Foreign Partners vs. Domestic Partners
Partnerships need to differentiate their calculations based on whether partners are foreign or domestic:
- Foreign partners are subject to different tax implications, which must be factored into the ECTI calculations on Form 8804-W.
- Domestic partners do not typically require this form unless they are part of a structure that has foreign partners.
Complex Partnerships
For partnerships involving multiple entities or complex ownership structures, additional steps may be necessary:
- Assessing all applicable income and deductions across different partners.
- Consulting with legal or tax professionals to navigate intricacies related to international tax treaties and obligations.
Preparing to Handle Diverse Situations
Every tax year can bring new circumstances, and partnerships must be prepared to adapt. This preparation is vital for compliance and strategic tax planning.
Emergencies and Unforeseen Circumstances
In the event that a partnership faces unexpected challenges, such as changes in partner status or sudden income fluctuations, they should proactively:
- Review any potential impacts on their tax obligations.
- Consult with experts to evaluate the necessity of adjusting their estimated tax payments.
- Document any changes or disruptions thoroughly to maintain compliance.
Leveraging Resources for Accuracy
Partnerships can utilize various resources to ensure accuracy and compliance:
- IRS guidelines and instructions accompanying Form 8804-W.
- Professional tax advisors who specialize in partnership taxation and foreign income.
- Online tools and calculators provided by reputable organizations to aid in estimating ECTI and tax liabilities.
Emphasizing Continuous Learning and Adaptation
The world of tax compliance is ever-evolving, especially for partnerships with international components. Staying informed about regulatory changes, new forms, or adjustments in tax laws is paramount.
Partnerships are encouraged to foster a culture of continuous education regarding tax obligations. This commitment can mitigate risks and streamline the filing process for Form 8804-W, positioning partnerships for success in their financial endeavors.
Understanding the Purpose of IRS Form F8804W
IRS Form F8804W, officially titled "Form 8804-W, Installment Agreement Request for Form 8804," is a vital document for partnerships that are required to pay tax on effectively connected income. This form is specifically meant for those partnerships that are considered "foreign partners" under U.S. tax law. It addresses the need for reporting and managing tax payments over time rather than as a lump sum. Understanding the intricacies of this form is essential for compliance and to ensure that foreign partners meet their tax obligations without incurring penalties.
Form F8804W comes into play primarily during the filing process when a partnership must report its effectively connected income and associated tax liabilities. This form allows partnerships to request an installment plan, making it easier for foreign partners to manage their tax dues without immediate financial burden. This can be particularly beneficial for partnerships that are new to the U.S. tax system or those that have fluctuating income levels. The IRS emphasizes that timely completion of Form F8804W can prevent possible penalties or interest charges that could accrue if taxes are not paid on time.
Eligibility and Requirements for Filing Form F8804W
Not all partnerships are eligible to file IRS Form F8804W. Specifically, the form is intended for partnerships that have foreign partners and are required to pay tax on effectively connected income. To determine eligibility, partnerships must first evaluate their liability under IRS regulations. A partnership must also be in good standing with the IRS, meaning that it has filed all necessary tax returns and resolved any outstanding tax issues prior to submitting Form F8804W.
Filing Form F8804W requires specific information, including the partnership's Employer Identification Number (EIN), the name and address of the partnership, and information about the foreign partners involved. Partnerships should gather their financial records to accurately report the amount of effectively connected income and the estimated tax liability. The instructions accompanying the form provide detailed guidance on how to calculate the tax due based on the partnership's income. Additionally, partnerships should be aware of the deadlines associated with filing this form, which typically coincides with the regular tax filing dates for the partnership's returns.
Common Pitfalls and How to Avoid Them When Filing Form F8804W
Filing IRS Form F8804W can be daunting, especially for partnerships unfamiliar with U.S. tax regulations. One of the most common pitfalls is failing to accurately report the effectively connected income, which can lead to discrepancies in the tax owed. It is crucial for partnerships to maintain meticulous financial records throughout the year to ensure that they can provide accurate figures on the form.
Another frequent error involves missing the filing deadline. Partnerships must keep track of not only the federal deadlines but also any state-specific requirements that may apply. Late submissions can result in penalties or interest charges, which can significantly increase the total amount owed. To mitigate these risks, partnerships can establish a filing calendar that includes reminders for both state and federal due dates.
Additionally, partnerships should be cautious about using outdated versions of the form. Tax laws and regulations change frequently, and using an obsolete version of Form F8804W can lead to compliance issues. Always ensure that you are using the latest version of the form, which can be found on the official IRS website. Seeking assistance from a tax professional familiar with U.S. tax law can also be beneficial in navigating the complexities associated with foreign partnerships and their tax obligations.