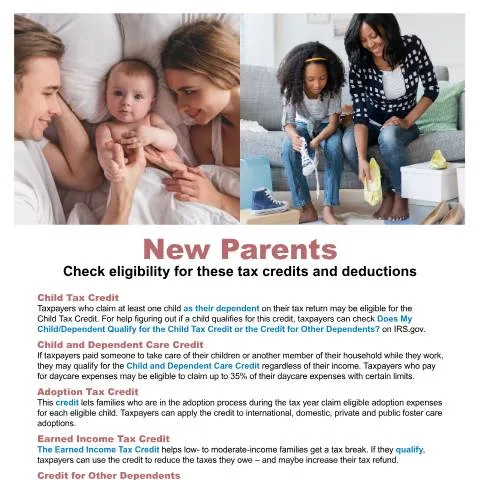
Unpacking IRS Publication 5851: A Comprehensive Guide for New Parents
When navigating the labyrinth of tax obligations and benefits, especially as a new parent, understanding IRS Publication 5851 can be pivotal. This document serves as a crucial resource for individuals seeking tax credits and deductions pertinent to their growing families. Let’s delve deeper into how this publication impacts parents, the steps involved in navigating it, and the nuances of the various benefits available.
The Target Demographic: Who Benefits from IRS Publication 5851?
New parents and guardians face a multitude of challenges, not least of which is the financial burden that comes with raising a child. IRS Publication 5851 is tailored for taxpayers who claim dependents, specifically children, on their tax returns. Here’s a detailed look at various profiles that may find this publication beneficial:
- Parents with Multiple Children: Families with more than one child can access various tax credits that add up significantly, such as the Child Tax Credit and the Earned Income Tax Credit.
- Single Parents: Single parents may particularly benefit from the Child Tax Credit and the Child and Dependent Care Credit, which can ease their financial load.
- Adoptive Parents: Families engaged in adoption can claim the Adoption Tax Credit, which covers eligible expenses incurred during the adoption process.
- Low to Moderate Income Families: The Earned Income Tax Credit is especially designed to assist families within this income range, providing a valuable tax relief.
Navigating the Process: From Claiming to Filing
Understanding how to effectively claim the benefits outlined in IRS Publication 5851 is essential. Each benefit described has specific eligibility criteria and application processes. Below is a chronological flow of actions a taxpayer may take:
- Assess Eligibility: Use the Does My Child/Dependent Qualify for the Child Tax Credit or the Credit for Other Dependents? tool available on IRS.gov to determine eligibility for various credits.
- Gather Documentation: Compile necessary documents, such as Social Security Numbers (SSNs) for all dependents, proof of income, and any expenses incurred that may qualify for credits.
- Complete Tax Forms: Fill out the appropriate forms, such as Form 1040, ensuring that you accurately report all dependent information to claim the Child Tax Credit.
- Submit Your Tax Return: Choose the method of submission — whether online via e-filing or by mailing in a paper tax return form.
- Await Processing: After submission, track your return status using the IRS 'Where's My Refund?' tool.
Calendar of Key Dates: When to Act
The timing of your actions can significantly impact the benefits you receive. Key dates to keep in mind include:
| Event | Date | Action Required |
|---|---|---|
| Start of Tax Filing Season | Typically Mid-January | Begin gathering documentation. |
| Tax Filing Deadline | April 15 | Submit your tax return. |
| Refund Tracking Begins | 24-48 hours after e-filing | Check refund status online. |
Mark these dates on your calendar to ensure you don’t miss crucial deadlines that could impact your tax benefits.
Dissecting the Details: Understanding Each Benefit
IRS Publication 5851 covers several significant tax credits, each with unique requirements and available amounts. Here’s a closer look:
Child Tax Credit
Designed to support families with children, this credit can significantly reduce tax liabilities. Eligibility criteria include:
- Claiming at least one child as a dependent.
- Income limits which may vary each tax year, so checking the latest thresholds is vital.
Child and Dependent Care Credit
If you pay for childcare expenses while working, this credit allows you to claim a percentage of those costs. Key points include:
- Eligible expenses include daycare, babysitting, and care for a dependent adult.
- The percentage you can claim varies based on your income.
Adoption Tax Credit
This credit helps alleviate the costs associated with adopting a child. Specifics to consider:
- Eligible expenses include court fees, attorney fees, and other adoption-related costs.
- Adoptions from foster care also qualify, expanding the scope of assistance.
Earned Income Tax Credit
This credit is particularly beneficial for low to moderate-income families and can result in a significant refund. Important considerations include:
- Eligibility depends on your filing status, income level, and number of qualifying children.
- Be aware of the income thresholds set for each tax year to determine your eligibility.
Submission Channels: The Best Way to File
Choosing the right method to submit your tax return can influence the speed and efficiency of processing. Here are the available options:
Online Filing
E-filing is considered the fastest way to submit your tax documents. Benefits include:
- Immediate confirmation of receipt.
- Faster processing times and refunds.
- Access to various tax preparation tools that can guide you through the credits.
Paper Filing
While traditional, paper filing can lead to delays. Considerations include:
- Longer processing times, especially for mailed documents.
- The potential for lost documents if not submitted correctly.
In-Person Submission
Some taxpayers prefer to file their returns in person, which can provide peace of mind. Pros include:
- Direct interaction with IRS representatives who can answer questions.
- Immediate feedback on any issues with your filing.
What Happens Next? Understanding the Aftermath of Filing
Once you’ve submitted your tax return and claimed the benefits, it’s critical to know what to expect:
- Processing Times: E-filed returns generally process faster, often within 21 days, while paper submissions can take significantly longer.
- Refunds: If you are due a refund, you can start tracking it online through the IRS portal within 24-48 hours after submission.
- Follow-Up Actions: If there are any discrepancies or issues, the IRS will contact you via mail to resolve the matter.
Dealing with Setbacks: What to Do in Case of Rejection
Not every submission is approved without contention. In cases where your claim is denied or incomplete:
- Understanding the Rejection: The IRS will provide a notice explaining the reason for denial. Familiarity with the process can help in addressing issues promptly.
- Correcting Errors: You can amend your return using Form 1040-X if you discover mistakes or need to add missing information.
- Document Your Communications: Keep detailed records of any correspondence with the IRS, as this may be necessary if disputes arise.
Navigating Complex Situations: Special Cases and Additional Resources
Not all taxpayers will fit the standard profiles described in IRS Publication 5851. Unique circumstances may warrant further investigation or assistance:
- Mixed-Status Families: Families with mixed immigration statuses may have different eligibility criteria for certain credits.
- Changes in Custody: Taxpayers who experience changes in custody arrangements need to understand how this affects dependency claims and tax credits.
- Consulting Experts: In complex cases, seeking assistance from a tax professional can provide clarity and ensure you maximize your eligible benefits.
In navigating the nuances of IRS Publication 5851, new parents can strategically position themselves to benefit from the available tax credits and deductions, easing the financial demands of parenthood. Understanding each step of the process—from eligibility assessment to submission and potential follow-up—empowers families to make informed financial decisions in their new roles.
Understanding IRS Publication 5851: A Comprehensive Overview
IRS Publication 5851 serves as a critical resource for taxpayers, particularly those involved in the tax-exempt sector. This publication specifically addresses the requirements and procedures for tax-exempt organizations, detailing how they can comply with federal tax regulations. The publication clarifies the criteria for obtaining and maintaining tax-exempt status under Section 501(c)(3) and other relevant sections of the Internal Revenue Code, emphasizing the importance of adhering to operational guidelines to preserve that status.
For example, organizations need to ensure that their activities align with the charitable purposes set forth in their foundational documents. Failure to do so could result in the revocation of tax-exempt status. Additionally, IRS Publication 5851 outlines essential record-keeping practices that organizations must implement to substantiate their claims of tax-exempt status. Good record-keeping not only aids in compliance but also facilitates a smoother audit process if the organization is selected for review by the IRS.
One of the significant aspects of IRS Publication 5851 is the emphasis on the importance of unrelated business income (UBI). Tax-exempt organizations must be aware that income generated from activities not directly related to their exempt purposes could be subject to taxation. The publication provides guidance on what constitutes UBI and how organizations can calculate and report this income accurately, ensuring they stay compliant with federal tax laws.
Key Changes in IRS Publication 5851: What You Need to Know
Tax regulations are dynamic, and IRS Publication 5851 is updated periodically to reflect changes in the law and IRS procedures. Staying informed about these updates is essential for organizations seeking to maintain their tax-exempt status. Recent revisions have clarified certain definitions and examples that may affect how organizations interpret their compliance obligations.
For instance, the latest edition of Publication 5851 has integrated new examples that demonstrate what constitutes acceptable fundraising activities for tax-exempt organizations. These examples offer practical insights, helping organizations navigate the complexities of fundraising while remaining compliant with IRS regulations. It’s crucial to review these amendments regularly, as they may affect operational practices, financial reporting, or strategic planning for tax-exempt organizations.
Additionally, the IRS has refined its guidance on the interactions between state and federal requirements for tax-exempt organizations. Understanding these nuances is vital, particularly for organizations operating across state lines, as they may face varying requirements. IRS Publication 5851 serves as a bridge to help organizations navigate these complexities, providing practical tools and resources.
Navigating Compliance: Best Practices for Tax-Exempt Organizations
Compliance is not merely about adhering to regulations; it involves a proactive approach to governance and operations within tax-exempt organizations. IRS Publication 5851 emphasizes that organizations should establish a compliance framework that includes policies and procedures for monitoring adherence to federal tax requirements. This framework should encompass training for board members and staff on the implications of tax-exempt status and the importance of compliance.
One practical best practice is the creation of a compliance checklist tailored to the specific activities of the organization. This checklist can serve as a guide for annual assessments and help ensure that all operational aspects align with IRS requirements. Additionally, organizations should consider implementing regular internal audits to evaluate compliance and identify potential areas of risk before they become significant issues.
Engaging with legal and financial advisors who specialize in nonprofit tax law is another recommended practice. These professionals can provide tailored guidance and assist in navigating the complexities of IRS Publication 5851. They can help organizations stay abreast of legislative changes and interpret how those changes affect their operations and compliance obligations.
Ultimately, a proactive stance on compliance helps organizations not only maintain their tax-exempt status but also enhances their credibility and trust among donors and the public. By implementing these best practices and utilizing IRS Publication 5851 as a foundational resource, tax-exempt organizations can thrive while fulfilling their mission and responsibilities.