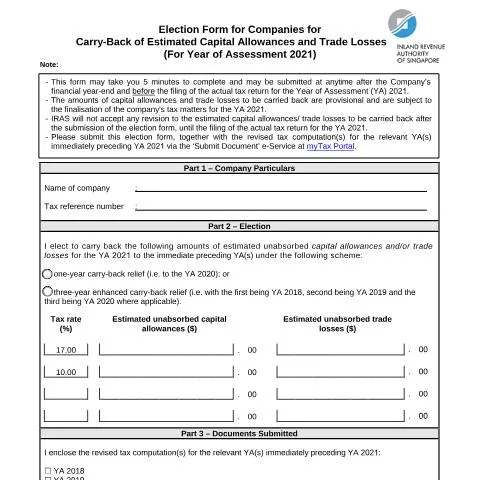
Introduction to the Election Form for Enhanced Carry-Back Relief System (Budget 2021)
The Election Form for Companies for Carry-Back of Estimated Capital Allowances and Trade Losses (Year of Assessment 2021) is an official document issued by the Inland Revenue Authority of Singapore (IRAS). This form allows eligible companies to elect for the carry-back of unabsorbed capital allowances and trade losses from the current Year of Assessment (YA 2021) to preceding YA(s), as part of the relief measures introduced under the Budget 2021.
Filing this form is a crucial step for companies aiming to optimize their tax position by leveraging past losses and allowances. Proper completion and submission can facilitate smoother processing of tax relief claims, ensuring compliance with the Singapore Income Tax Act and relevant tax regulations.
Who Should Fill Out This Form?
This form is intended for companies that have incurred unabsorbed capital allowances and trade losses in YA 2021 and wish to carry back these amounts to reduce taxable income in previous assessment years. Specifically, companies that have experienced losses or unused allowances in YA 2018, YA 2019, or YA 2020 and want to elect for relief under the enhanced carry-back scheme should complete this form.
It is important to note that the election is irrevocable once submitted. Therefore, companies should ensure the accuracy of their information and confirm their eligibility before filing.
How to Complete the Form
Part 1: Company Particulars
- Name of company: Enter the official registered name of the company.
- Tax reference number: Provide the company's Unique Entity Number (UEN) or other relevant tax reference.
Part 2: Election Details
In this section, companies must specify the relief scheme they are electing for:
- One-year carry-back relief: Carrying back to YA 2020.
- Three-year enhanced carry-back relief: Carrying back to YA 2018, YA 2019, and YA 2020.
Additionally, companies should declare the estimated amounts of unabsorbed capital allowances and trade losses, along with the applicable tax rate(s) for each year.
Part 3: Supporting Documents
Companies are required to submit revised tax computation(s) for the relevant YA(s) immediately preceding YA 2021, specifically for YA 2018, YA 2019, and YA 2020, as applicable. These computations should reflect the provisional amounts of capital allowances and trade losses to be carried back and are subject to finalization upon the actual tax filing.
The form can be completed and submitted at any time after the company's financial year-end but before the filing of the tax return for YA 2021. Submission is done electronically via the myTax Portal using the 'Submit Document' e-Service.
Declaration and Certification
By signing the form, the authorized person declares that:
- There has been no substantial change in the company's ultimate shareholders and their shareholdings as at the relevant dates.
- There has been no change in the company's trade or business activities as at the relevant dates.
The declaration affirms that the information provided is true and correct. The individual making the declaration must specify their full name, capacity, contact number, and date of signing.
It is important to understand that making false or incorrect declarations under the Singapore Income Tax Act can result in penalties.
Submission Process and Important Notes
The completed election form, along with the revised tax computations, should be submitted electronically through the myTax Portal. The submission must be made before the deadline for filing the YA 2021 tax return to ensure the carry-back relief is considered in the assessment process.
Amounts declared are provisional and subject to final adjustment upon the company's tax audit and final tax computation. IRAS will not accept revisions to the carry-back amounts after the form's submission, until the actual tax return for YA 2021 is filed.
For assistance or inquiries regarding this form, companies can contact IRAS at 1800-356 8622 or visit the official website at https://www.iras.gov.sg.