Understanding the Group Relief Form for Claimant Companies (Form GR-B) in Singapore
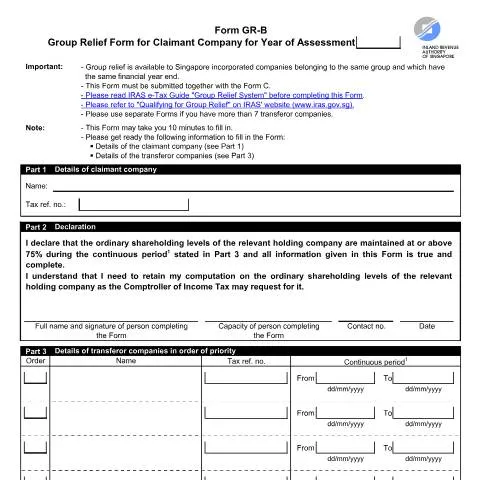
The Group Relief Form for Claimant Company (Form GR-B) is an official document issued by the Inland Revenue Authority of Singapore (IRAS). It facilitates the process for Singapore-incorporated companies to claim group relief for the same assessment year, provided they meet specific criteria. This form is an essential component of the group relief system designed to streamline tax management within corporate groups.
Purpose and Scope of the Form
The primary objective of Form GR-B is to enable a claimant company to declare its entitlement to group relief by transferring unutilized losses or qualifying allowances from transferor companies within the same group. To qualify, both the claimant and transferor companies must be incorporated in Singapore, belong to the same group, and share the same financial year end.
It is important to note that this form must be submitted together with the company's annual tax return, specifically with Form C. The IRAS e-Tax Guide titled "Group Relief System" provides comprehensive guidance on eligibility criteria and procedures. Companies intending to claim relief should review the IRAS website section on "Qualifying for Group Relief" for detailed information.
Preparing to Complete the Form
Completing the Form GR-B requires gathering specific details about the claimant and transferor companies:
- Details of the claimant company, including its tax reference number and contact information.
- Details of up to seven transferor companies, including their names, tax reference numbers, and the relevant periods for which relief is claimed.
Companies with more than seven transferor companies should prepare separate forms for each group of transferors, as the form is limited to a maximum of seven transferor companies per submission.
Step-by-Step Guide to Filling Out the Form
Part 1: Claimant Company Details
Provide the full name of the claimant company, its tax reference number, and the name and signature of the person completing the form. The capacity of the individual (e.g., director, accountant) should also be specified, along with a contact number.
Part 2: Declaration
The declarant must affirm that the company's ordinary shareholding levels in the relevant holding company are maintained at or above 75% throughout the specified continuous period. This declaration is crucial as it confirms the company's eligibility for group relief.
Part 3: Transferor Companies Details
List each transferor company in order of priority, providing their names, tax reference numbers, and the relevant period for which the relief is being claimed. The form requires precise date ranges to establish the continuous period during which the shareholding threshold was maintained.
Submission and Important Considerations
The completed Form GR-B must be submitted electronically via the IRAS myTax Portal, ensuring that it is attached to the corresponding Form C. The submission should be made within the stipulated deadlines for the assessment year.
Accuracy and completeness are vital, as making false or incorrect declarations can lead to penalties under the Singapore Income Tax Act 1947. IRAS recommends retaining detailed computations of shareholding levels, as they may request supporting documentation during audits or reviews.
Follow-Up and Record-Keeping
After submission, companies should retain copies of the completed form and relevant supporting documents for at least five years, as IRAS reserves the right to request verification at any time. Maintaining accurate records ensures smooth processing and facilitates any future amendments or audits.
Contact and Assistance
For further assistance, companies can contact IRAS via their helpline at 1800-356 8622 or consult the official website at www.iras.gov.sg. The IRAS e-Tax Guide "Group Relief System" offers detailed instructions and clarifications to support taxpayers in completing the form correctly.
In conclusion, the Group Relief Form (Form GR-B) is a vital tool for Singapore companies seeking to optimize their tax position through intra-group relief. Proper preparation, accurate completion, and timely submission ensure compliance with IRAS requirements and facilitate efficient tax management within corporate groups.