Understanding the Filing of Returns and Payment Responsibilities
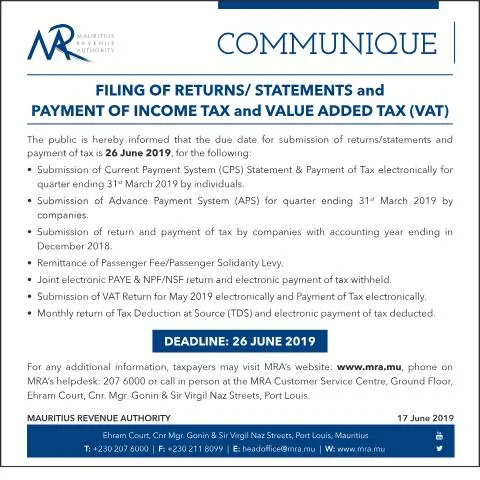
In the complex landscape of taxation in Mauritius, individuals and businesses alike face the crucial task of ensuring compliance with tax obligations. The document known as the "Filing of Returns / Statements and Payment of Income Tax and Value Added Tax (VAT)" is pivotal within this framework. Released by the Mauritius Revenue Authority (MRA) on 17 June 2019, it outlines essential procedures and deadlines for one’s tax liabilities. Neglecting to adhere to these guidelines can lead to penalties, making comprehension and timely submissions paramount.
The Importance of Timely Compliance
Each year, the fiscal cycle imposes specific deadlines for the submission of various tax returns and payments. For instance, the critical deadline for submission and payment relating to the quarter ending on 31 March 2019 was 26 June 2019. This date encompasses multiple obligations, including:
- Current Payment System (CPS) Statement for individuals
- Advance Payment System (APS) for companies
- Company returns for those with an accounting year ending in December 2018
- Remittance of Passenger Fee and Solidarity Levy
- Joint electronic PAYE and NPF/NSF return
- Submission of VAT Return for May 2019
- Monthly Tax Deduction at Source (TDS) return
Being aware of these obligations allows taxpayers to plan their finances effectively, avoiding unnecessary interest or penalties due to late submissions.
Decoding the Form Structure
The form in question contains distinct sections that require careful attention. Understanding each part is essential for ensuring complete and accurate submissions. Below are the primary components typically included in the filing.
Section by Section Breakdown
1. Personal Information:
This section requests foundational details, such as the taxpayer’s name, National ID number, and contact information. Ensure that the information matches the official records to prevent discrepancies.
2. Income Details:
Taxpayers must declare their total income from all sources. Accuracy here is vital, as underreporting can lead to severe penalties. Include all forms of income, such as salaries, rental income, and dividends.
3. Deductions:
This section allows for specific deductions that can lower the taxable income. Examples include contributions to retirement funds and qualifying medical expenses. It’s advisable to keep detailed records of these deductions.
4. Tax Calculation:
A clear calculation of tax owed must be provided. Follow the prescribed rates for income tax and VAT. If uncertain, consult the MRA guidelines or a tax professional to ensure calculations align with current laws.
5. Submission and Payment:
Finally, taxpayers must indicate the method of payment—whether through online banking, cheque, or cash at designated payment centres. Each method has its own processing times and fees.
Navigating Submission Channels
One of the key aspects of complying with tax obligations is the choice of submission channel. The MRA offers multiple avenues for submitting forms, each with distinct advantages and procedures.
Online vs. Paper Submissions
Online Submission:
Utilizing the e-filing system via the MRA’s online platform (govmu.org) is highly encouraged. The advantages include:
- Immediate confirmation of receipt
- Automatic calculation features
- Reduced risk of human error
To file online, taxpayers must have a MauPass account linked to their National ID. This single-sign-on system streamlines access to various government services while ensuring data security.
Paper Submission:
While online submission is preferable, submitting a paper form is still a valid option. However, it entails:
- Potential delays in processing
- Risks of lost documents
- Manual entry into the MRA system, increasing the chance of errors
Individuals opting for paper submission should ensure that forms are sent via registered mail or delivered in person, retaining a copy for their records.
What Happens After Submission?
After submitting tax returns, taxpayers may wonder what the subsequent steps involve. It is crucial to track the status of submissions and address any follow-ups.
Post-Submission Procedures
Processing Time:
Typically, the MRA will process returns within a few weeks. However, this can vary based on the complexity of the return and the volume of submissions received.
Follow-Up:
Taxpayers should maintain communication lines open with the MRA, especially if they do not receive confirmation of their submission. The helpdesk can be reached at +230 207 6000, or taxpayers may visit the Customer Service Centre located at Ehram Court, Port Louis.
Dealing with Queries
If discrepancies arise or if the MRA requests additional documentation or clarifications, it is imperative to respond promptly and accurately. Keeping a detailed log of all communications with the tax authority will facilitate smoother resolutions.
Special Circumstances and Considerations
Certain taxpayers may find themselves in unique situations that complicate their tax filing. Understanding the nuances is essential to navigate these complexities effectively.
Foreign Nationals and Tax Filing
For foreign residents or non-residents earning income in Mauritius, specific provisions apply. It’s important to determine residency status, as tax obligations differ significantly based on this classification.
- Non-residents may only be taxed on income sourced within Mauritius.
- Documentation proving income sources may be required to claim any applicable deductions.
Minors and Taxation
Minors earning income are subject to the same tax regulations as adults. However, any income earned must be reported by a parent or guardian.
Urgent Cases
In situations such as imminent deadlines or financial hardship, taxpayers should consult directly with the MRA. There are provisions in place for extensions or reduced penalties in cases of genuine difficulty, provided that proper documentation is submitted.
Comparative Analysis with Other Forms
The "Filing of Returns / Statements and Payment of Income Tax and VAT" form may be confused with other official documents. Understanding the differences is crucial for appropriate filing.
| Form Type | Purpose | Deadline |
|---|---|---|
| CPS Statement | For individuals' quarterly tax payments | Varies; typically 26th of the month following the quarter |
| APS Statement | For companies' quarterly tax payments | Varies; typically 26th of the month following the quarter |
| VAT Return | Reporting sales and VAT liabilities | 26th of the month following the taxable period |
| Income Tax Return | Annual income reporting for individuals and businesses | Typically 30 September following the end of the fiscal year |
By distinguishing these forms, taxpayers can avoid confusion and ensure compliance with their respective obligations.
Resources for Successful Filing
To navigate the obligations associated with the "Filing of Returns / Statements and Payment of Income Tax and VAT," taxpayers are encouraged to explore the resources provided by the MRA.
Official Guidance and Assistance
The MRA’s official website (www.mra.mu) serves as a comprehensive resource for downloadable forms, guides, and essential contact information. The helpdesk is accessible for immediate assistance, while interactive features on the website can streamline the filing process.
Professional Advice
In complex scenarios, consulting a tax professional can yield significant benefits. Engaging a qualified accountant can facilitate compliance, especially in cases involving foreign income, deductions, and intricate tax liabilities.
Next Steps for Taxpayers
Having a clear understanding of the intricacies involved in the "Filing of Returns and Payment of Income Tax and VAT" is vital for successful compliance. The next steps include:
- Reviewing personal financial records in preparation for filing.
- Obtaining any necessary documentation to support deductions and claims.
- Choosing a submission method that best aligns with individual circumstances.
- Staying informed about any changes in tax regulations or deadlines by checking the MRA website regularly.
By proactively managing tax obligations, individuals and businesses can ensure they remain in good standing with the MRA, ultimately contributing to the financial health of the nation.
Understanding the Income Tax Filing Process in Mauritius
Filing your income tax return in Mauritius is a crucial process for all individuals and entities subject to taxation. The Mauritian tax year runs from 1 July to 30 June of the following year, which means that taxpayers need to ensure their returns are submitted in a timely manner. The MRA requires that all tax returns are filed online through their e-filing system, making it essential for taxpayers to have access to the necessary technology and an understanding of the portal.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
To initiate the filing process, you will need to gather all relevant documents, including your National Identity Card (for individuals), financial statements, and any other supporting documents that may be required. The MRA typically requires the following forms to be filled out:
- MRA Form IT1: For individual taxpayers.
- MRA Form IT2: For companies and other legal entities.
- MRA Form VAT1: For VAT-related filings.
Once you have collected the required documents, log in to the MRA's e-filing system using your MauPass credentials, which are linked to your National ID. This single sign-on feature simplifies access and ensures that your personal information is securely managed through the Central Population Database. When completing the forms, pay close attention to the details as inaccuracies can lead to delays or penalties.
After completing the forms, review them for completeness before submission. You must ensure that your income is accurately reported and that all deductions and credits you are eligible for are claimed. The deadline for submission is typically set for 30 September following the end of the tax year, although extensions may be granted under specific circumstances. Failure to file on time can result in fines and interest on unpaid taxes.
How to Handle VAT Filings for Businesses
For businesses operating in Mauritius, understanding the Value Added Tax (VAT) obligations is paramount. VAT is levied on the supply of goods and services at various stages of production and distribution. As of the current fiscal year, the standard VAT rate in Mauritius is 15%, and businesses must file their VAT returns regularly, typically on a monthly or quarterly basis depending on their turnover.
Businesses must register for VAT if their taxable turnover exceeds MUR 2 million over a 12-month period. To begin the VAT registration process, businesses should complete the MRA Form VAT2, which requires comprehensive details about the business structure and financials.
Once registered, businesses must maintain accurate records of all sales and purchases to correctly calculate their VAT liabilities. It is crucial to keep copies of invoices, receipts, and any other relevant documents for at least five years, as these may be required during audits conducted by the MRA.
VAT returns must be submitted electronically through the MRA's e-filing system, and businesses should ensure they are familiar with the filing deadlines. The typical filing period aligns with the end of the month following the tax period. Businesses that fail to submit their VAT returns on time may incur penalties, including fines and interest on late payments.
When submitting VAT returns, companies must accurately report the output tax collected on sales and the input tax incurred on purchases. If a business’s input tax exceeds its output tax, it may be eligible for a VAT refund, which requires the completion of MRA Form VAT3 to claim. Understanding these nuances is vital for effective VAT management and compliance.
Common Pitfalls and How to Avoid Them in Tax Filing
Filing tax returns can be a daunting task for many individuals and businesses in Mauritius. However, awareness of common pitfalls can significantly enhance the filing experience and compliance. One major pitfall is the failure to submit the correct forms. It is essential to use the appropriate MRA forms and ensure that they are suited to your tax situation, whether you are filing as an individual or a business entity.
Another common issue is the misreporting of income or expenses. Taxpayers should ensure that all income is accurately reported, including income from investments, side businesses, and other sources. Similarly, deductions must be backed by valid documentation. In some cases, taxpayers attempt to claim deductions for non-eligible expenses, resulting in penalties during audits.
Moreover, many individuals and businesses overlook tax credits and reliefs available to them. For instance, the MRA offers various tax reliefs for specific expenses such as charitable donations, medical expenses, and education-related costs. Familiarizing oneself with these credits can lead to significant tax savings.
Lastly, not keeping track of deadlines can lead to missed submissions and resulting fines. Taxpayers are encouraged to mark important dates on their calendars, including the deadlines for both income tax and VAT returns. Utilizing the MRA’s digital reminders can also help mitigate this risk.
To sum up, understanding the filing of returns, adhering to local tax regulations, and avoiding common mistakes will enhance compliance and reduce the potential for penalties. Engaging with tax professionals or consultants can also provide additional support in navigating the complexities of Mauritian tax law.