Overview of the Fair Share Contribution (FSC) for Companies in Mauritius
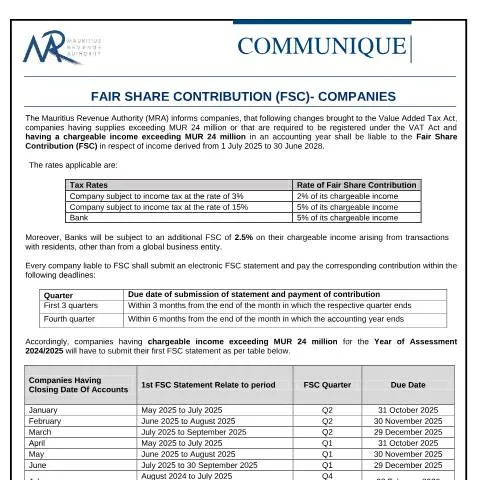
The Mauritius Revenue Authority (MRA) has issued a formal notice concerning the implementation of the Fair Share Contribution (FSC) applicable to certain companies for the fiscal years starting from 1 July 2025 through 30 June 2028. This measure is part of the recent amendments to the Value Added Tax (VAT) Act, aiming to ensure a fair contribution from corporations based on their income and specific financial thresholds. This guide provides essential information for affected companies, outlining eligibility, rates, filing obligations, and deadlines.
Scope and Applicability of the FSC
The FSC is a new fiscal obligation targeting companies with significant turnover and income levels. Specifically, companies that meet the following criteria are liable to the contribution:
- Having supplies exceeding MUR 24 million in the relevant accounting period, or
- Requiring registration under the VAT Act and generating a chargeable income exceeding MUR 24 million within an accounting year.
These thresholds ensure that the FSC primarily affects larger corporations, including those engaged in substantial commercial activities or financial operations.
Applicable Rates and Taxation Details
The contribution rates are differentiated based on the company's income tax rate and sector. The rates are as follows:
- For companies taxed at 3%, the FSC rate is 2% of chargeable income.
- For companies taxed at 15%, the FSC rate is 5% of chargeable income.
- Banks are subject to an FSC rate of 5%, with an additional 2.5% on income derived from transactions with residents, excluding global business entities.
It is important to note that the additional FSC for banks applies specifically to income from resident transactions, reflecting the sector’s unique financial activities.
Filing and Payment Procedures
All liable companies must submit an electronic FSC statement and settle the corresponding contribution. The process is governed by specific deadlines based on the company's fiscal quarter and year-end closing date:
- For each of the first three quarters, submission and payment are due within three months after the end of the respective quarter.
- The final quarter's declaration and payment are due within six months after the end of the company's accounting year.
The electronic submission is facilitated through the MRA's official online portal, which is integrated with the Mauritian Single Sign-On system tied to the National ID Card and Central Population Database. This digital approach aims to streamline compliance and reduce administrative burdens.
Specific Deadlines for the 2024/2025 Assessment Year
Companies with a fiscal year ending between July 2024 and September 2025 will need to adhere to the following FSC declaration deadlines:
| Company's Financial Year End | FSC Quarter | Due Date for Submission and Payment |
|---|---|---|
| January – May 2025 | Q2 | 31 October 2025 |
| February – June 2025 | Q2 | 30 November 2025 |
| March – July 2025 | Q2 | 29 December 2025 |
| April – August 2025 | Q1 | 31 October 2025 |
| May – September 2025 | Q1 | 30 November 2025 |
| June – September 2025 | Q1 | 29 December 2025 |
| July 2024 – July 2025 | Q4 | 02 February 2026 |
| August 2024 – August 2025 | Q4 | 02 March 2026 |
| September 2024 – September 2025 | Q4 | 31 March 2026 |
Further Information and Assistance
For comprehensive guidance on the FSC process, including access to the online submission platform and detailed instructions, companies are encouraged to visit the official Mauritius Revenue Authority website at www.mra.mu. Additionally, support can be obtained by contacting the MRA Helpdesk during working hours at +230 207 6000 or via email at [email protected].
The introduction of the FSC aims to foster a fair and equitable fiscal environment, ensuring that larger corporations contribute their fair share to the national development efforts. Companies are advised to stay informed of their obligations and adhere strictly to the prescribed deadlines to avoid penalties or interest charges.