Navigating the Return of Income Form [4R15]: A Comprehensive Guide
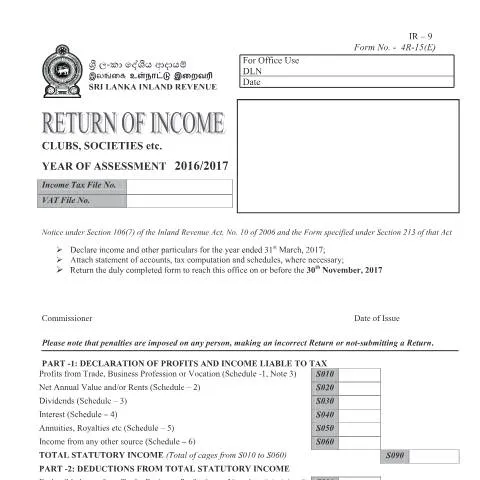
In the realm of Sri Lanka's financial landscape, the Return of Income - Form [4R15] stands as a crucial document for Clubs and Societies. This form is a legal obligation for entities generating income and plays a pivotal role in the tax assessment process. Understanding the nuances of this form can be the difference between compliance and facing penalties. As 30th November approaches, it becomes essential for organizations to prepare effectively and understand what lies ahead.
The Importance of Filing: What is at Stake?
For organizations operating under the Clubs and Societies category, the Return of Income Form [4R15] is not merely a bureaucratic hurdle; it is a vital component of financial transparency and accountability. The declaration of income not only reflects the organization’s financial health but also directly impacts tax obligations. Failure to submit this form can lead to severe consequences, including:
- Financial Penalties: Incorrect or late submissions attract penalties under the Inland Revenue Act.
- Legal Implications: Non-compliance may result in legal action or a loss of operational privileges.
- Loss of Credibility: Trustworthiness can be undermined among stakeholders, affecting funding and partnerships.
Thus, ensuring accuracy and timeliness in filing the Return of Income is not just compliance; it is critical for safeguarding the organization’s future.
Understanding the Document Structure: A Breakdown
At first glance, the Return of Income Form [4R15] may seem daunting due to its detailed structure. However, breaking it down section by section sheds light on the necessary information required and simplifies the process significantly. Below is a detailed look at each part of the form:
Part 1: Declaration of Profits and Income Liable to Tax
This section lays the foundation for the financial reporting of the organization. It includes various income categories:
- Profits from Trade, Business Profession or Vocation: Should be reported from Schedule - 1.
- Rents and Net Annual Value: Referenced in Schedule - 2, detail any property income here.
- Dividends and Interest: This encompasses Schedule - 3 and Schedule - 4 respectively.
- Other Sources of Income: Any additional income must be declared in Schedule - 6.
Accurate reporting in this section is crucial as it sets the stage for calculating taxable income.
Part 2: Deductions from Total Statutory Income
In this segment, organizations can claim deductions that can help lower their taxable income. The relevant deductions include:
- Deductible losses from Trade or Business: Reported in Schedule - 7, if applicable.
- Interest and Annuity Payments: Captured in Schedule - 8, if the organization has such liabilities.
Understanding what qualifies as a deduction can significantly reduce the organization's taxable income, making this part a vital area for careful scrutiny.
Part 3: Calculation of Income Tax Payable
This portion is pivotal as it translates declared income into specific tax obligations. Organizations must compute:
- Gross Income Tax Payable: This is calculated by applying the relevant tax rate to the taxable income.
- Tax Credits: Any applicable credits must be subtracted to determine the final tax liability.
Failure to accurately calculate these figures can lead to overpayment or underpayment, both of which have implications for the organization.
Filing Channels: Your Options for Submission
When it comes to submitting the Return of Income Form [4R15], entities have several options that cater to different needs and preferences:
- Online Submission: Utilizing the platforms available at forms.gov.lk allows for a streamlined process, with instant confirmations and tracking options.
- Paper Submission: Organizations may opt for traditional methods, ensuring that forms are mailed or handed in directly to the relevant authorities.
- In-Person Consultations: For those needing assistance, visiting the local Inland Revenue Department can provide clarity and guidance.
Each method has its pros and cons, and organizations should choose based on their capabilities and required support.
Chronological Flow: From Preparation to Compliance
Understanding the sequence of steps involved in filing the Return of Income [4R15] can aid organizations in managing their compliance effectively. Here’s the typical flow:
- Data Collection: Gather all necessary documents, including financial statements, previous returns, and supporting schedules.
- Completion of the Form: Carefully fill out the form, ensuring accuracy and thoroughness in all sections.
- Review and Approval: Have the completed form reviewed by relevant stakeholders or financial officers within the organization.
- Submission: Choose the preferred filing method and submit the form to the appropriate authorities.
- Post-Submission Follow-Up: Confirm receipt and monitor for any communication from the Inland Revenue Department regarding the submission.
This structured approach minimizes the risk of errors and ensures compliance is met efficiently.
Common Pitfalls: Navigating the Complexities
While completing the Return of Income Form [4R15], organizations often encounter several challenges that can lead to complications:
- Misclassification of Income: Ensure that each income source is reported in its correct category to avoid discrepancies.
- Incomplete Documentation: Attach all necessary statements and schedules as required, or risk penalties for incomplete submissions.
- Ignoring Deductions: Failing to include eligible deductions can inflate taxable income unnecessarily.
By being vigilant and proactive, organizations can navigate these common pitfalls and ensure a smooth filing process.
Final Thoughts: The Road Ahead After Submission
Once the Return of Income Form [4R15] has been successfully submitted, the organization enters a new phase. It is important to be aware of the following:
- Awaiting Assessment: The Inland Revenue Department will review the submitted information and may reach out for further clarification.
- Tax Payments: Ensure that any tax due is paid before the specified deadlines to avoid additional penalties.
- Record Keeping: Maintain copies of the submitted forms and all supporting documents for future reference and audits.
Staying organized and informed will be critical in managing ongoing compliance and fostering a reputation of transparency within the community.
Conclusion: Embracing Responsibility
The Return of Income Form [4R15] is not just a governmental obligation but a commitment to responsible financial management. By understanding the intricacies of this document and the implications of its submission, Clubs and Societies can better position themselves for success. As the deadline approaches, it is imperative that organizations ensure their compliance, safeguarding their operations and upholding their reputations for integrity.
Understanding the Filing Process for Return of Income
The process of filing a Return of Income in Sri Lanka is not merely a formality; it is a critical obligation for individuals and entities that generate income. The Return of Income is a document that outlines your earnings and tax liabilities for the financial year. The due date for submission typically falls on the last day of October, although specific conditions and exceptions may apply depending on the nature of the taxpayer's income. To ensure compliance, taxpayers should familiarize themselves with the different forms applicable to their income sources. For instance, Form B is designated for individuals, while companies may need to submit Form C.
To initiate the filing procedure, taxpayers must access the relevant form from the official webpage managed by the Department of Inland Revenue (DIR). It's vital to have a valid National Identity Card (NIC) for identification purposes, as the NIC is essential in all tax-related transactions in the country. For those opting for the digital route, the Electronic Transaction Act facilitates the use of digital forms available through forms.gov.lk. This online system aims to streamline processes and enhance efficiency in tax administration.
After completing the Return of Income, one must submit the document either online or through a physical submission at the local DIR office. For online submissions, ensure that all necessary documents, such as proof of income, deductions, and any relevant certificates, are scanned and uploaded as required. The DIR may request additional documentation for verification, so maintaining accurate records is crucial. Failure to comply with the filing deadline can result in penalties, increasing the urgency of understanding the specifics of your obligation.
Common Challenges and Solutions in Filing Returns
Despite the clear guidelines for the Return of Income, many taxpayers face challenges that can complicate the filing process. One common issue is the lack of proper documentation and misunderstanding of income sources. Taxpayers must be aware that all forms of income—salaries, business income, rental income—must be reported accurately. Misreporting can lead to audits and penalties, further stressing individuals and businesses.
Another obstacle relates to the calculation of taxable income and allowable deductions. Taxpayers often find it difficult to interpret the various tax laws and provisions governing deductions such as medical expenses, educational expenses, or contributions to approved pension funds. Engaging a qualified accountant or tax practitioner can significantly alleviate this burden, providing clarity on what can be deducted legitimately. Additionally, taxpayers can attend workshops or seminars conducted by the Department of Inland Revenue, which can offer insights into calculating taxes effectively and understanding current tax laws.
Technical issues with the online filing system can also pose a challenge, such as website outages or difficulties with the upload process. In such cases, it is advisable to contact the DIR's helpdesk for real-time assistance. Maintaining a proactive approach by beginning the filing process early can provide ample time to resolve such issues before the deadline.
Taxpayer Assistance and Resources Available
The Sri Lankan government has initiated several resources designed to assist taxpayers in navigating the Return of Income process. The Department of Inland Revenue provides comprehensive guides and resources on its website, including downloadable forms, instructional videos, and FAQs that cover common inquiries about tax obligations. For those unfamiliar with the tax system, these resources can serve as valuable tools to ensure compliance.
Additionally, taxpayers can take advantage of the services provided by the Institute of Chartered Accountants of Sri Lanka (ICASL). The ICASL frequently offers training sessions, online webinars, and workshops focused on taxation, including how to effectively complete the Return of Income. Such educational opportunities not only enhance understanding but empower taxpayers to make informed decisions regarding their tax affairs.
Besides formal resources, there is also a wealth of community-based support available. Local clubs and societies often host informational sessions and discussions regarding tax planning and compliance, allowing taxpayers to share experiences and solutions. Networking within these community groups can provide additional insights and practical advice on preparing and submitting the Return of Income.