Understanding the Tax Status of Commissions Related to Insurance Contracts in Jamaica
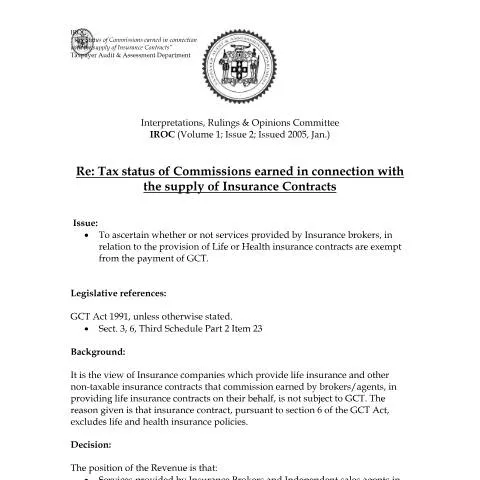
The official document titled 2005 IROC.GCT - Tax Status of Commissions earned in connection with the supply of Insurance Contracts issued by the Taxpayer Audit & Assessment Department (TAAD) provides essential guidance for insurance brokers, agents, and insurance companies operating within Jamaica. This comprehensive guide clarifies whether commissions earned through insurance activities are subject to General Consumption Tax (GCT) under Jamaican law, specifically the GCT Act 1991.
Objective of the Document
The primary purpose of this document is to determine the tax obligations of insurance intermediaries—such as brokers and independent sales agents—in relation to commissions earned from insurance contracts. It aims to clarify whether these commissions are classified as taxable supplies subject to GCT or whether they are exempt, especially considering the type of insurance involved, such as life or health insurance policies.
Legal Framework and Key Provisions
The interpretation relies on specific sections of the GCT Act 1991, notably:
- Section 3, which defines taxable activities;
- Section 6, outlining exemptions for certain insurance services;
- Third Schedule Part 2, which details activities exempt from GCT, including services rendered under health and life insurance contracts.
Tax Status of Commissions on Insurance Contracts
Position of Insurance Companies vs. Revenue Department
Insurance companies providing life and health insurance policies argue that commissions earned by brokers or agents are not subject to GCT. Their reasoning is based on the exclusion of life and health insurance policies from the scope of taxable supplies under section 6 of the GCT Act.
Conversely, the Revenue Department's position is that:
- All services provided by insurance brokers and independent sales agents in connection with insurance contracts are considered taxable supplies.
- Insurance providers are responsible for remitting GCT on commissions earned by these intermediaries.
Definition of Insurance Contracts
An insurance contract is defined as a legal agreement where one party indemnifies another against loss, damage, or liability arising from future, contingent events. This includes life, property, casualty, health, and reinsurance policies issued by licensed insurers in Jamaica.
Implications for Insurance Intermediaries
Taxable vs. Exempt Activities
While services under health and life insurance contracts are generally exempt from GCT, commissions earned by self-employed or independent agents are explicitly excluded from exemption under paragraph 13 and 23 of the Third Schedule Part 2 of the GCT Act. Therefore, intermediaries earning commissions from these activities are typically liable to pay GCT on their earnings.
Time of Supply and Payment
According to the regulations, the supply of taxable services, including commissions, is deemed to occur at the time when payment is received by the broker or agent. This timing is crucial for compliance and accurate GCT remittance.
Practical Guidance for Compliance
Registration and Filing
Insurance intermediaries earning commissions must be registered for GCT if their annual turnover exceeds the registration threshold specified by TAAD. They are required to file periodic GCT returns, typically monthly, and remit the applicable tax by the prescribed deadlines.
Documentation and Record-Keeping
It is essential for intermediaries to maintain detailed records of commissions earned, payments received, and GCT remitted. Proper invoicing and documentation facilitate compliance and ease audits by tax authorities.
Contact and Further Assistance
For specific questions regarding the application of GCT to insurance commissions or assistance with registration and filing, intermediaries should contact the Jamaica Tax Authority’s Taxpayer Audit & Assessment Department or consult a qualified tax professional familiar with Jamaican tax law.
Understanding the tax obligations related to insurance commissions is vital for compliance and avoiding penalties. This official guidance aims to clarify responsibilities and streamline the tax process for insurance industry stakeholders in Jamaica.