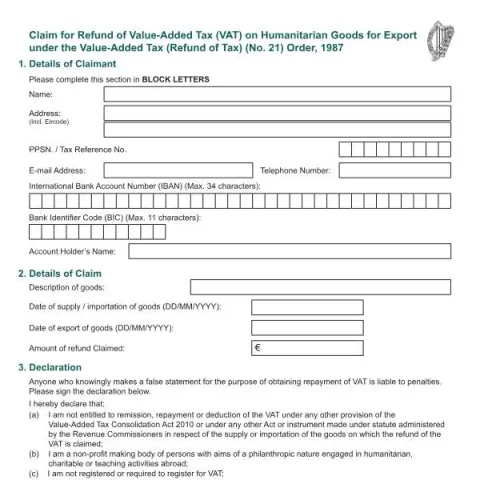
Understanding the VAT 73 Claim Form for Humanitarian Goods Export Refund in Ireland
The VAT 73 form is an official document issued by the Office of the Revenue Commissioners in Ireland, designed specifically for entities seeking a refund of Value-Added Tax (VAT) paid on humanitarian goods that are exported from Ireland. This form is part of the legal framework established under the Value-Added Tax (Refund of Tax) (No. 21) Order, 1987. It serves a crucial role for non-profit organisations and humanitarian bodies engaged in exporting goods abroad for philanthropic purposes, ensuring they can recover VAT paid during their import or purchase process.
Purpose and Scope of the VAT 73 Form
The primary purpose of the VAT 73 claim form is to facilitate the reimbursement of VAT on goods that are intended for humanitarian use and are exported within Ireland. This process helps reduce the financial burden on non-profit organisations involved in international aid activities, enabling them to allocate more resources directly to their humanitarian missions.
The form is applicable exclusively to goods that meet the criteria of being exported from Ireland within four months of their supply or importation. It is specifically targeted at non-profit entities that are not registered or required to register for VAT, such as charitable organisations, religious groups, or educational institutions engaged in humanitarian activities abroad.
Key Conditions and Eligibility Criteria
- Export Timing: Goods must be exported within four months from the date of supply or importation into Ireland.
- Claim Period: Applications must be submitted within four years from the end of the taxable period in which the goods were supplied or imported.
- Organisation Status: The claimant must be a non-profit body with aims of a philanthropic nature, engaged in activities abroad such as humanitarian, charitable, or teaching efforts.
- VAT Registration: The claimant should not be registered for VAT or should not be required to register under Irish VAT law.
- Supporting Documentation: Original invoices showing VAT paid, customs export documentation, and receipts must be attached to substantiate the claim.
Step-by-Step Guide to Completing the Form
1. Filling Out the Claimant Details
In section 1, the claimant must provide their full name, address (including Eircode), PPSN or tax reference number, email, telephone contact, and bank details. Accurate and legible information ensures smooth processing of the claim.
2. Providing Details of the Exported Goods
Section 2 requires a clear description of the goods, along with the dates of supply/importation and exportation. The claimed refund amount should be entered in euros, based on the VAT paid on the goods.
3. Declaration and Signature
The claimant must sign and date the declaration, affirming the truthfulness of the information provided and confirming eligibility. The declaration also emphasizes that the claimant is not entitled to any other VAT remission or deduction for the same goods.
Important Submission Guidelines and Deadlines
Before submitting the VAT 73 form, ensure the following:
- All sections (1 to 3) are completed and signed.
- Supporting documents, such as original invoices, customs export documents, and receipts, are attached.
- Invoices are legible, dated, and detail the VAT content, supplier information, and description of goods.
Claims must be submitted within four years of the end of the relevant taxable period. The completed form and supporting documentation should be sent to:
Collector-General’s Division, Office of the Revenue Commissioners, Sarsfield House, Francis Street, Limerick, V94 R972.
Fill in your form directly online
No printing: type your details into the boxes of the official form, tick, then download the PDF ready to send.
- 1Type into the form boxes
- 2Tick in one click
- 3Save and download the PDF
Processing and Follow-Up
After submission, the claim undergoes examination by Revenue officials. They verify the documentation and assess the eligibility based on legal criteria. The processing time can vary, but applicants are advised to keep copies of all submitted documents. Once approved, the refund is issued directly to the bank account details provided in the application.
Additional Considerations
It is important to note that the VAT 73 form is an official legal document; providing false information can lead to penalties under Irish law. Therefore, accuracy and honesty are paramount when completing the form. Also, applicants are encouraged to retain copies of all documents for their records and potential audits.
For further information or to obtain additional copies of the form, applicants can visit the Revenue website or contact the Collector-General’s Division directly. Ensuring compliance with the outlined procedures will facilitate a smooth and efficient refund process for humanitarian organisations operating in Ireland.